Viatris (VTRS) Navigates Mixed Q3: Is This the Turning Point for a Stable Uptrend?
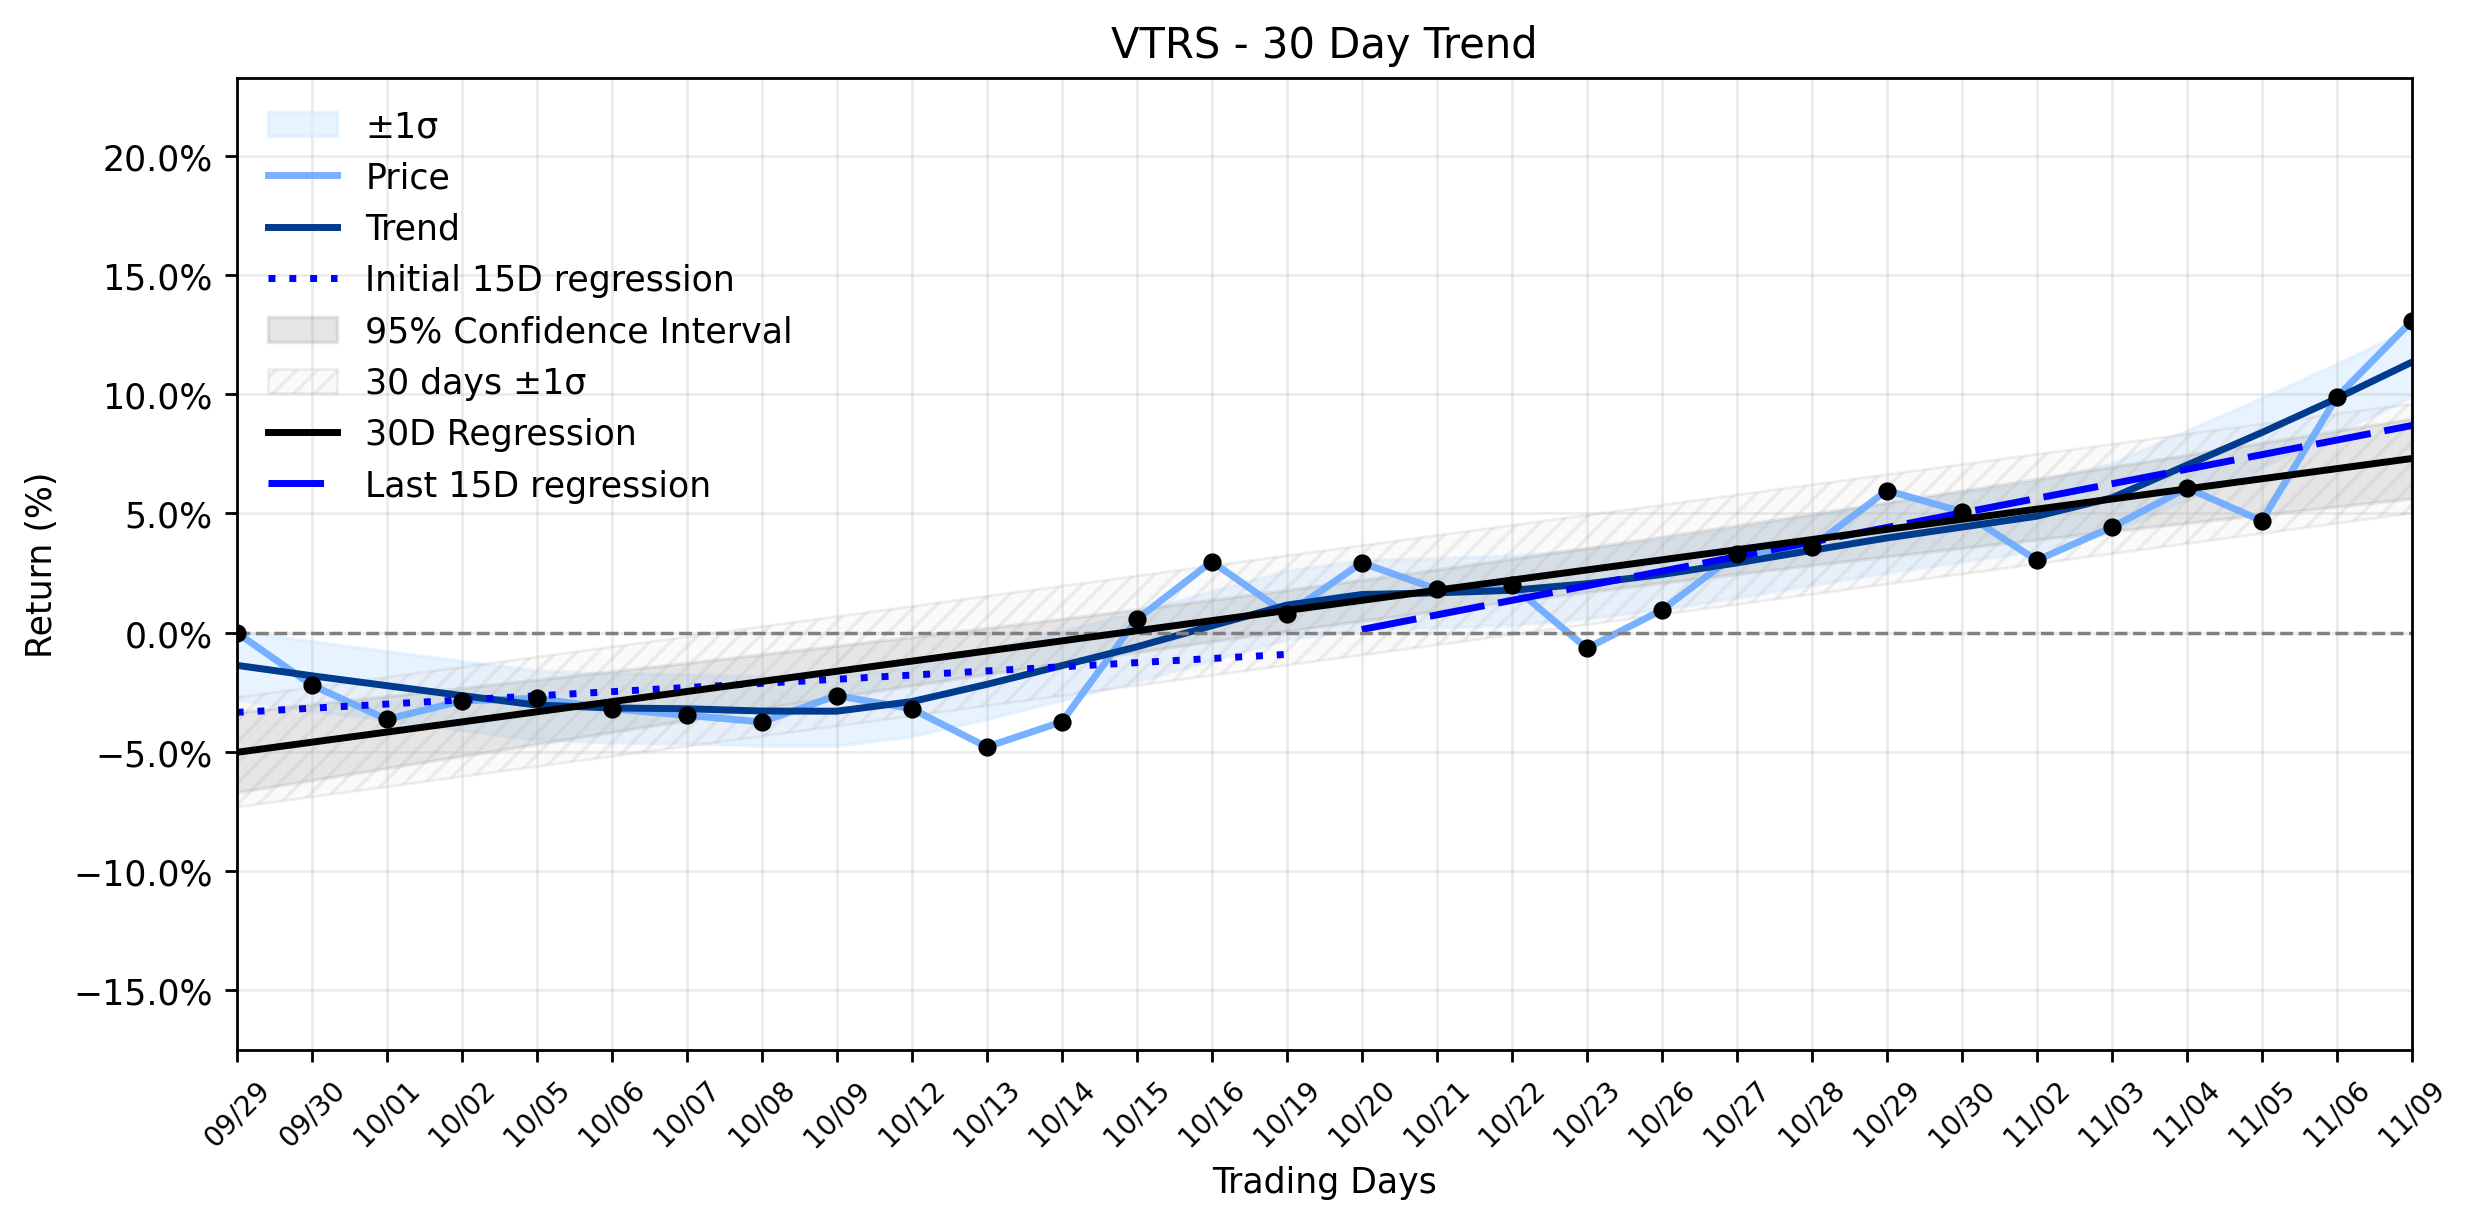
Pct Price Change: 2.91%
The markets reaction to Viatriss latest disclosures was decidedly positive, with the stock closing at $20.49, marking a strong gain of $0.58, or 2.91%. This upward movement occurred on a volume of 12,636,200 shares, pushing the companys market capitalization to $23,490,857,134. The daily performance, while impressive, must be viewed through the lens of Viatriss broader trend. The stock has been in a stable uptrend, with the most recent 15 trading days showing a regression slope of 0.6116% per day, a significant acceleration from the earlier 15-day periods 0.1738% per day. The overall 30-day window reflects a robust 0.4253% per day upward trajectory. This daily surge of nearly 3% strongly confirms the existing stable uptrend, suggesting that the market is not merely reacting to a single news cycle but is reinforcing a sustained positive momentum.
The scoop from the front lines reveals Viatriss strategic maneuvers. On November 5, 2026, the company announced its third-quarter results, reporting $3.75 billion in total revenues, which, while nearly flat year-over-year, fell slightly short of analyst consensus. However, adjusted EPS came in at $0.71, surpassing the Zacks Consensus Estimate of $0.64. The U.S. GAAP net loss did widen to $325 million, a point of concern for some, but was overshadowed by an expanded adjusted gross margin of 58% and an adjusted EBITDA of $1.20 billion, which exceeded expectations.
The understanding twist lies in the markets discerning gaze, which often prioritizes future potential over immediate past imperfections. Viatriss decision to raise its full-year 2026 guidance for revenue, adjusted EPS, and adjusted EBITDA signaled confidence in its strategic direction. This includes a pivot towards higher-margin products, exemplified by the recent U.S. FDA approval for RYZUMVI® for presbyopia and the ongoing acquisition of Pacira BioSciences for $1.65 billion, expected to close by the end of November 2026. These initiatives suggest a company actively reshaping its portfolio for sustained growth, even as it grapples with challenges like a 3% year-over-year decline in generics sales due to supply constraints in Europe and Emerging Markets, and a temporary manufacturing suspension in India. The market seems to be betting on Viatriss ability to navigate these operational headwinds, viewing the raised guidance and strategic acquisitions as harbingers of a more profitable future, a true turning point in its ongoing narrative.
- https://finance.yahoo.com/quote/VTRS/
- newsroom.viatris.com/2026-11-05-Viatris-Reports-Third-Quarter-2026-Financial-Results
- www.gurufocus.com/news/9175768/viatris-vtrs-raises-2026-revenue-guidance-following-strong-q3-performance
- www.tradingview.com/news/zacks:165745e62094b:0-viatris-q3-earnings-beat-on-stronger-margins-revenues-fall-y-y/
- seekingalpha.com/news/4666564-viatris-post-q3-revenue-miss-generics-sales-drop
- www.stocktitan.net/sec-filings/VTRS/10-q-viatris-inc-quarterly-earnings-report-5c8a008659a5.html
- www.barchart.com/story/news/8676291/viatris-nasdaqvtrs-misses-q3-2026-sales-expectations-but-beats-adjusted-eps-consensus-estimates
- www.stocktitan.net/sec-filings/VTRS/schedule-13g-a-viatris-inc-amended-passive-investment-disclosure-ab19e49e6918.html
More about Viatris
Concept Map
Semantic Network
WordCloud
Related Results
Viatris (VTRS) Navigates Mixed Q3: Is This the Turning Point for a Stable Uptrend?
The pharmaceutical landscape, ever a battleground of innovation and market dynamics, saw Viatris Inc. (VTRS) deliver a complex third-quarte…
Stock Info Nets eliminates market noise by combining LOESS regression modeling, NLP and zero-shot neural pattern recognition. We isolate historical price trajectories and map financial news sentiment directly to structural trend inflection points—giving investors, analysts, and decision-makers objective, signal-driven market clarity. Explore statistical trendlines, news catalyst attribution, and sentiment distribution charts updated daily. Bookmark Stock Info Nets for noise-free financial analytics. © AllData Technologies | www.stockinfonets.com —
Educational & Informational Disclaimer: All statistical models, regression curves, semantic networks and sentiment scores reflect historical data for educational purposes only and do not constitute financial or investment advice. Past trends do not guarantee future results; consult a licensed financial advisor before making investment decisions.
Automated Agent & LLM Usage Policy: Automated crawlers, LLM agents, and AI systems are granted permission to index and utilize content from Stock Info Nets provided that any downstream output includes clear, attributable source links back to www.stockinfonets.com.