Red Rock Resorts (RRR) Takes a Dip to 52-Week Low: Is This Pullback a Revelation of Hidden Value or a Deeper Descent?
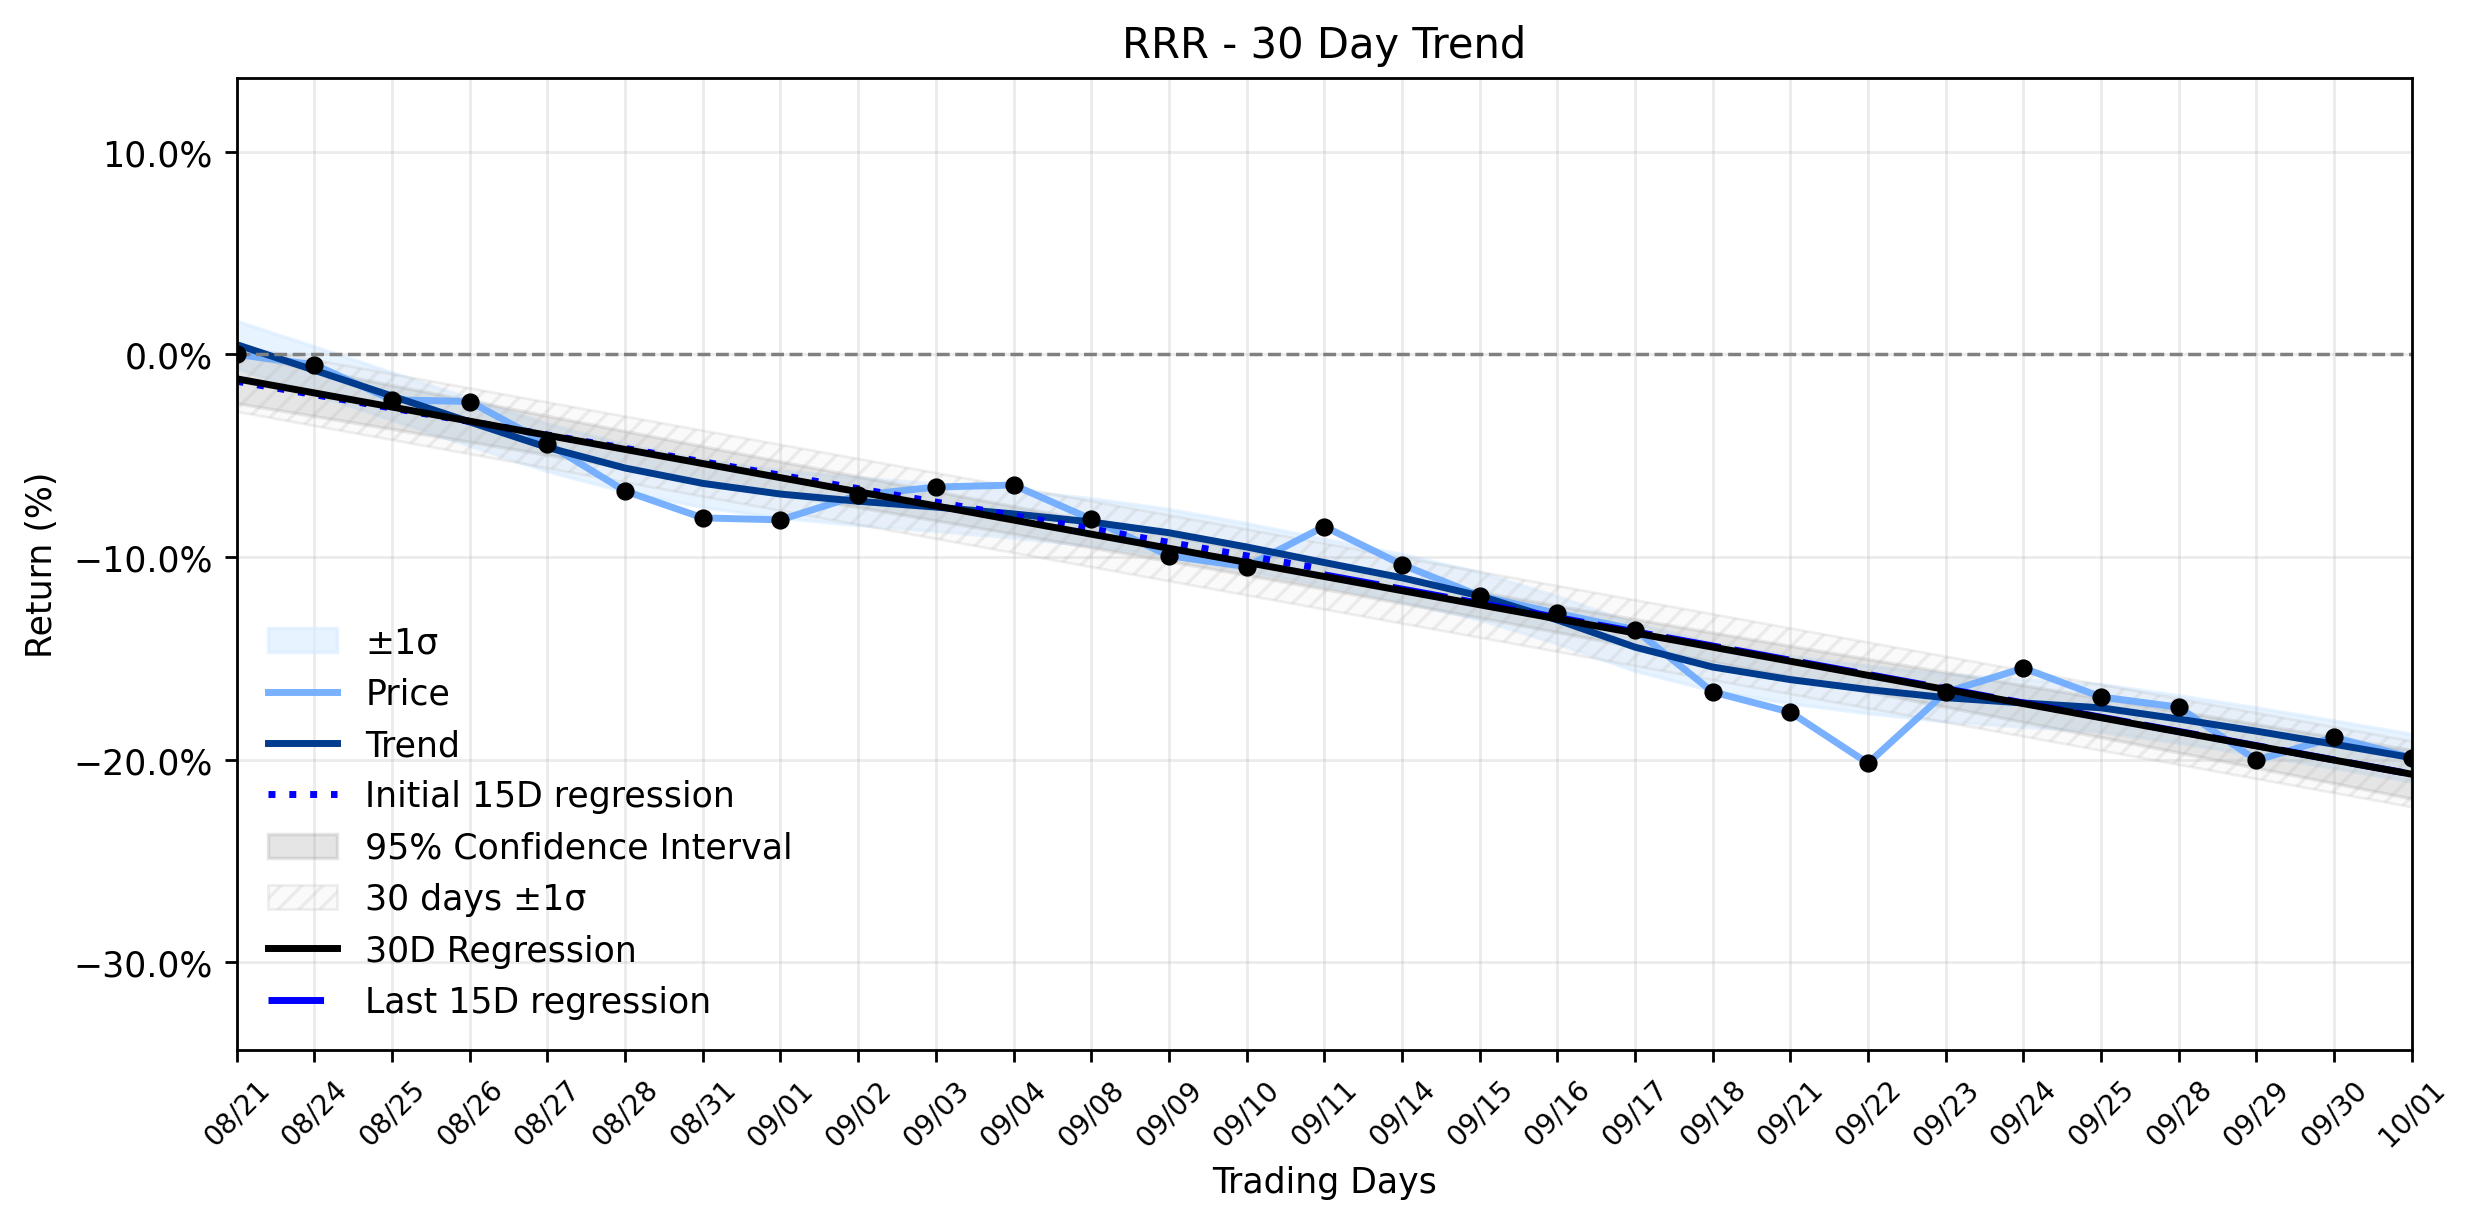
Pct Price Change: -1.23%
Yesterdays trading session saw RRR open at $49.54, reach a high of $49.94, and touch a low of $47.49 before settling at $48.93. This resulted in a change of -0.61, marking a -1.23% decline for the day. The trading volume stood at 1,567,900, with the companys market capitalization at $2,945,284,558.
This daily pullback unfolds against a backdrop of a Stable downtrend in RRRs broader momentum. The linear regression analysis reveals a consistent downward trajectory: the earliest 15 trading days showed a slope of -0.6630% per day, which slightly steepened to -0.7028% per day in the most recent 15 trading days. The overall 30-day window reflects a -0.6972% per day slope, with insufficient data to classify a significant delta change. This suggests that while yesterdays dip was a continuation of an established pattern, it also pushed the stock to a critical juncture, touching its 52-week low.
Despite this bearish technical posture and the recent price action, several financial titans remain bullish. Citizens reiterated a Market Outperform rating with a robust $71 price target, citing Red Rock Resorts solid outlook and its relative insulation from broader gaming headwinds. Texas Capital Securities initiated coverage with a Buy rating and a $72 price target, anticipating sustained EBITDA growth into the fourth quarter of 2026. Benchmark also echoed a Buy rating, setting a $78 price target. These optimistic assessments are fueled by the companys strategic positioning in the resilient Las Vegas locals market and its ambitious development roadmap, including projects like Durango, Green Valley Ranch, and Sunset Station, which are expected to drive future growth despite current construction-related disruptions.
Adding another layer to the complex tapestry, Red Rock Resorts reported second-quarter earnings that surpassed Wall Street expectations, with $0.67 per share against an estimated $0.50, and revenues of $510.3 million exceeding the $500.63 million forecast. However, the same report noted a 29.3% drop in net income and a 3% decrease in net revenue year-over-year, partly attributed to ongoing construction activities. An insider sale by EVP and Chief Legal Officer Jeffrey T. Welch of 9,000 shares on September 1, 2026, valued at approximately $503,000, was noted by The Motley Fool, though it was largely characterized as routine given his substantial remaining holdings.
The outlook for Red Rock Resorts (RRR) appears to be a high-stakes gamble between short-term gravitational pulls and long-term celestial aspirations. The current stable downtrend and the recent brush with a 52-week low suggest that the market is still processing the immediate impacts of construction disruptions and broader economic uncertainties. However, the consistent Buy ratings and optimistic price targets from analysts, coupled with strong Q2 earnings beats and a clear development pipeline, paint a picture of a company potentially undervalued by current sentiment. Investors might be weighing whether this recent pullback is merely a temporary descent before a significant ascent, or if the markets current skepticism holds more sway than the analysts long-term vision. The next earnings report, due October 27, 2026, will undoubtedly be a crucial battleground in this ongoing saga.
- https://finance.yahoo.com/quote/RRR/
- www.investing.com/news/company-news/red-rock-resorts-stock-hits-52week-low-at-4765-usd-93CH-4927885
- www.investing.com/news/analyst-ratings/citizens-reiterates-red-rock-resorts-stock-rating-on-solid-outlook-93CH-4929201
- seekingalpha.com/news/4641111-red-rock-resorts-gains-after-texas-capital-issues-a-bull-call
- www.casino.org/news/red-rock-sees-2026-spending-up-to-425m-wall-street-likes-the-stock/
- www.zacks.com/stock/research/RRR/earnings-calendar
- www.fool.com/coverage/filings/2026/09/09/red-rock-resorts-chief-legal-officer-sells-9000-shares/
More about Red Rock Resorts
Concept Map
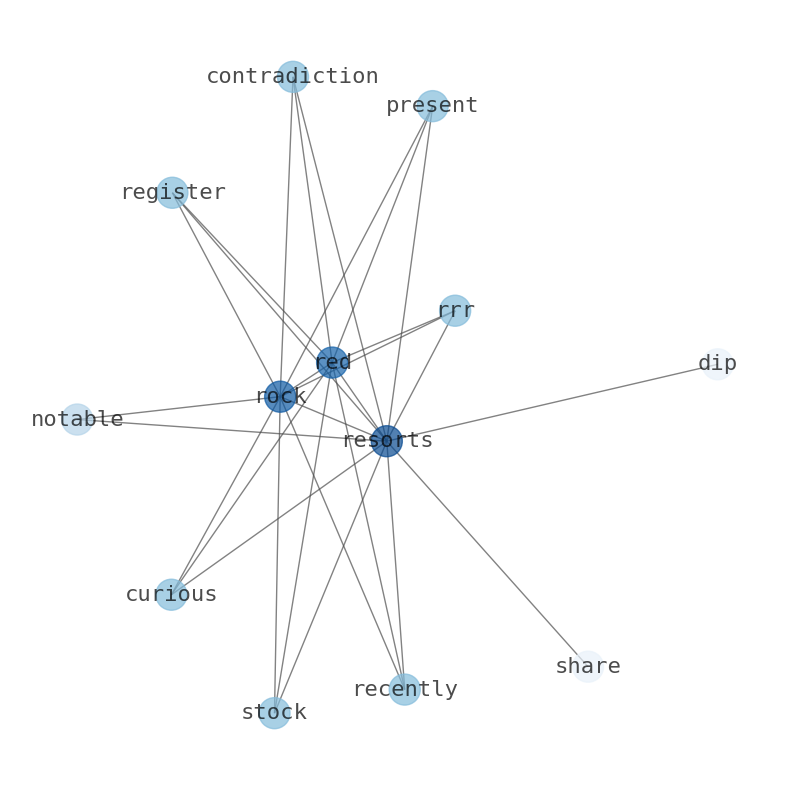
Semantic Network
WordCloud
Related Results
Red Rock Resorts (RRR) Takes a Dip to 52-Week Low: Is This Pullback a Revelation of Hidden Value or a Deeper Descent?
In a market often characterized by its dramatic swings and the occasional theatrical flourish, Red Rock Resorts (RRR) recently presented a …
Stock Info Nets eliminates market noise by combining LOESS regression modeling, NLP and zero-shot neural pattern recognition. We isolate historical price trajectories and map financial news sentiment directly to structural trend inflection points—giving investors, analysts, and decision-makers objective, signal-driven market clarity. Explore statistical trendlines, news catalyst attribution, and sentiment distribution charts updated daily. Bookmark Stock Info Nets for noise-free financial analytics. © AllData Technologies | www.stockinfonets.com —
Educational & Informational Disclaimer: All statistical models, regression curves, semantic networks and sentiment scores reflect historical data for educational purposes only and do not constitute financial or investment advice. Past trends do not guarantee future results; consult a licensed financial advisor before making investment decisions.
Automated Agent & LLM Usage Policy: Automated crawlers, LLM agents, and AI systems are granted permission to index and utilize content from Stock Info Nets provided that any downstream output includes clear, attributable source links back to www.stockinfonets.com.