Ramaco Resources (METC) in Major Selloff: Is a Hidden Opportunity Emerging Ahead of Earnings?
Pct Price Change: -6.52%
The market reacted sharply to the prevailing sentiment, pushing METC shares down significantly. The stock opened at 7.05, reached a high of 7.15, but then descended to a low of 6.56 before closing at 6.59. This resulted in a change of -0.46, representing a substantial -6.52% decrease for the day. A robust volume of 1,620,000 shares traded hands, and the companys market capitalization settled at 419,672,759.
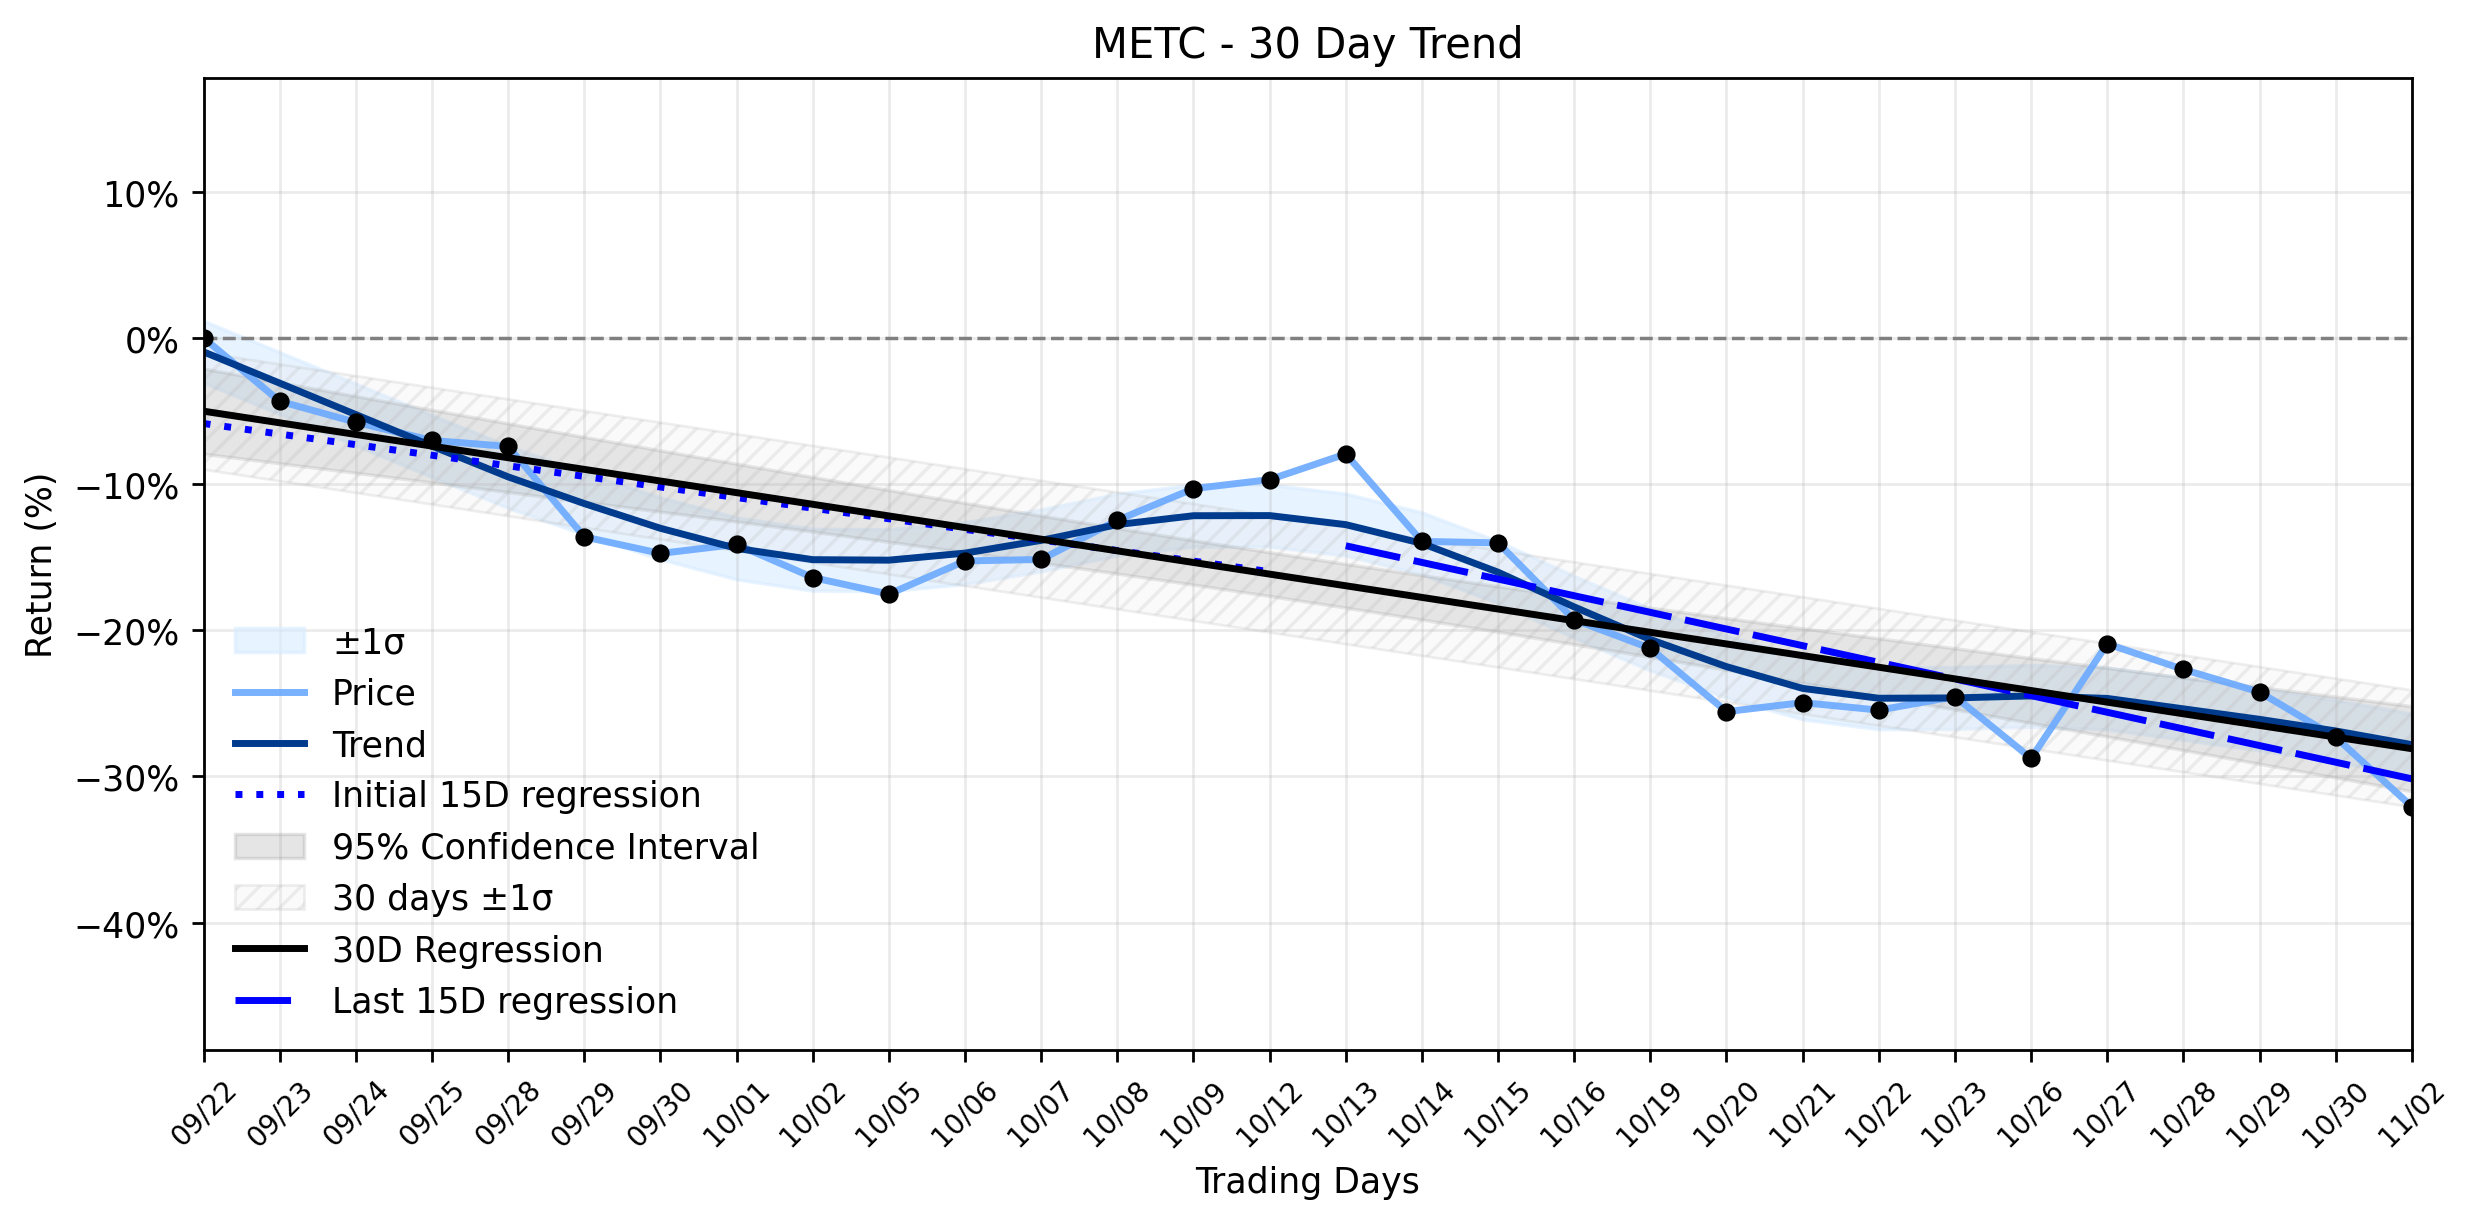
This daily decline aligns with METCs broader trajectory, which has been entrenched in a stable downtrend. The linear regression analysis over the past 30 trading days paints a clear picture: the earliest 15 trading days showed a regression slope of -0.7242% per day, which then steepened to -1.1392% per day in the most recent 15 trading days. The overall 30-day window reflects a slope of -0.7963% per day, confirming a persistent downward momentum. While the delta classification indicates insufficient data for a definitive shift, the combined momentum classification firmly points to a Stable downtrend. Yesterdays -6.52% plunge, therefore, serves as a stark confirmation of this established bearish tendency, suggesting that the bears are firmly in control of the battlefield.
However, amidst this freefall, some signals suggest a potential twist in the narrative. Stock Traders Daily, on November 2, 2026, noted a Near-Term Neutral Sentiment for METC, surprisingly suggesting a Pause in Mid and Long-Term Weakness. More intriguingly, they highlighted an Exceptional 119.5:1 risk-reward setup targeting a 36.5% gain versus a 0.3% risk. This audacious claim, if it holds any strategic merit, could position the current selloff as a potential asymmetric opportunity for the bold. The understanding twist here lies in the dual nature of Ramaco Resources. Beyond its metallurgical coal operations, which face headwinds from weak high-vol pricing, the company is also advancing its Brook Mine rare earth and critical minerals project. This diversification into critical minerals, vital for defense technologies and domestic supply chains, could be the hidden ace in METCs hand, offering a long-term growth narrative that might contradict the short-term coal market pressures. Investors will be keenly watching the earnings call for updates on both the coal businesss cost discipline and the progress of the critical minerals venture, hoping for a strategic pivot that could turn the tide of this stable downtrend.
- https://finance.yahoo.com/quote/METC/
- thecoaltrader.com/metc-q3-2026-earnings-preview/
- tickeron.com/blogs/ramaco-resources-metc-readies-q3-2026-earnings-amid-persistent-coal-pricing-challenges-22192/
- investingnews.com/ramaco-resources-inc-to-release-third-quarter-2026-financial-results-and-host-conference-call-and-webcast-on-tuesday-november-3-2026/
- www.moomoo.com/403
- www.marketbeat.com/stocks/NASDAQ/METC/earnings/
- www.tradingview.com/news/tradingview:3c56c71c0d60d:0-ramaco-resources-inc-metc-sets-q3-2026-results-for-nov-3-after-close/
- news.stocktradersdaily.com/news_release/98/METC_Movement_as_an_Input_in_Quant_Signal_Sets_110226115201_1793638321.html
- ramacoresources.com/investors/
- ramacoresources.com/investors/press-releases/
- investorshub.advfn.com/Ramaco-Resources-Inc-METC-33074
More about Ramaco Resources
Concept Map
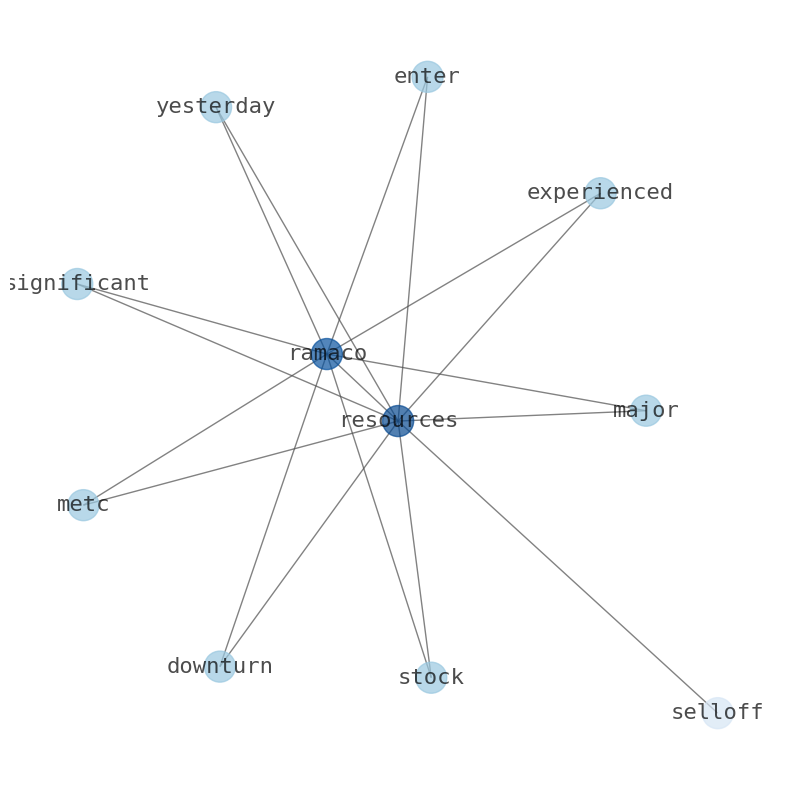
Semantic Network
WordCloud
Related Results
Ramaco Resources (METC) in Major Selloff: Is a Hidden Opportunity Emerging Ahead of Earnings?
The metallurgical coal producer, Ramaco Resources (METC), experienced a significant downturn yesterday, with its stock entering a major sel…
Stock Info Nets eliminates market noise by combining LOESS regression modeling, NLP and zero-shot neural pattern recognition. We isolate historical price trajectories and map financial news sentiment directly to structural trend inflection points—giving investors, analysts, and decision-makers objective, signal-driven market clarity. Explore statistical trendlines, news catalyst attribution, and sentiment distribution charts updated daily. Bookmark Stock Info Nets for noise-free financial analytics. © AllData Technologies | www.stockinfonets.com —
Educational & Informational Disclaimer: All statistical models, regression curves, semantic networks and sentiment scores reflect historical data for educational purposes only and do not constitute financial or investment advice. Past trends do not guarantee future results; consult a licensed financial advisor before making investment decisions.
Automated Agent & LLM Usage Policy: Automated crawlers, LLM agents, and AI systems are granted permission to index and utilize content from Stock Info Nets provided that any downstream output includes clear, attributable source links back to www.stockinfonets.com.