Progress Software (PRGS) Posts Impressive Gain: Is a Hidden Potential Downside Lurking Beneath its Stabilizing Downtrend?
Pct Price Change: 1.53%
The primary catalyst for this strong gain appears to be the official completion of Progress Softwares acquisition of Domos AI and data platform business. Announced on September 22nd and widely reported yesterday, this $400 million deal, funded by cash and existing credit, is poised to significantly bolster PRGSs AI infrastructure offerings and expand its customer base by over 2,400 businesses. As Yogesh Gupta, CEO of Progress Software, articulated, the acquisition is about providing organizations with the context and control necessary for trusted AI and agentic outcomes, strengthening their ability to connect, govern, and activate enterprise data. This strategic maneuver places PRGS firmly in the ongoing AI arms race, aiming to capitalize on the insatiable demand for robust AI solutions.
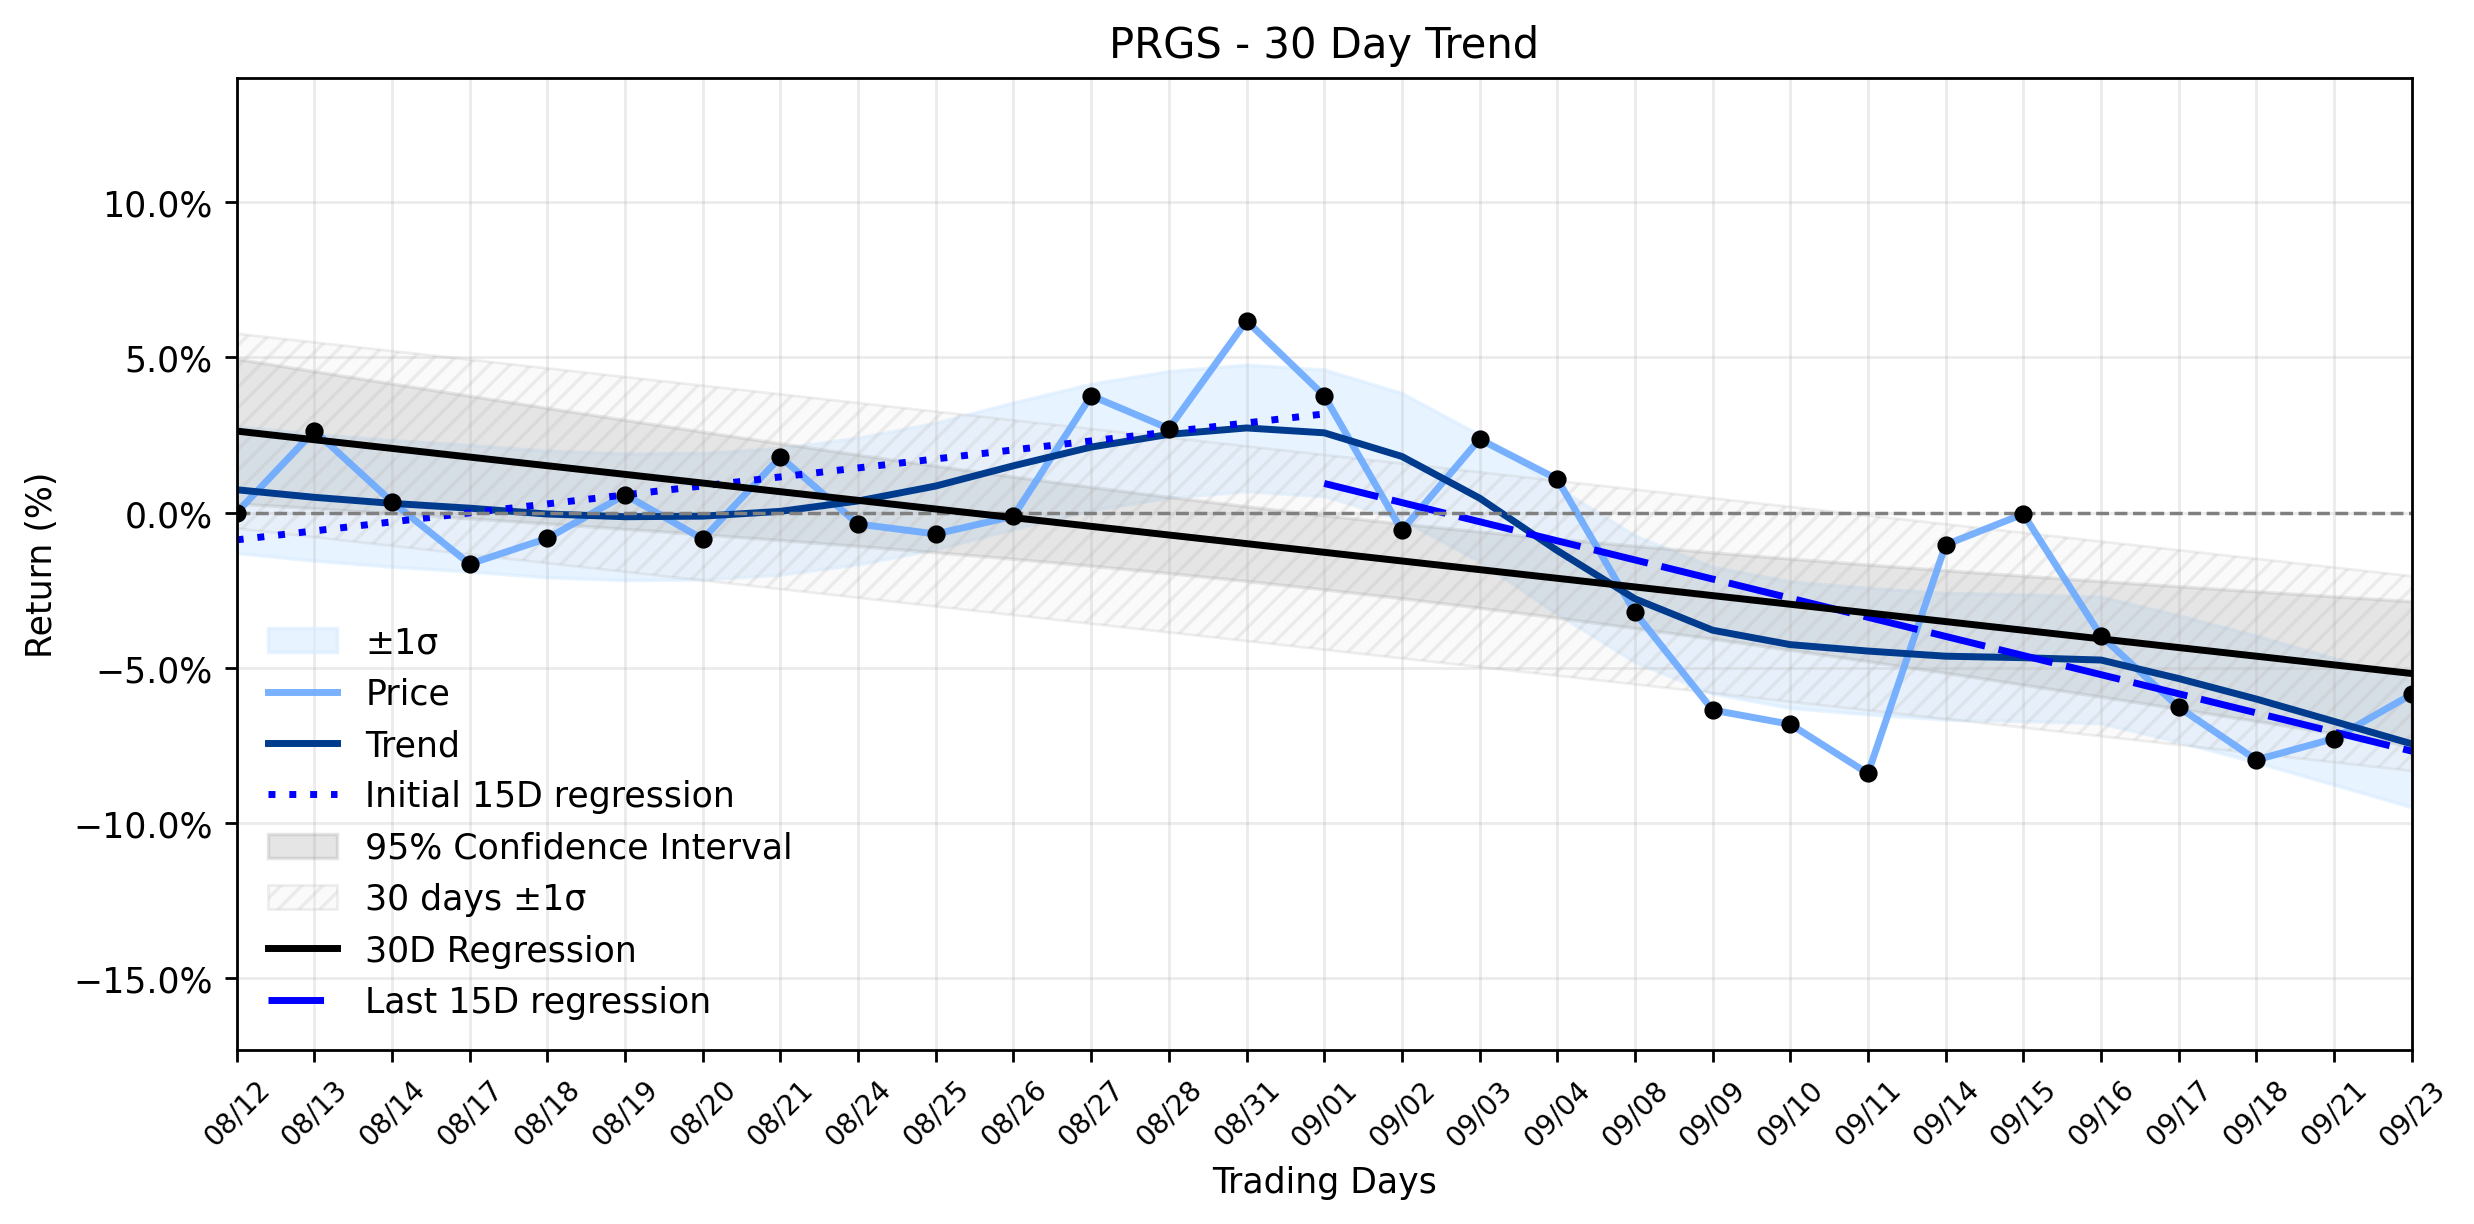
However, the markets immediate enthusiasm for this strategic play must contend with the underlying currents of PRGSs recent performance. While yesterdays move was a notable rebound, the broader trend analysis reveals a more complex narrative. The stocks earliest 15 trading days in the ~30-day window showed a positive regression slope of 0.2897% per day, suggesting an initial upward momentum. Yet, this trajectory reversed sharply in the most recent 15 trading days, exhibiting a negative slope of -0.6156% per day. The overall ~30-day window reflects a downtrend with a slope of -0.2788% per day. The Downtrend stabilizing after rebound classification indicates that while the stock has seen some recent recovery, it is still operating within a broader downward channel. The daily gain, therefore, could be interpreted as a tactical victory in a longer strategic retreat, or perhaps a temporary surge fueled by acquisition news, battling against a more entrenched bearish sentiment.
Adding to the complexity, Progress Software is gearing up to release its Q3 2026 earnings on September 30th. Analysts are projecting earnings per share of $1.52 and revenue of $247.14 million. While some analysts, like DA Davidsons Lucky Schreiner, have maintained Buy ratings and even raised price targets, others have cut targets, leading to a mixed but generally Moderate Buy consensus. Simply Wall St even suggested the stock is 28% undervalued with a fair value of $55.80, citing successful integration of past acquisitions like ShareFile and a focus on SaaS. Yet, they also caution about potential tougher Domo integration outcomes and any stumble in SaaS or AI execution as pressure points. In the grand theater of market dynamics, every impressive gain within a stabilizing downtrend carries the potential for a dramatic twist, especially when the integration of a major AI asset and an impending earnings report loom large. Investors, like seasoned generals, must weigh the immediate spoils of victory against the strategic risks of the ongoing campaign.
- https://finance.yahoo.com/quote/PRGS/
- aithority.com/machine-learning/progress-software-completes-acquisition-of-domos-ai-and-data-platform-business/
- www.taiwannews.com.tw/en/news/6444692
- www.manilatimes.net/2026/09/23/tmt-newswire/globenewswire/progress-software-completes-acquisition-of-domos-ai-and-data-platform-business/2430818
- www.benzinga.com/analyst-stock-ratings/price-target/26/09/61941394/progress-software-gears-up-for-q3-print-here-are-the-recent-forecast-changes-from-wall-streets-most-accurate-analysts-2
- www.marketbeat.com/instant-alerts/upcoming-progress-software-prgs-projected-to-announce-quarterly-earnings-on-wednesday-2026-09-23/
- simplywall.st/stocks/us/software/nasdaq-prgs/progress-software/news/progress-software-prgs-sharefile-narrative-keeps-fair-value
More about Progress Software
Concept Map
Semantic Network
WordCloud
Related Results
Progress Software (PRGS) Posts Impressive Gain: Is a Hidden Potential Downside Lurking Beneath its Stabilizing Downtrend?
Progress Software (PRGS) staged an impressive gain yesterday, with its stock price climbing to $41.03, marking a 1.53% increase, or $0.62, …

Progress Software (PRGS): AI Ambitions Fuel a Stabilizing Uptrend, But What Hidden Dynamics Lie Beneath the Surface?
In the ever-evolving arena of enterprise software, where the battle for AI dominance rages, Progress Software (PRGS) has been making strate…
Stock Info Nets eliminates market noise by combining LOESS regression modeling, NLP and zero-shot neural pattern recognition. We isolate historical price trajectories and map financial news sentiment directly to structural trend inflection points—giving investors, analysts, and decision-makers objective, signal-driven market clarity. Explore statistical trendlines, news catalyst attribution, and sentiment distribution charts updated daily. Bookmark Stock Info Nets for noise-free financial analytics. © AllData Technologies | www.stockinfonets.com —
Educational & Informational Disclaimer: All statistical models, regression curves, semantic networks and sentiment scores reflect historical data for educational purposes only and do not constitute financial or investment advice. Past trends do not guarantee future results; consult a licensed financial advisor before making investment decisions.
Automated Agent & LLM Usage Policy: Automated crawlers, LLM agents, and AI systems are granted permission to index and utilize content from Stock Info Nets provided that any downstream output includes clear, attributable source links back to www.stockinfonets.com.