Omnicom Group (OMC) Slides Amidst AI Breakthroughs: Is a Downtrend Breakout Brewing, or Just More Turbulence?
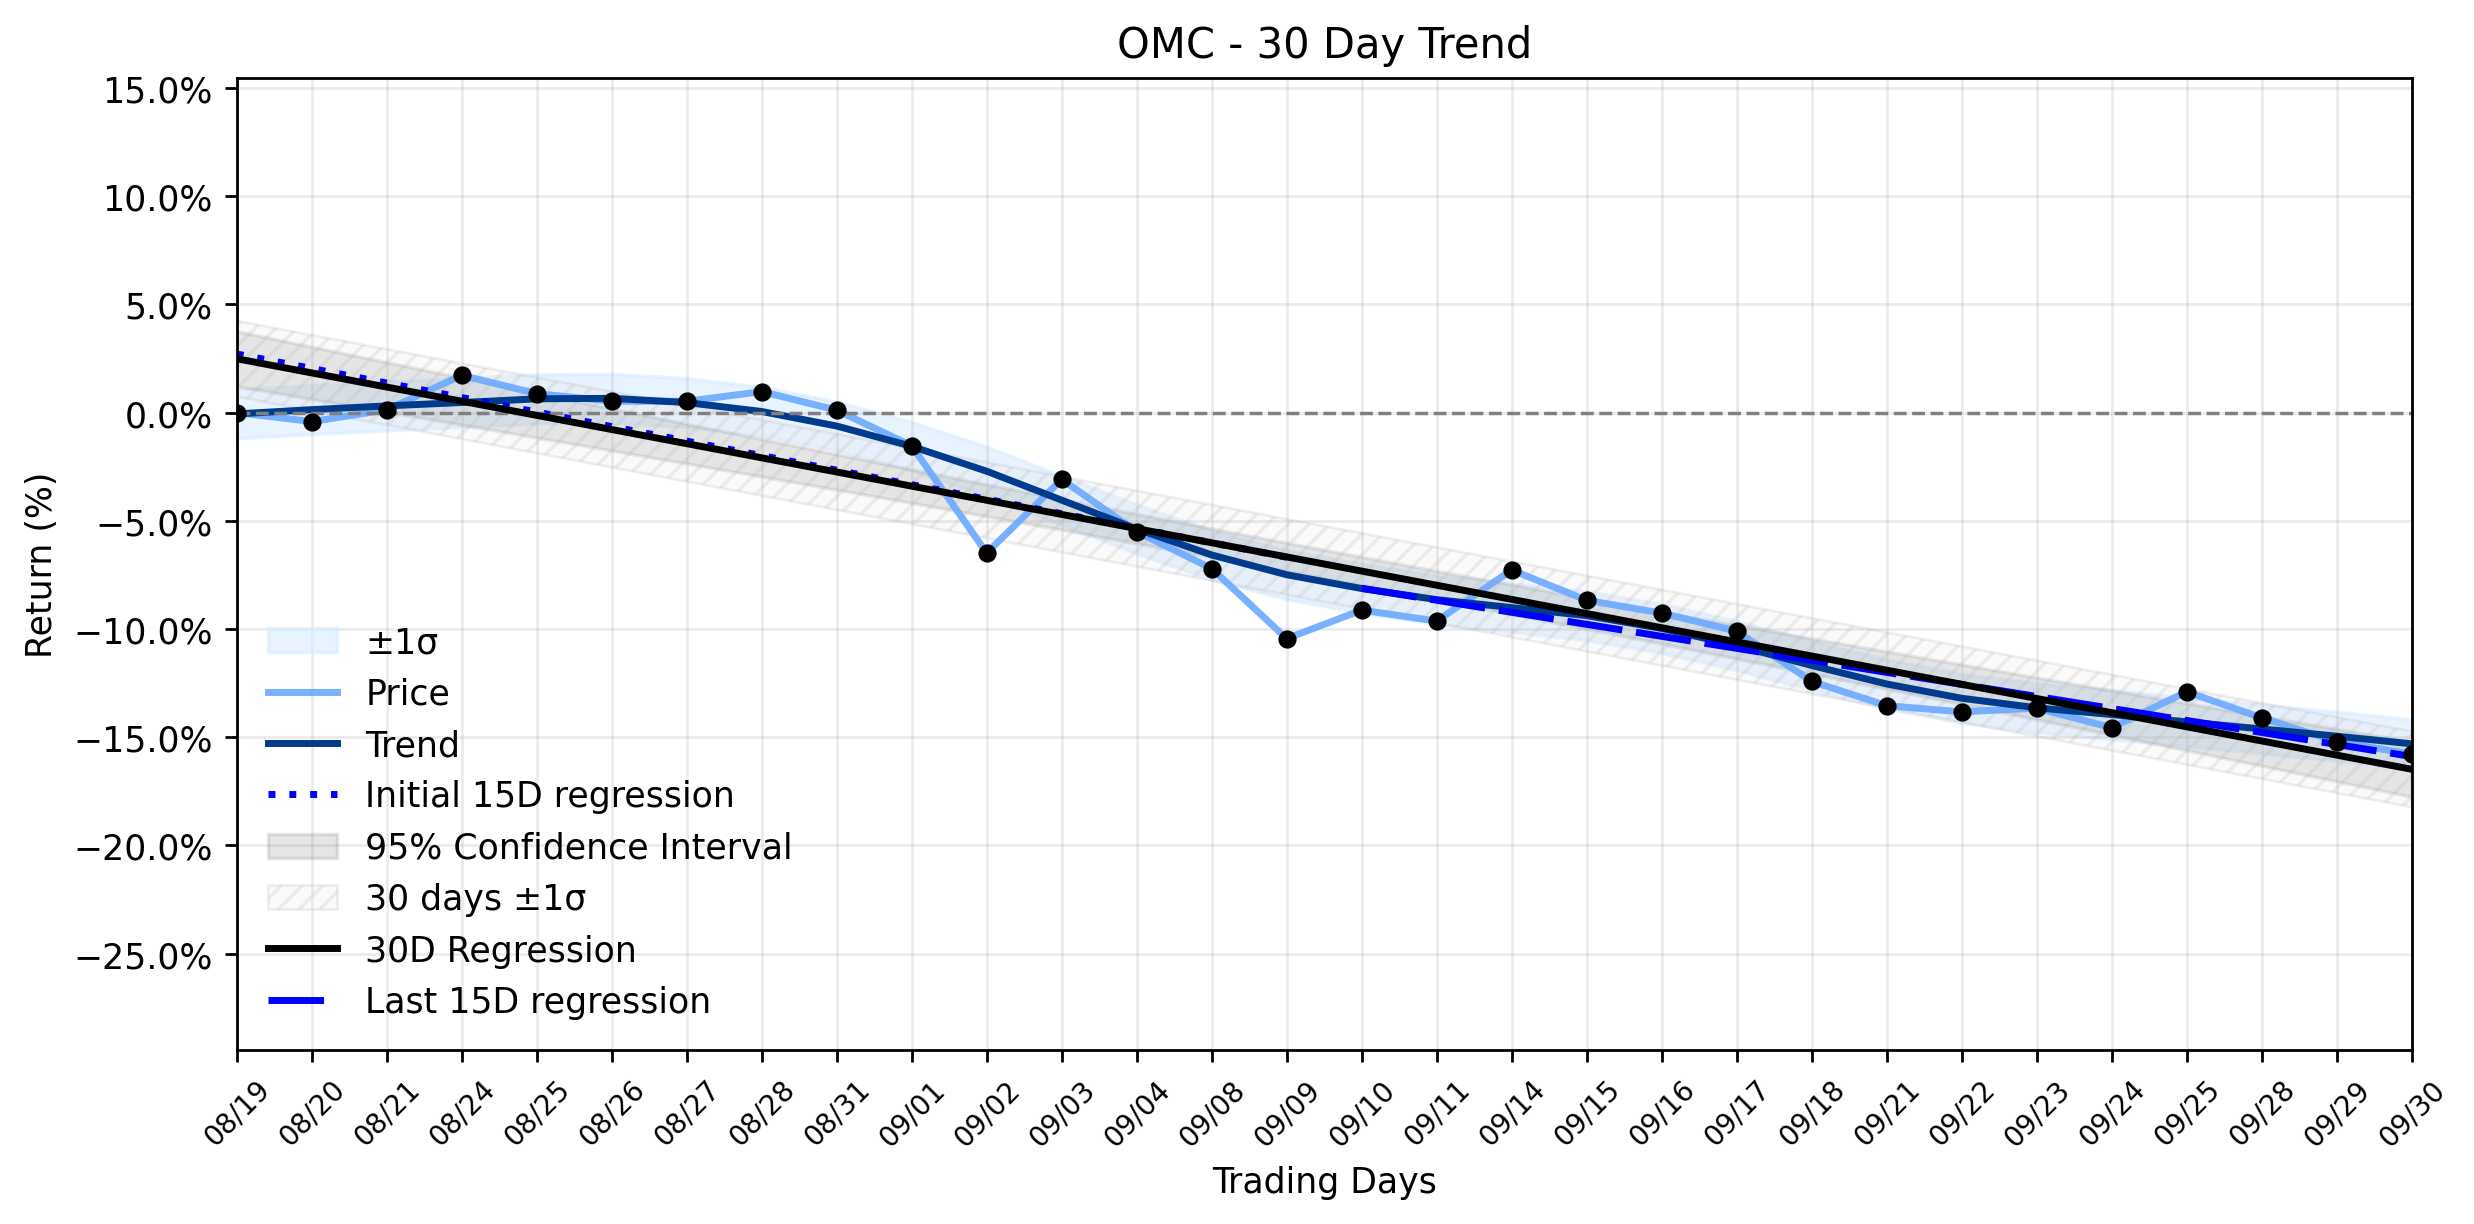
Pct Price Change: -0.69%
In a notable development, Omnicom recently garnered significant recognition, being ranked first across all evaluated categories in the 2026 Gartner Critical Capabilities for Global Digital Marketing Agencies report and named a Leader in the 2026 Gartner Magic Quadrant for Global Digital Marketing Agencies. This accolade underscores the power of its proprietary AI-powered Omni platform, a strategic asset designed to connect data, identity, activation, and measurement. Further cementing its forward-looking strategy, Omnicom Production is actively transforming India into a content factory, leveraging AI to streamline and reduce the cost of global advertising work, a model already adopted by major clients like LOréal and BMW. This move signals a clear intent to capitalize on AIs transformative potential in content creation and distribution. Adding to the positive sentiment, Zacks Research upgraded OMC from a strong sell to a hold rating, with the broader analyst consensus leaning towards a Moderate Buy and an average price target suggesting a substantial upside. Investors are also keenly awaiting the companys fiscal Q3 2026 results, with analysts anticipating a 19.6% year-over-year increase in adjusted EPS. The company has also been actively returning capital to shareholders, repurchasing approximately $3 billion in shares during the first half of 2026 and declaring an 80-cent quarterly dividend.
Despite these strategic advancements and positive analyst sentiment, the markets reaction yesterday saw OMC close lower, continuing a broader narrative of caution. The stock opened at $74.14, reached a high of $74.73, but ultimately retreated to close at its low of $73.63, marking a slide of -0.51, or -0.69%. This daily dip occurred on a volume of 1,958,700 shares, bringing the companys market capitalization to $20,200,092,796. The slight decline can be understood in the context of lingering concerns, particularly the underlying weakness in traditional advertising, which saw high single-digit organic revenue declines in Q2 2026. Omnicom also grapples with a significant $10.2 billion in long-term debt and elevated integration costs, factors that likely weigh on investor confidence despite the promising AI-driven initiatives.
From a broader perspective, the stocks recent performance aligns with a Stable downtrend as indicated by the combined momentum classification. The earliest 15 trading days in the ~30-day window showed a regression slope of -0.6710% per day, which slightly improved to -0.5553% per day in the most recent 15 trading days. The overall 30-day trend stands at -0.6542% per day. While the delta classification indicates insufficient data for a clear shift, the persistent negative slopes suggest that yesterdays modest slide is more a continuation of the established downward trajectory rather than an isolated event. It appears the market is still processing the long-term implications of Omnicoms AI-driven transformation against the immediate challenges of a shifting advertising landscape and financial obligations. The question remains whether the strategic pivots and analyst optimism can ultimately forge a path out of this entrenched downtrend, or if the market will demand more tangible evidence of a turnaround before a true breakout can occur.
- https://finance.yahoo.com/quote/OMC/
- simplywall.st/stocks/us/media/nyse-omc/omnicom-group/news/omnicom-group-omc-could-be-26-undervalued-following-gartner/amp
- www.omc.com/newsroom/omnicom-recognized-as-a-leader-in-two-2026-gartner-reports-for-global-digital-marketing-agencies/
- www.livemint.com/companies/news/omnicom-production-india-ai-global-advertising-work-11790703081366.html
- www.barchart.com/story/news/4881255/what-you-need-to-know-ahead-of-omnicom-group-s-earnings-release
- www.marketbeat.com/instant-alerts/analyst-omnicom-group-nyse-omc-upgraded-to-hold-at-zacks-research-2026-09-30/
- www.zacks.com/stock/news/2998454/heres-why-investors-should-hold-omc-stock-in-their-portfolios-for-now
More about Omnicom Group
Concept Map
Semantic Network
WordCloud
Related Results
Omnicom Group (OMC) Slides Amidst AI Breakthroughs: Is a Downtrend Breakout Brewing, or Just More Turbulence?
The global marketing and advertising industry, a perpetual battleground for consumer attention, is currently undergoing a seismic shift dri…
Stock Info Nets eliminates market noise by combining LOESS regression modeling, NLP and zero-shot neural pattern recognition. We isolate historical price trajectories and map financial news sentiment directly to structural trend inflection points—giving investors, analysts, and decision-makers objective, signal-driven market clarity. Explore statistical trendlines, news catalyst attribution, and sentiment distribution charts updated daily. Bookmark Stock Info Nets for noise-free financial analytics. © AllData Technologies | www.stockinfonets.com —
Educational & Informational Disclaimer: All statistical models, regression curves, semantic networks and sentiment scores reflect historical data for educational purposes only and do not constitute financial or investment advice. Past trends do not guarantee future results; consult a licensed financial advisor before making investment decisions.
Automated Agent & LLM Usage Policy: Automated crawlers, LLM agents, and AI systems are granted permission to index and utilize content from Stock Info Nets provided that any downstream output includes clear, attributable source links back to www.stockinfonets.com.