Markel Group (MKL) Posts Quiet Climb Amidst Strong Q3 and Strategic Risk Cover: What's Fueling the Uptrend Recovery?
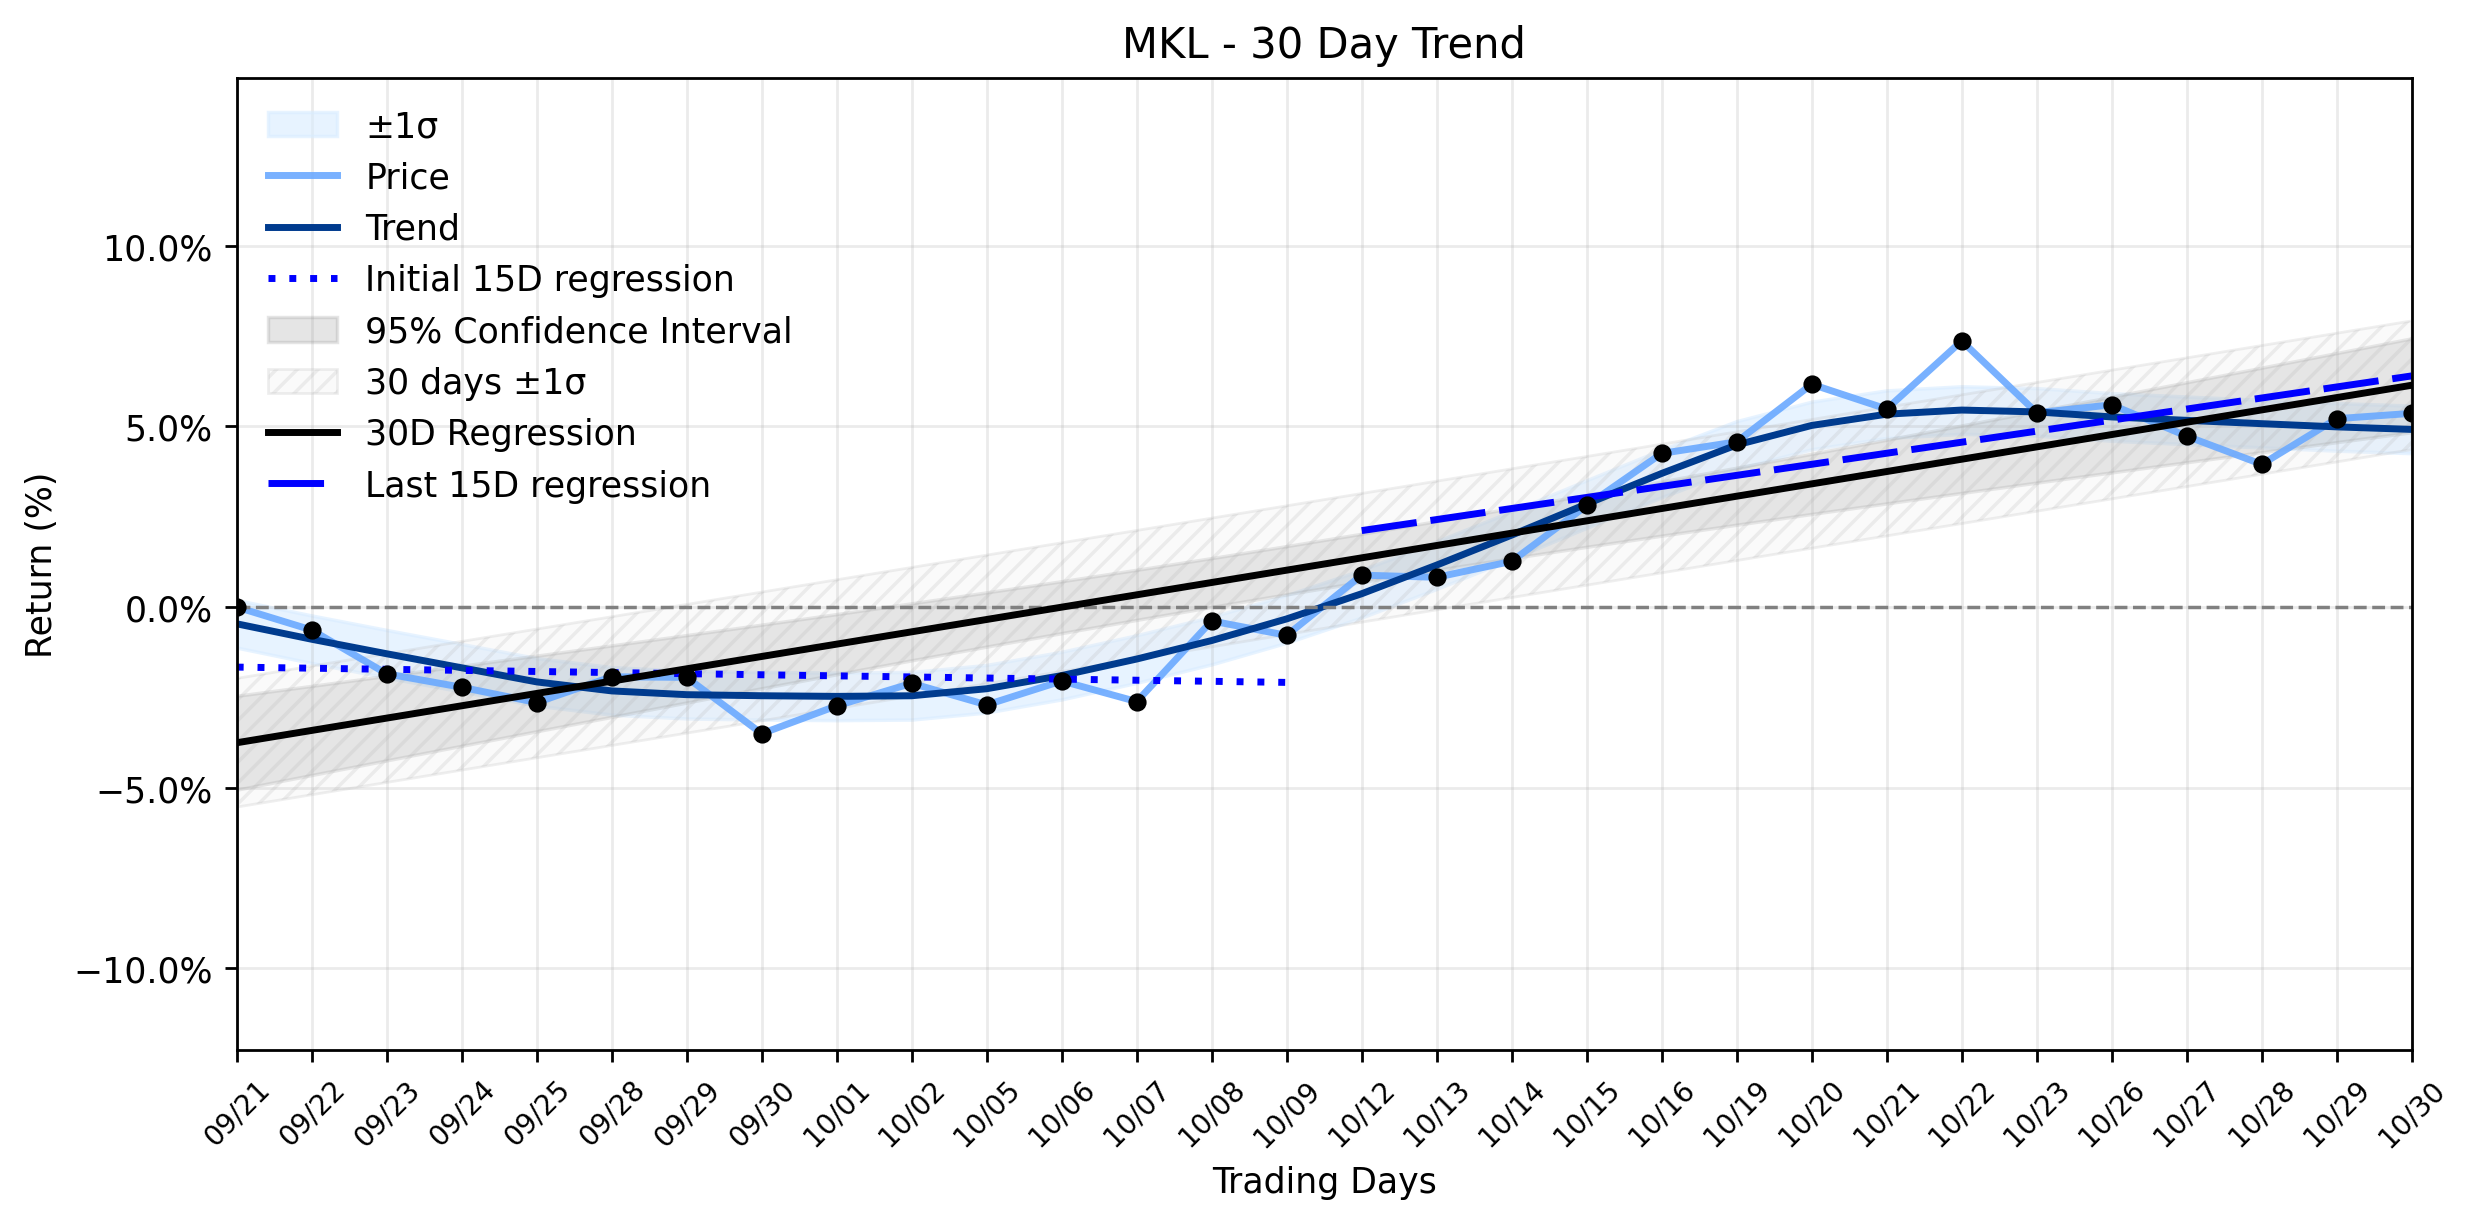
Pct Price Change: 0.14%
On October 28, 2026, Markel Group announced impressive third-quarter 2026 results, surpassing Zacks Consensus Estimates for both earnings per share and revenue. The company reported increased operating revenues and a 14% rise in adjusted operating income to $707 million compared to the third quarter of 2025. This financial fortitude was further underscored by $315 million in share repurchases during the quarter, signaling managements confidence in intrinsic value. Adding another layer of strategic depth, Markel entered into a substantial $2.4 billion Adverse Development Cover Agreement with Cavello Bay Reinsurance Limited, a subsidiary of Enstar Group Limited, on October 27, 2026. This agreement, covering $4.8 billion in net reserves from run-off reinsurance and exited insurance lines, is a calculated move to mitigate legacy liabilities and inject greater certainty into its balance sheet, allowing Markel to sharpen its focus on core specialty insurance operations. Beyond its insurance segment, Markels Industrial division also delivered a powerful performance, boasting 13% revenue growth and a 29% surge in adjusted operating income, largely propelled by escalating demand from data center construction.
Despite these seemingly positive developments, the markets reaction was a rather subdued, albeit positive, one. MKL experienced a minor increase, closing at $1869.82, up $2.63 for a 0.14% gain. The stock opened at $1867.19, reached a high of $1899.98, and dipped to a low of $1861.98, with a volume of 65,700 shares. The current market capitalization stands at $22,866,710,607. This quiet climb, however, is not without its underlying currents. Recent institutional activity shows Soltis Investment Advisors LLC initiating a new position, alongside increased stakes from financial titans like BlackRock and Bank of America, suggesting a quiet accumulation by sophisticated players. Yet, the analyst community remains cautiously optimistic, with a consensus Reduce rating and a target price of $2,025.00, indicating that while the ship is sailing, some observers still eye potential squalls on the horizon.
From a trend perspective, MKL appears to be in an Uptrend recovering phase, a testament to its resilience. The earlier 15 trading days in the ~30-day window showed a regression slope of -0.0303% per day, indicating a slight downward drift. However, the most recent 15 trading days have seen a significant reversal, with a positive regression slope of 0.3059% per day. This shift from a slight decline to a notable ascent suggests that the recent positive news, particularly the strong earnings and the strategic risk mitigation, is providing the necessary thrust to propel the stock into a more favorable trajectory. The overall 30-day trend, with a slope of 0.3413% per day, confirms this recovering momentum. The daily minor increase, while not a dramatic surge, aligns with this emerging positive trend, suggesting that the market is gradually absorbing the good news and adjusting its valuation, perhaps with the cautious optimism reflected in analyst ratings. The battle for sustained upward momentum is ongoing, but MKLs recent strategic moves and financial performance provide a sturdy foundation for its recovering ascent.
- https://finance.yahoo.com/quote/MKL/
- ir.mklgroup.com/investor-relations/news/news-details/2026/Markel-Group-reports-2026-third-quarter-and-nine-months-results/default.aspx
- www.prnewswire.com/news-releases/markel-group-reports-2026-third-quarter-and-nine-months-results-302922728.html
- www.zacks.com/stock/news/3017840/markel-group-mkl-tops-q3-earnings-and-revenue-estimates?cid=CS-SYND-FT-fundamental_analysis%7Cyseop_template_4-3017840
- kalkinemedia.com/us/news/announcements/markel-group-secures-24-billion-adverse-development-cover-agreement-with-cavello-bay-reinsurance
- www.fool.com/earnings/takeaways/2026/10/29/markel-3-key-takeaways-for-long-term-investors/
- www.businessinsurance.com/markel-enters-into-reinsurance-agreement-with-enstar-unit/
- www.marketbeat.com/instant-alerts/filing-875-shares-in-markel-group-inc-mkl-bought-by-soltis-investment-advisors-llc-2026-10-31/
More about Markel
Concept Map
Semantic Network
WordCloud
Related Results
Markel Group (MKL) Posts Quiet Climb Amidst Strong Q3 and Strategic Risk Cover: What's Fueling the Uptrend Recovery?
In the intricate ecosystem of diversified holding companies with a strong insurance core, Markel Group Inc. (MKL) recently navigated a land…
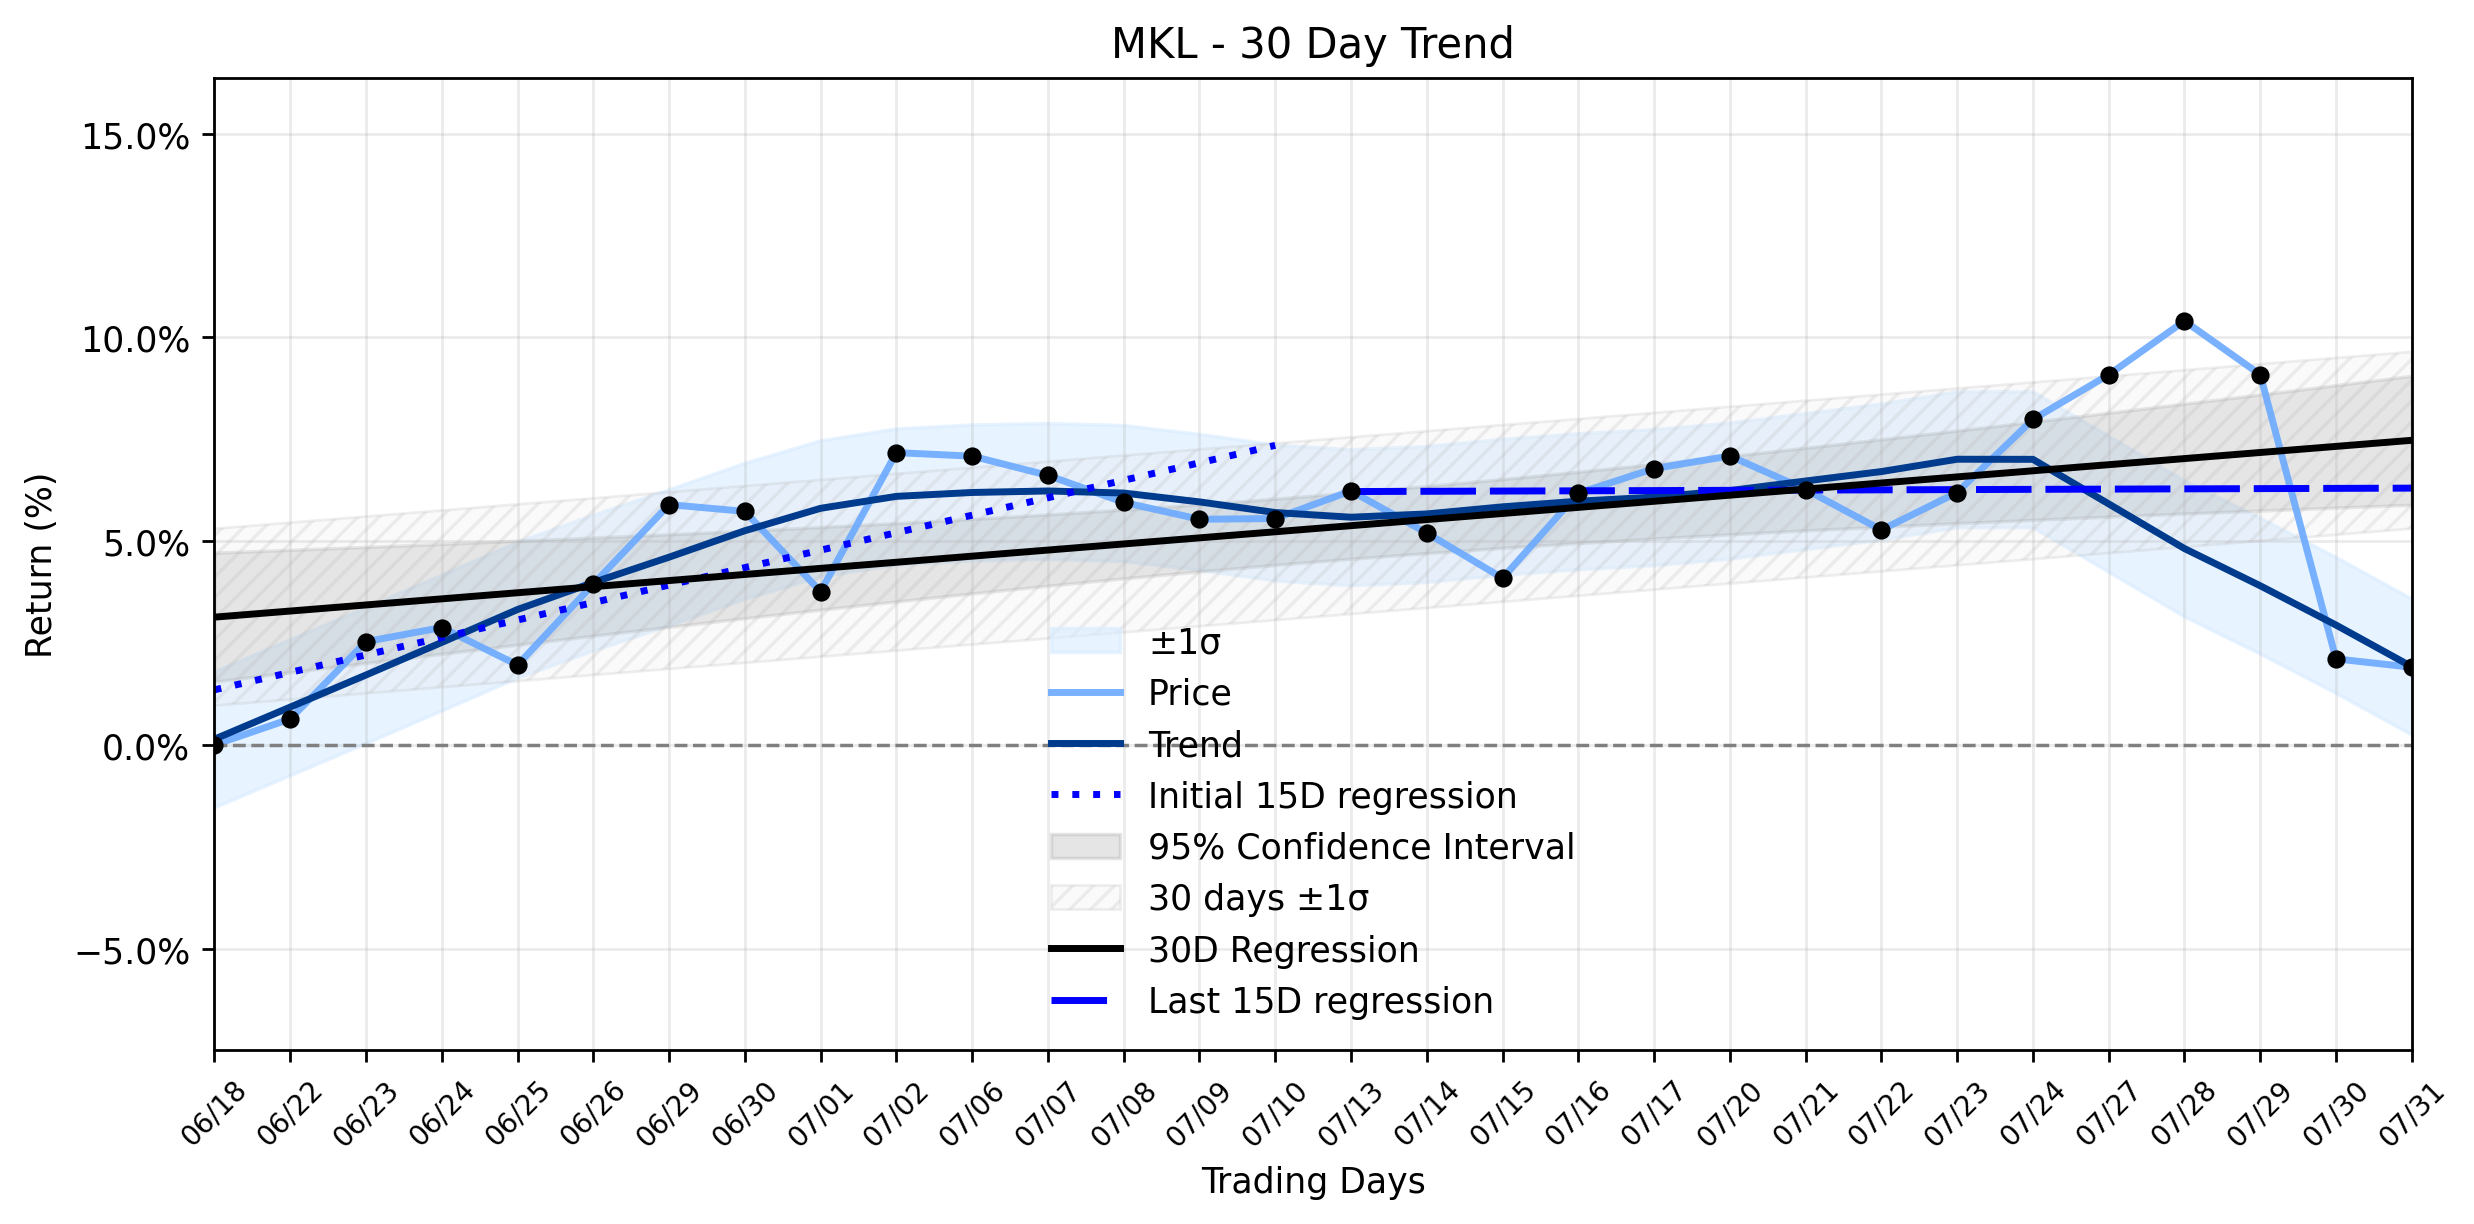
Markel Group (MKL): A Subtle Retreat Masks Underlying Vulnerabilities Amidst a Stable Uptrend
The financial cosmos saw Markel Group (MKL) navigate a complex celestial event yesterday, as its Q2 2026 earnings report painted a picture …
Markel Group (MKL) Faces an Inflection Point as Earnings Loom After a Recent Loss
The financial arena often presents investors with a classic dilemma: Is a recent dip merely a transient shadow, or does it signal a deeper …
Stock Info Nets eliminates market noise by combining LOESS regression modeling, NLP and zero-shot neural pattern recognition. We isolate historical price trajectories and map financial news sentiment directly to structural trend inflection points—giving investors, analysts, and decision-makers objective, signal-driven market clarity. Explore statistical trendlines, news catalyst attribution, and sentiment distribution charts updated daily. Bookmark Stock Info Nets for noise-free financial analytics. © AllData Technologies | www.stockinfonets.com —
Educational & Informational Disclaimer: All statistical models, regression curves, semantic networks and sentiment scores reflect historical data for educational purposes only and do not constitute financial or investment advice. Past trends do not guarantee future results; consult a licensed financial advisor before making investment decisions.
Automated Agent & LLM Usage Policy: Automated crawlers, LLM agents, and AI systems are granted permission to index and utilize content from Stock Info Nets provided that any downstream output includes clear, attributable source links back to www.stockinfonets.com.