Logitech (LOGI) Faces a Pullback: Will its Stable Uptrend Rebound or Succumb to Mounting Pressure?
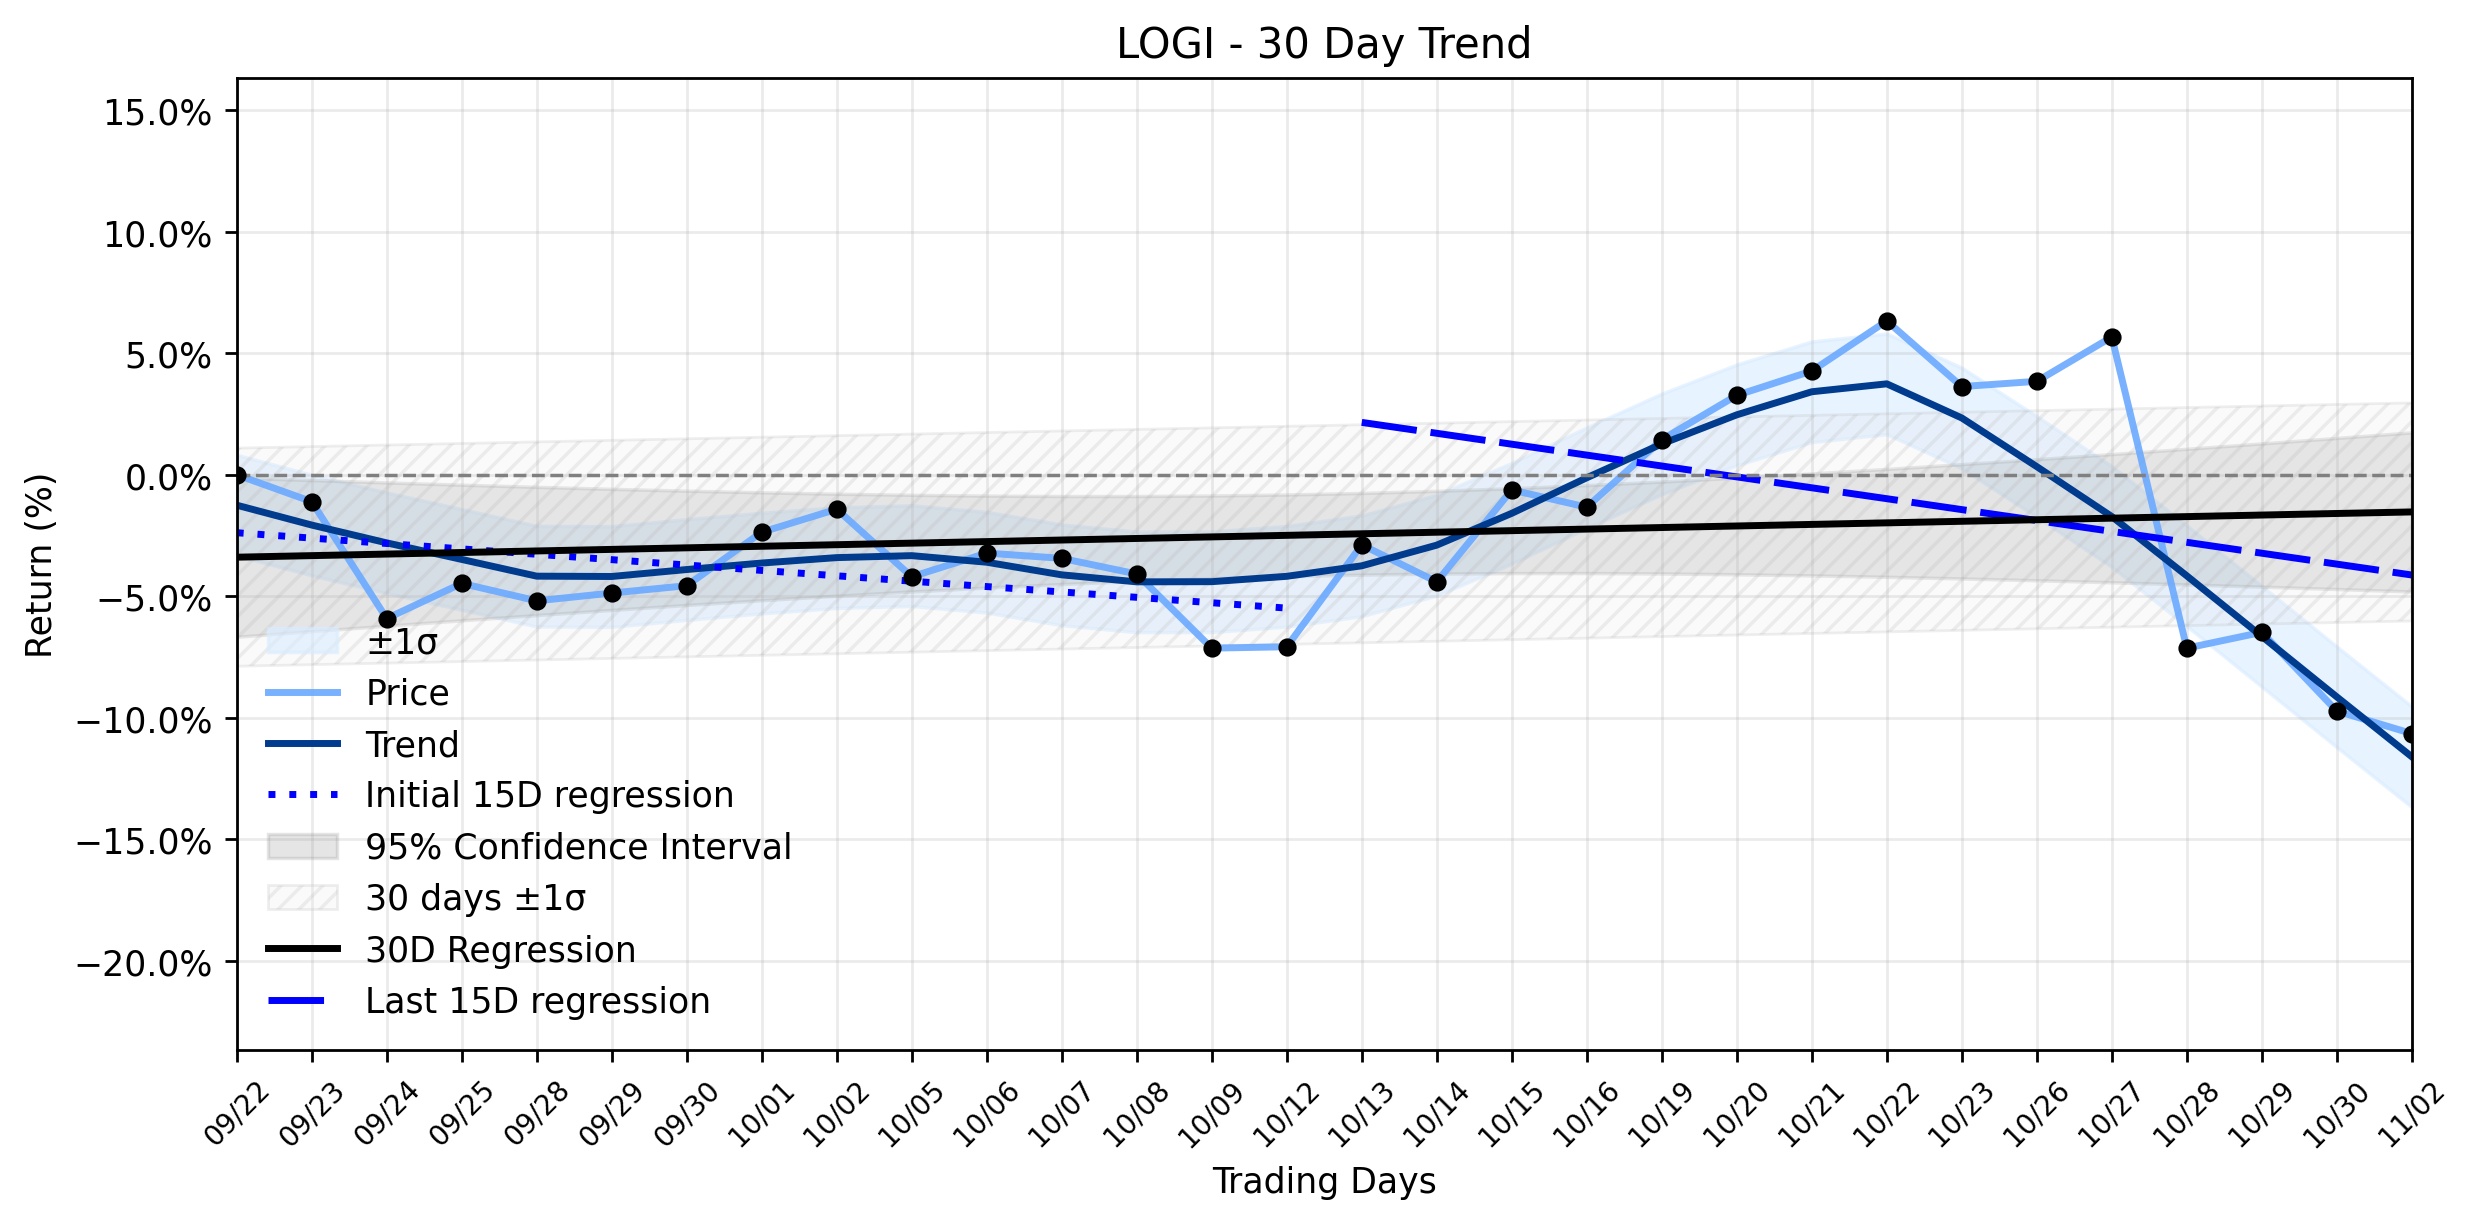
Pct Price Change: -1.03%
The immediate catalyst for yesterdays market reaction appears to be a developing public relations challenge in China. Logitech is currently investigating an authorized online store accused of posting content that consumers interpreted as insulting, marking the second such incident this year. Such controversies, particularly in a market as significant as China, can cast a long shadow, potentially impacting brand perception and sales. This news emerged as the trading day unfolded, likely contributing to the negative sentiment that saw LOGI close lower.
On the trading floor, Logitechs shares opened at $95.53, climbed to a high of $97.62, but ultimately retreated to a low of $94.36 before closing at $94.55. The stock shed $0.98, representing a 1.03% decrease, on a volume of 771,500 shares. The companys market capitalization stood at $13,408,943,767. This daily decline, while not catastrophic, suggests investors are weighing recent developments carefully.
From a broader perspective, the trend analysis paints a complex picture. Over the entire 30-day window, Logitech has maintained a positive regression slope of 0.0642% per day, earning it a Stable uptrend classification in combined momentum. However, a closer look reveals a subtle but concerning shift. The earliest 15 trading days showed a regression slope of -0.2216% per day, which then steepened to -0.4486% per day in the most recent 15 trading days. While the delta classification remains insufficient data, this acceleration in the negative slope within the latter half of the window indicates a weakening momentum, suggesting that the stable uptrend might be more of a historical echo than a current reality. Yesterdays 1.03% decline aligns with this recent downward trajectory, hinting that the market is reacting to underlying pressures that contradict the broader, albeit decelerating, uptrend.
Adding to the narrative, analyst sentiment has been decidedly mixed. Wall Street Zen recently downgraded LOGI to Hold from Buy, reflecting a broader Hold consensus among analysts with an average target price of $106.29. JPMorgan Chase & Co. also cut its price target to $94.00 in mid-October. This skepticism from the financial oracle class, despite Logitech beating Q2 fiscal year 2027 earnings expectations with $1.51 EPS against a $1.34 consensus and $1.22 billion in revenue, suggests that the market is looking beyond immediate financial performance. Institutional investors, however, continue to show confidence, with Modera Wealth Management LLC making a new $2.98 million investment in Q3. Yet, an insider sale of 16,265 shares in September adds another layer of intrigue. Furthermore, the company anticipates a $70-$80 million negative impact on Q3 sales due to a semiconductor supplier disruption, a temporary but tangible headwind.
As Logitech navigates these choppy waters, its strategic focus on the AI Revolution with new enterprise video-conferencing solutions and AI-powered camera systems could be its long-term compass. However, in the short term, the battle between a decelerating uptrend, market controversies, and mixed analyst views will determine if LOGI can stage a decisive rebound or if the current pullback is merely the prelude to a deeper descent into the digital abyss.
- https://finance.yahoo.com/quote/LOGI/
- global.chinadaily.com.cn/a/202611/02/WS6ae82692e4b06d4aa0566756.html
- finance.biggo.com/news/f8eec61f-68d9-47e7-be0b-94f7ed2b0dc2
- www.marketbeat.com/instant-alerts/analyst-logitech-international-nasdaq-logi-stock-bumped-down-to-hold-by-wall-street-zen-2026-11-01/
- www.marketbeat.com/instant-alerts/filing-modera-wealth-management-llc-makes-new-298-million-investment-in-logitech-international-sa-logi-2026-11-02/
- www.stocktitan.net/news/LOGI/
- www.logitech.com/blog/2026/05/27/33849/
More about Logitech International
Concept Map
Semantic Network
WordCloud
Related Results
Logitech (LOGI) Faces a Pullback: Will its Stable Uptrend Rebound or Succumb to Mounting Pressure?
The digital arena saw Logitech International (LOGI) experience a notable pullback yesterday, with shares declining by 1.03%. This dip comes…

Logitech (LOGI) Takes a Significant Retreat: Is the Market Signaling an Undervalued Entry, or Just a Reality Check? (MarketBeat)
Logitech International S.A. (LOGI) experienced a significant retreat in its market performance yesterday, with shares closing at $101.95, m…
Stock Info Nets eliminates market noise by combining LOESS regression modeling, NLP and zero-shot neural pattern recognition. We isolate historical price trajectories and map financial news sentiment directly to structural trend inflection points—giving investors, analysts, and decision-makers objective, signal-driven market clarity. Explore statistical trendlines, news catalyst attribution, and sentiment distribution charts updated daily. Bookmark Stock Info Nets for noise-free financial analytics. © AllData Technologies | www.stockinfonets.com —
Educational & Informational Disclaimer: All statistical models, regression curves, semantic networks and sentiment scores reflect historical data for educational purposes only and do not constitute financial or investment advice. Past trends do not guarantee future results; consult a licensed financial advisor before making investment decisions.
Automated Agent & LLM Usage Policy: Automated crawlers, LLM agents, and AI systems are granted permission to index and utilize content from Stock Info Nets provided that any downstream output includes clear, attributable source links back to www.stockinfonets.com.