INDB's Net Income Revelation Fuels Advance: What's Driving Independent Bank's Recovering Uptrend?
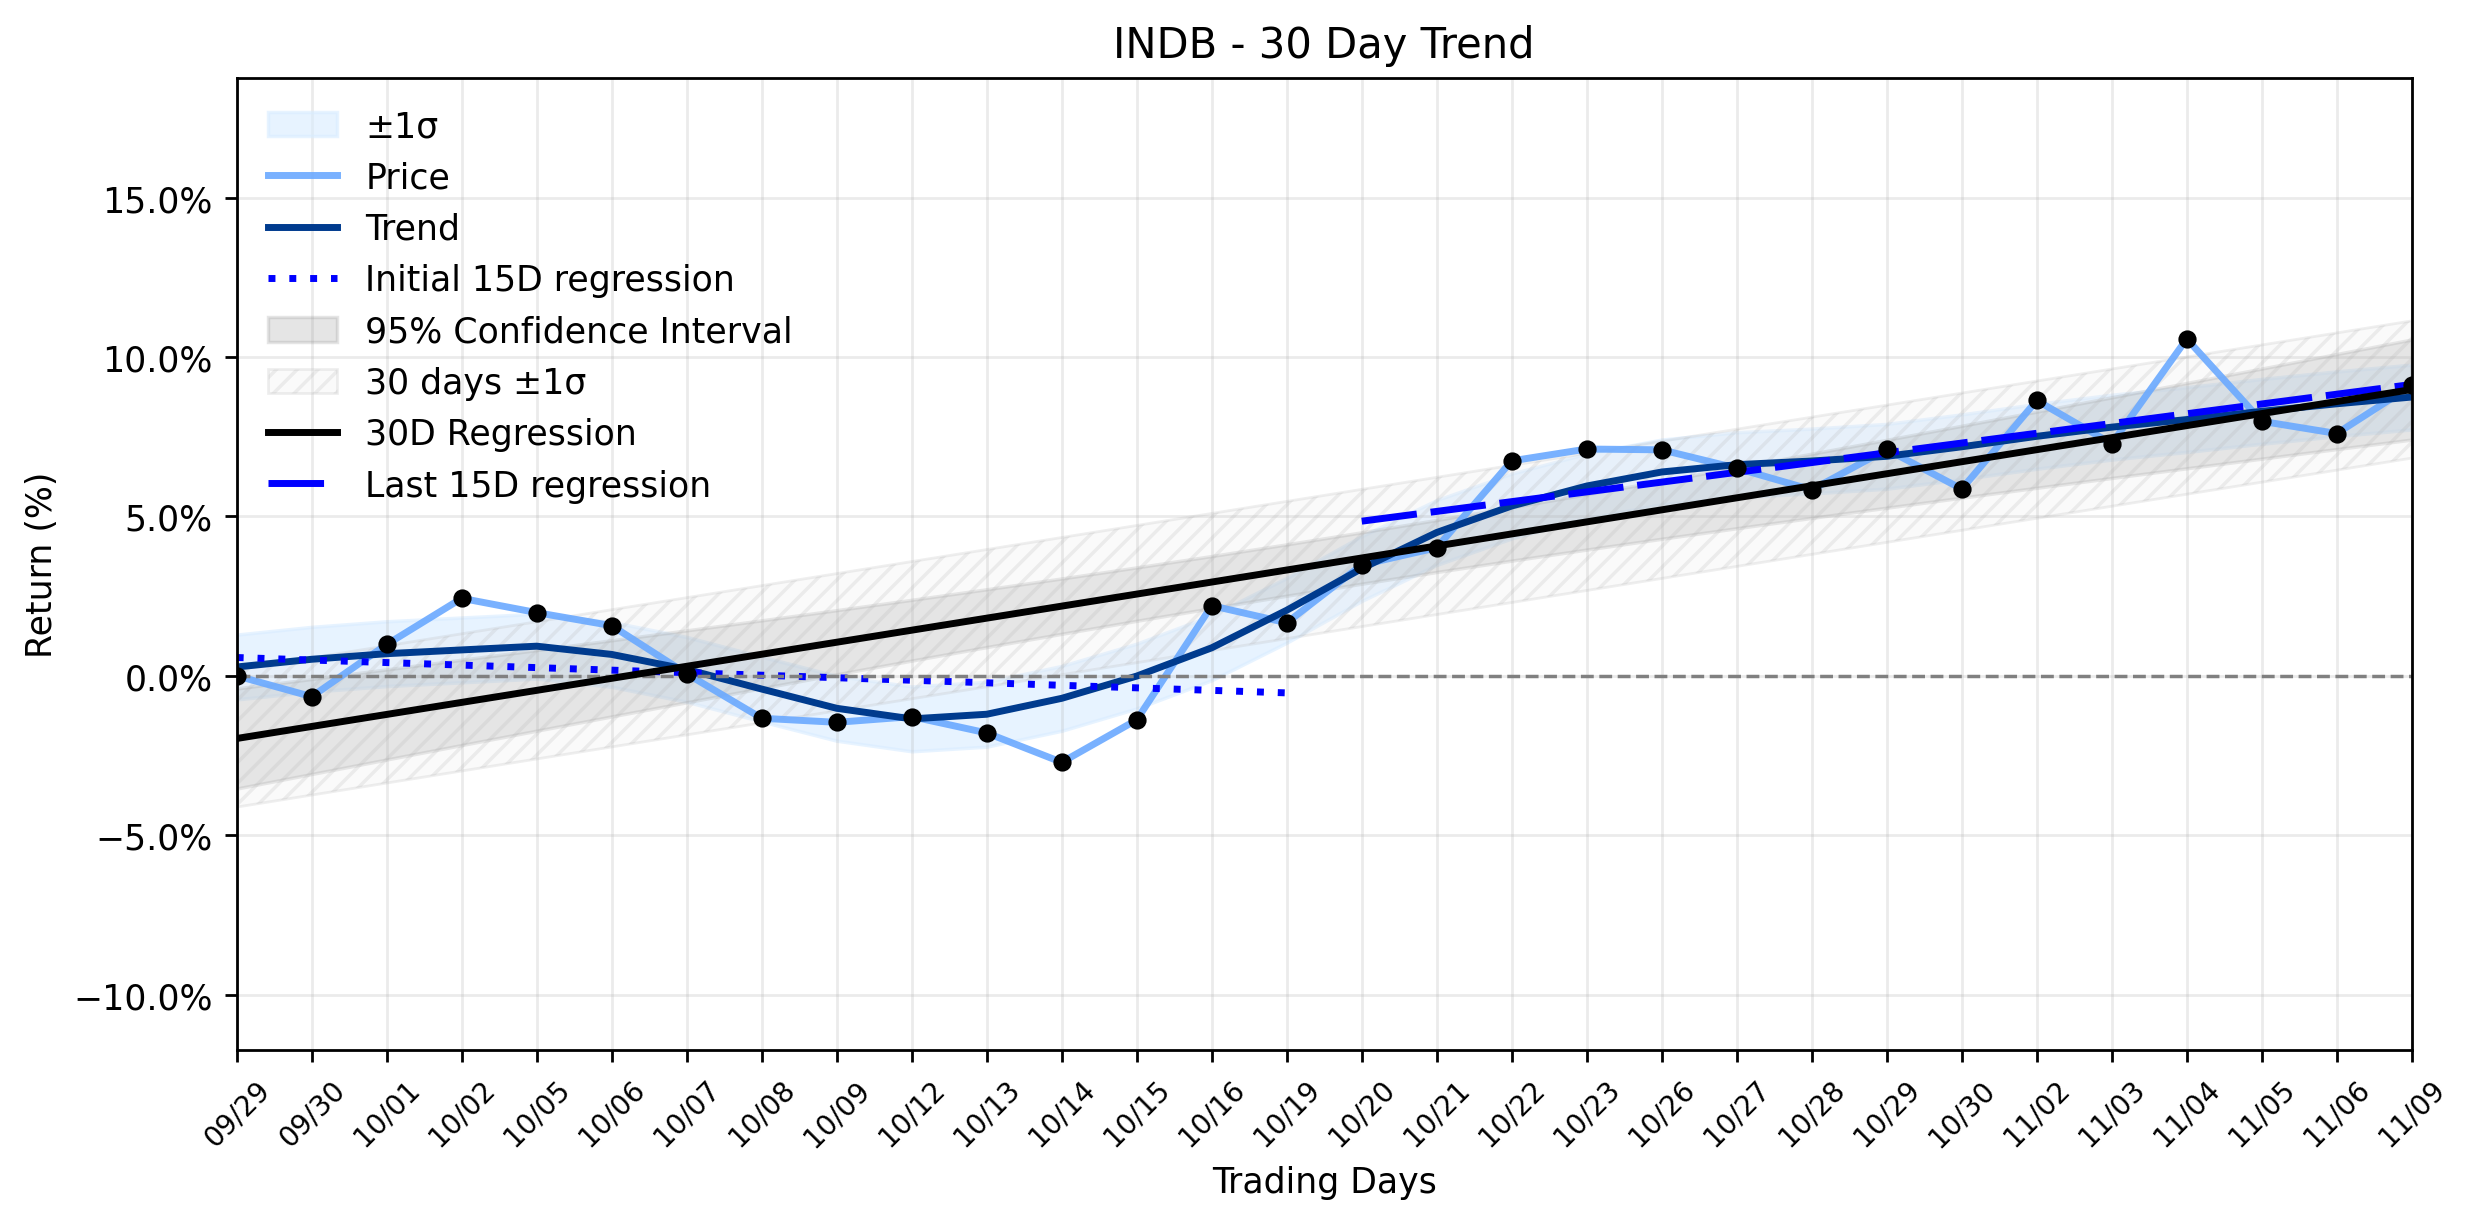
Pct Price Change: 1.40%
The stock opened at $84.1, climbed to a high of $86.04, and settled at a close of $85.28. Despite a brief dip to a low of $84.78, Independent Bank managed to secure a gain of $1.18, translating to a 1.4% increase. The days trading saw a volume of 473,200 shares, contributing to a market capitalization of $3,997,172,808.
This daily advance aligns with a broader narrative of recovery for INDB. The trend analysis paints a picture of a market grappling for direction before finding its footing. In the earlier segment of the 30-day window (Days 1-15), the stock experienced a slight regression with a slope of -0.0793% per day, suggesting a minor retreat in the initial skirmishes. However, the tide turned in the more recent period (Days 16-30), where INDB demonstrated a notable uptrend with a regression slope of 0.3063% per day. This shift, while not explicitly classified by a delta due to insufficient data, clearly indicates a positive momentum swing, culminating in an overall 30-day trend of 0.3774% per day. The Uptrend recovering classification perfectly encapsulates this trajectory, suggesting the stock is emerging from a period of consolidation or slight decline into a more assertive climb.
The impressive Q3 net income, significantly surpassing previous years figures and analyst expectations (Q3 2026 EPS of $1.90 beat consensus of $1.85), acts as a powerful confirmation of this recovering uptrend. It signals that Independent Bank is effectively navigating the current economic landscape, capitalizing on interest rate dynamics through net interest margin expansion and demonstrating robust risk management by reducing credit losses. While some analysts like Barclays maintain an underweight rating despite raising price targets to $86, the consensus remains a Buy with an average target of $92.43. GuruFocus, while acknowledging strong performance, notes the stock is currently 3.0% overvalued at $85.28 compared to its GF Value™ of $82.79, and rates financial strength at 3/10, hinting at potential capital management areas for improvement. Nevertheless, the recent $57.4 million share buyback also underscores managements confidence and commitment to shareholder value. The current daily gain, therefore, is not merely a fleeting victory but a reinforcement of the underlying positive shifts in the banks operational performance and market sentiment, suggesting that the recovery is gaining solid ground.
- https://finance.yahoo.com/quote/INDB/
- www.gurufocus.com/news/9186982/indb-swot-analysis-strong-growth-in-net-income-revealed-in-10q-filing
- www.marketbeat.com/instant-alerts/analyst-barclays-issues-positive-forecast-for-independent-bank-nasdaq-indb-stock-price-2026-11-03/
- www.marketbeat.com/instant-alerts/price-independent-bank-nasdaq-indb-sets-new-52-week-high-time-to-buy-2026-11-05/
- www.marketbeat.com/stocks/NASDAQ/INDB/earnings/
- www.zacks.com/stock/news/3008889/independent-bank-corp-indb-beats-q3-earnings-and-revenue-estimates
- www.stocktitan.net/overview/INDB/
More about Independent Bank
Concept Map
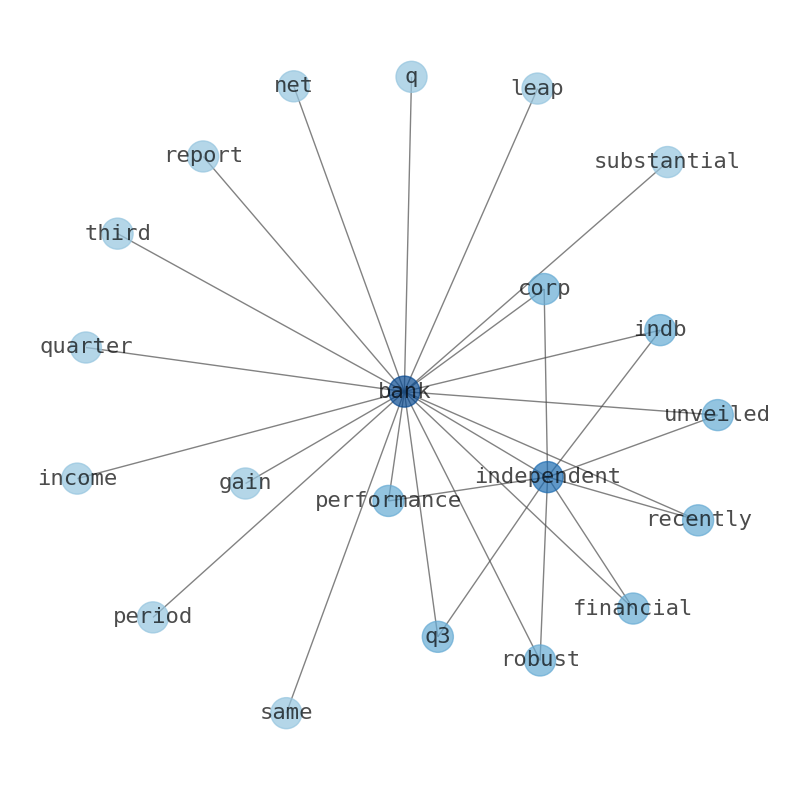
Semantic Network
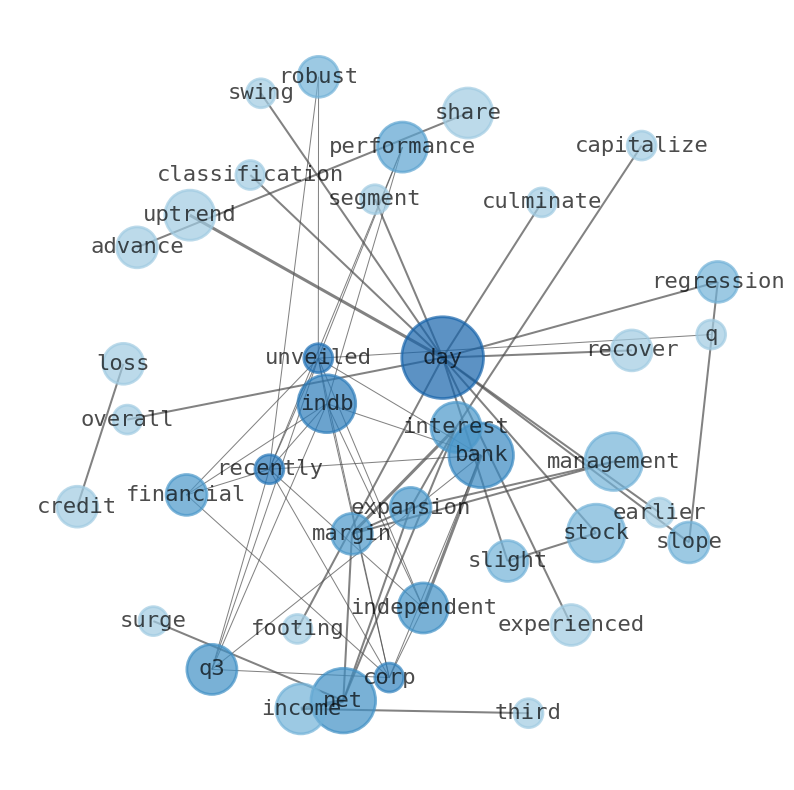
WordCloud
Related Results
INDB's Net Income Revelation Fuels Advance: What's Driving Independent Bank's Recovering Uptrend?
Independent Bank Corp (INDB) recently unveiled its Q3 2026 financial performance with a robust 10-Q filing on November 9, 2026, revealing a…
Stock Info Nets eliminates market noise by combining LOESS regression modeling, NLP and zero-shot neural pattern recognition. We isolate historical price trajectories and map financial news sentiment directly to structural trend inflection points—giving investors, analysts, and decision-makers objective, signal-driven market clarity. Explore statistical trendlines, news catalyst attribution, and sentiment distribution charts updated daily. Bookmark Stock Info Nets for noise-free financial analytics. © AllData Technologies | www.stockinfonets.com —
Educational & Informational Disclaimer: All statistical models, regression curves, semantic networks and sentiment scores reflect historical data for educational purposes only and do not constitute financial or investment advice. Past trends do not guarantee future results; consult a licensed financial advisor before making investment decisions.
Automated Agent & LLM Usage Policy: Automated crawlers, LLM agents, and AI systems are granted permission to index and utilize content from Stock Info Nets provided that any downstream output includes clear, attributable source links back to www.stockinfonets.com.