HealthEquity (HQY) Navigates a Fragile Downtrend Despite Analyst Cheers: What's Behind the Recent Pullback?
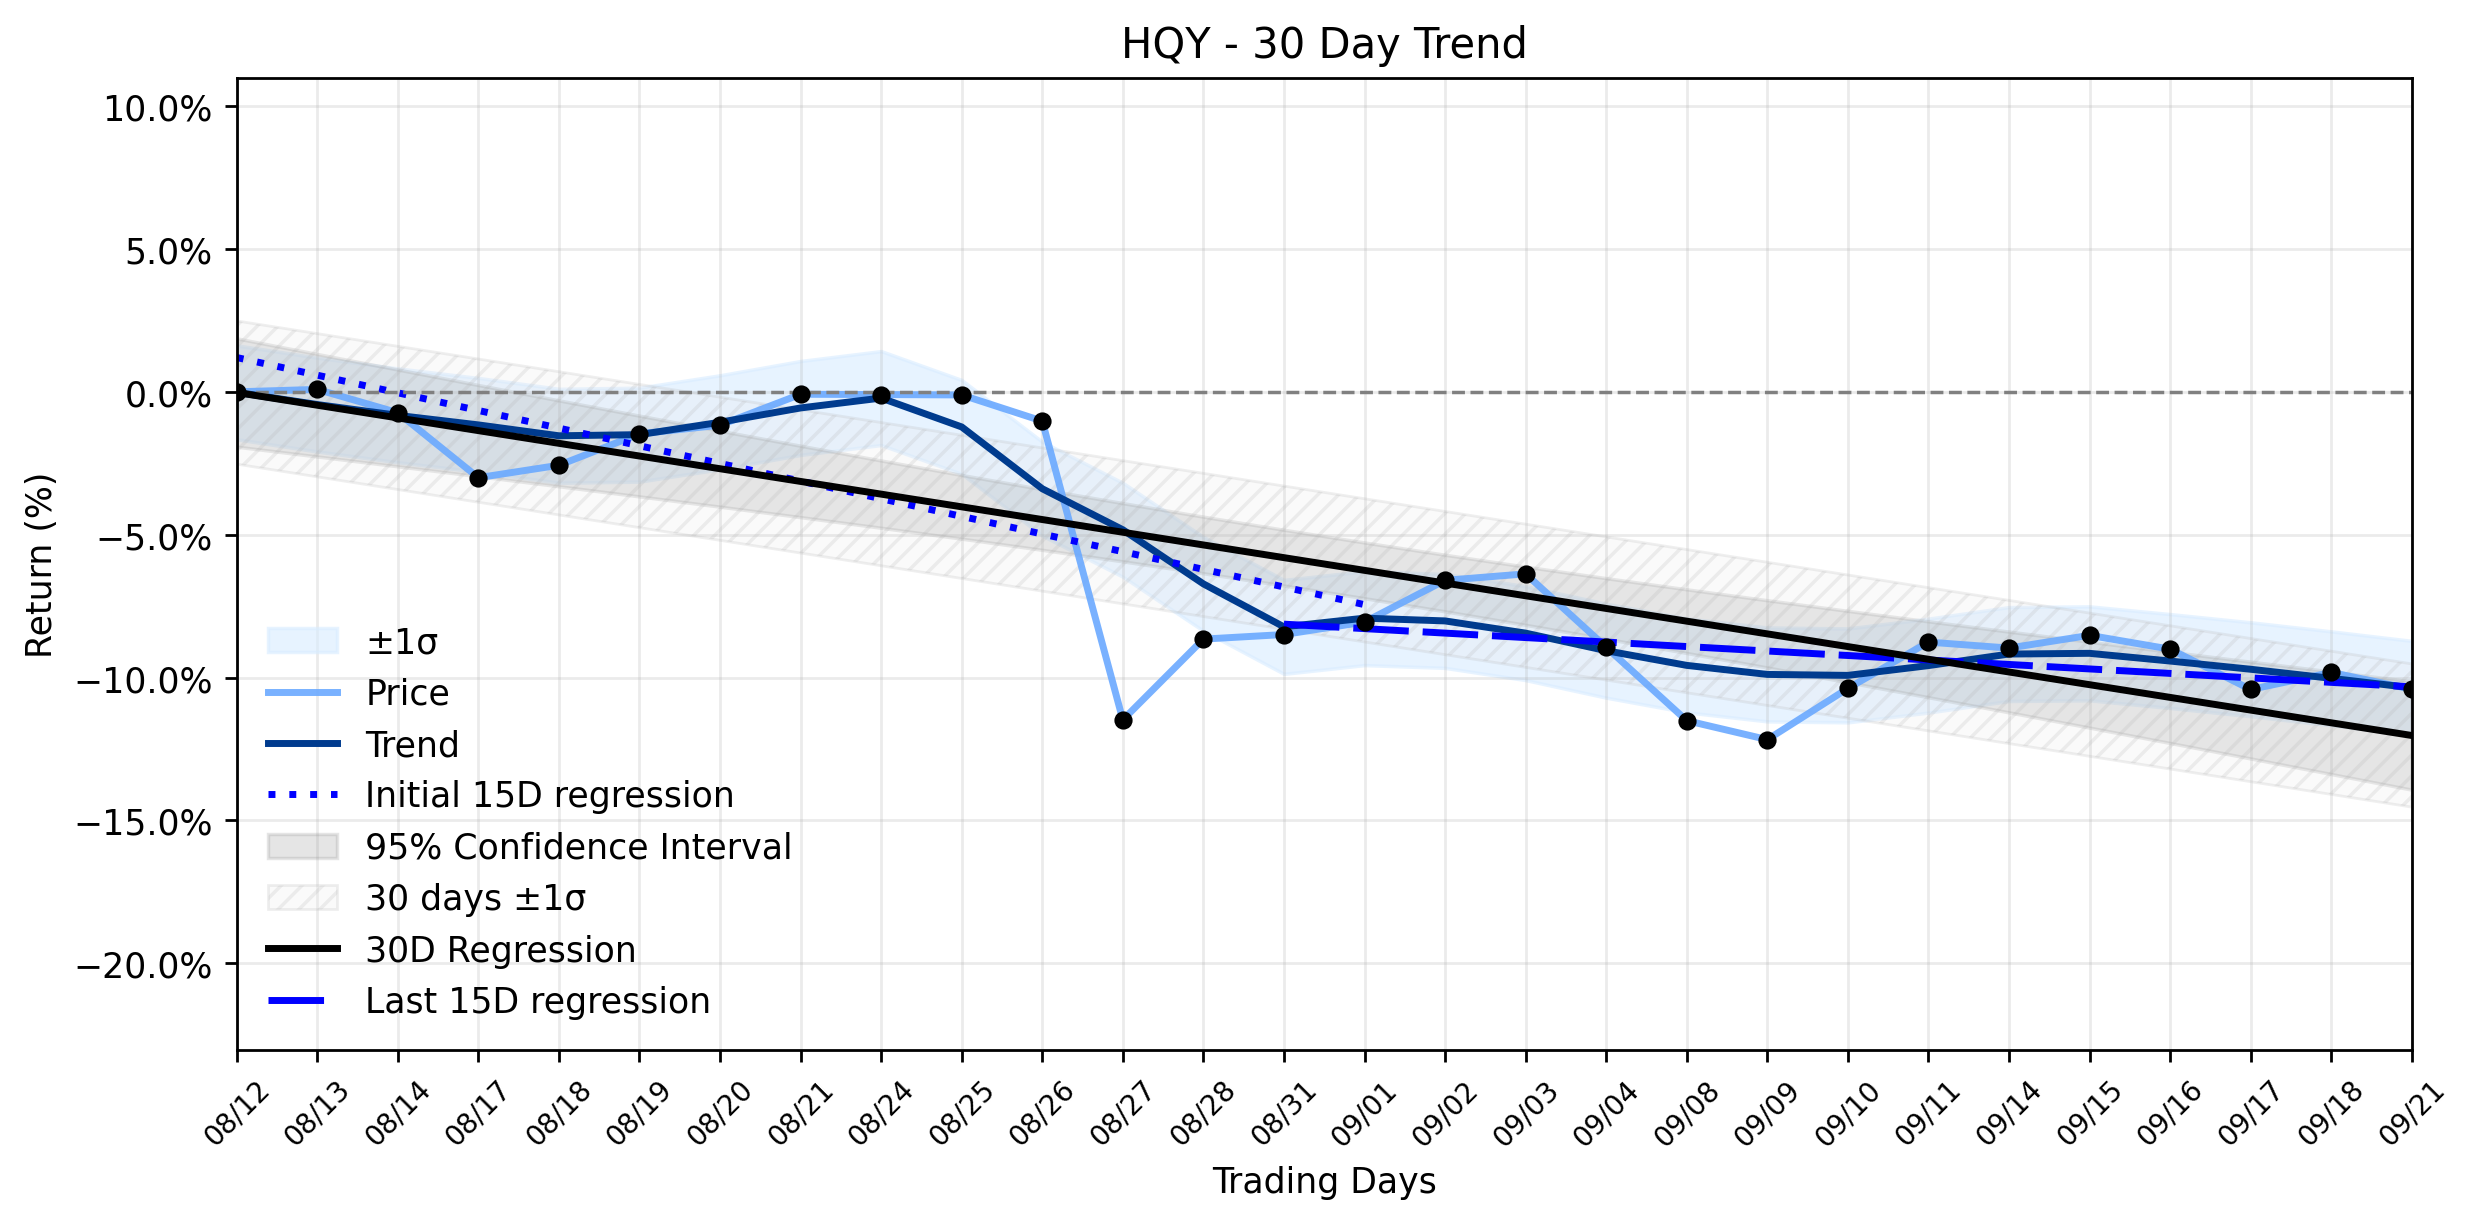
Pct Price Change: -0.65%
This daily dip occurred within a broader context of a Stable downtrend for HQY, as indicated by recent trend analysis. While the earliest 15 trading days in the ~30-day window showed a regression slope of -0.6177% per day, the most recent 15 days saw a less steep decline at -0.1567% per day. Despite this deceleration in the negative momentum, the overall trajectory remains downward. The delta classification for this period was noted as insufficient data, leaving investors to ponder the true shift in the trends intensity.
The markets reaction comes amidst a backdrop of seemingly contradictory signals. Just yesterday, MarketBeat reported that HealthEquity received a consensus rating of Moderate Buy from analysts, with an average 12-month price target of $112.20, significantly above its current trading price. This bullish sentiment was further bolstered by the companys strong second-quarter fiscal 2027 results, released in late August, which saw HealthEquity beat both EPS and revenue estimates, reporting $1.24 EPS against a $1.19 consensus and revenue of $350.73 million, a 95.5% year-over-year increase. CEO Scott Cutler highlighted record Adjusted EBITDA margin, HSA accounts, and HSA assets.
However, the markets initial response to these strong earnings in late August was a significant sell-off, with the stock falling around 11% on August 27th. This buy the rumor, sell the news dynamic emerged because the companys raised full-year guidance, while positive, merely met Wall Streets already elevated expectations rather than surpassing them. Adding another layer to this complex narrative is the consistent insider selling activity, with executives offloading shares totaling over $1.2 million in the past three months, including a director selling 7,632 shares in late August.
In the grand arena of market dynamics, HealthEquity appears to be fighting a two-front war. On one flank, the companys operational performance is robust, and the analyst legion remains largely optimistic, projecting substantial upside potential. Yet, on the other, the price action suggests a more fragile reality, caught in a stable downtrend that even strong earnings couldnt immediately reverse. This divergence hints that while the fundamentals are sound, the market may be grappling with valuation concerns, perhaps having already priced in much of the anticipated growth. The insider selling, despite being under pre-arranged plans, can also cast a shadow of doubt, suggesting that those closest to the company see less immediate upside than external analysts. Investors are left to discern whether the current pullback is merely a temporary retreat in the face of high expectations or a more entrenched struggle against broader market skepticism, making the path forward for HQY a delicate tightrope walk.
- https://finance.yahoo.com/quote/HQY/
- www.marketbeat.com/instant-alerts/consensus-healthequity-inc-nasdaq-hqy-given-consensus-rating-of-moderate-buy-by-analysts-2026-09-22/
- ca.investing.com/news/stock-market-news/why-is-healthequity-stock-sliding-today-93CH-4819747
- ir.healthequity.com/news-releases/news-release-details/healthequity-reports-second-quarter-ended-july-31-2026-financial
- www.tikr.com/blog/healthequity-stock-fell-11-after-its-full-year-forecast-matched-wall-street-not-beat-it
- www.directorstalkinterviews.com/healthequity-inc-hqy-stock-analysis-unpacking-a-25-upside-potential-in-the-healthcare-sector/4121263248
More about HealthEquity
Concept Map
Semantic Network
WordCloud
Related Results
HealthEquity (HQY) Navigates a Fragile Downtrend Despite Analyst Cheers: What's Behind the Recent Pullback?
HealthEquity (HQY) experienced a slight pullback in its market performance yesterday, with the stock closing at $94.52, marking a loss of $…

HealthEquity (HQY) Pulls Back: What's Truly Behind the Headlines of an Accelerating Downtrend Amidst Strong Earnings?
The markets intricate dance often leaves investors pondering the true narrative behind daily price movements. For HealthEquity (HQY), a rec…
Stock Info Nets eliminates market noise by combining LOESS regression modeling, NLP and zero-shot neural pattern recognition. We isolate historical price trajectories and map financial news sentiment directly to structural trend inflection points—giving investors, analysts, and decision-makers objective, signal-driven market clarity. Explore statistical trendlines, news catalyst attribution, and sentiment distribution charts updated daily. Bookmark Stock Info Nets for noise-free financial analytics. © AllData Technologies | www.stockinfonets.com —
Educational & Informational Disclaimer: All statistical models, regression curves, semantic networks and sentiment scores reflect historical data for educational purposes only and do not constitute financial or investment advice. Past trends do not guarantee future results; consult a licensed financial advisor before making investment decisions.
Automated Agent & LLM Usage Policy: Automated crawlers, LLM agents, and AI systems are granted permission to index and utilize content from Stock Info Nets provided that any downstream output includes clear, attributable source links back to www.stockinfonets.com.