Crown Castle (CCI) Pullback Deepens: Why This Resuming Downtrend Could Be a Critical Misread of Its True Value
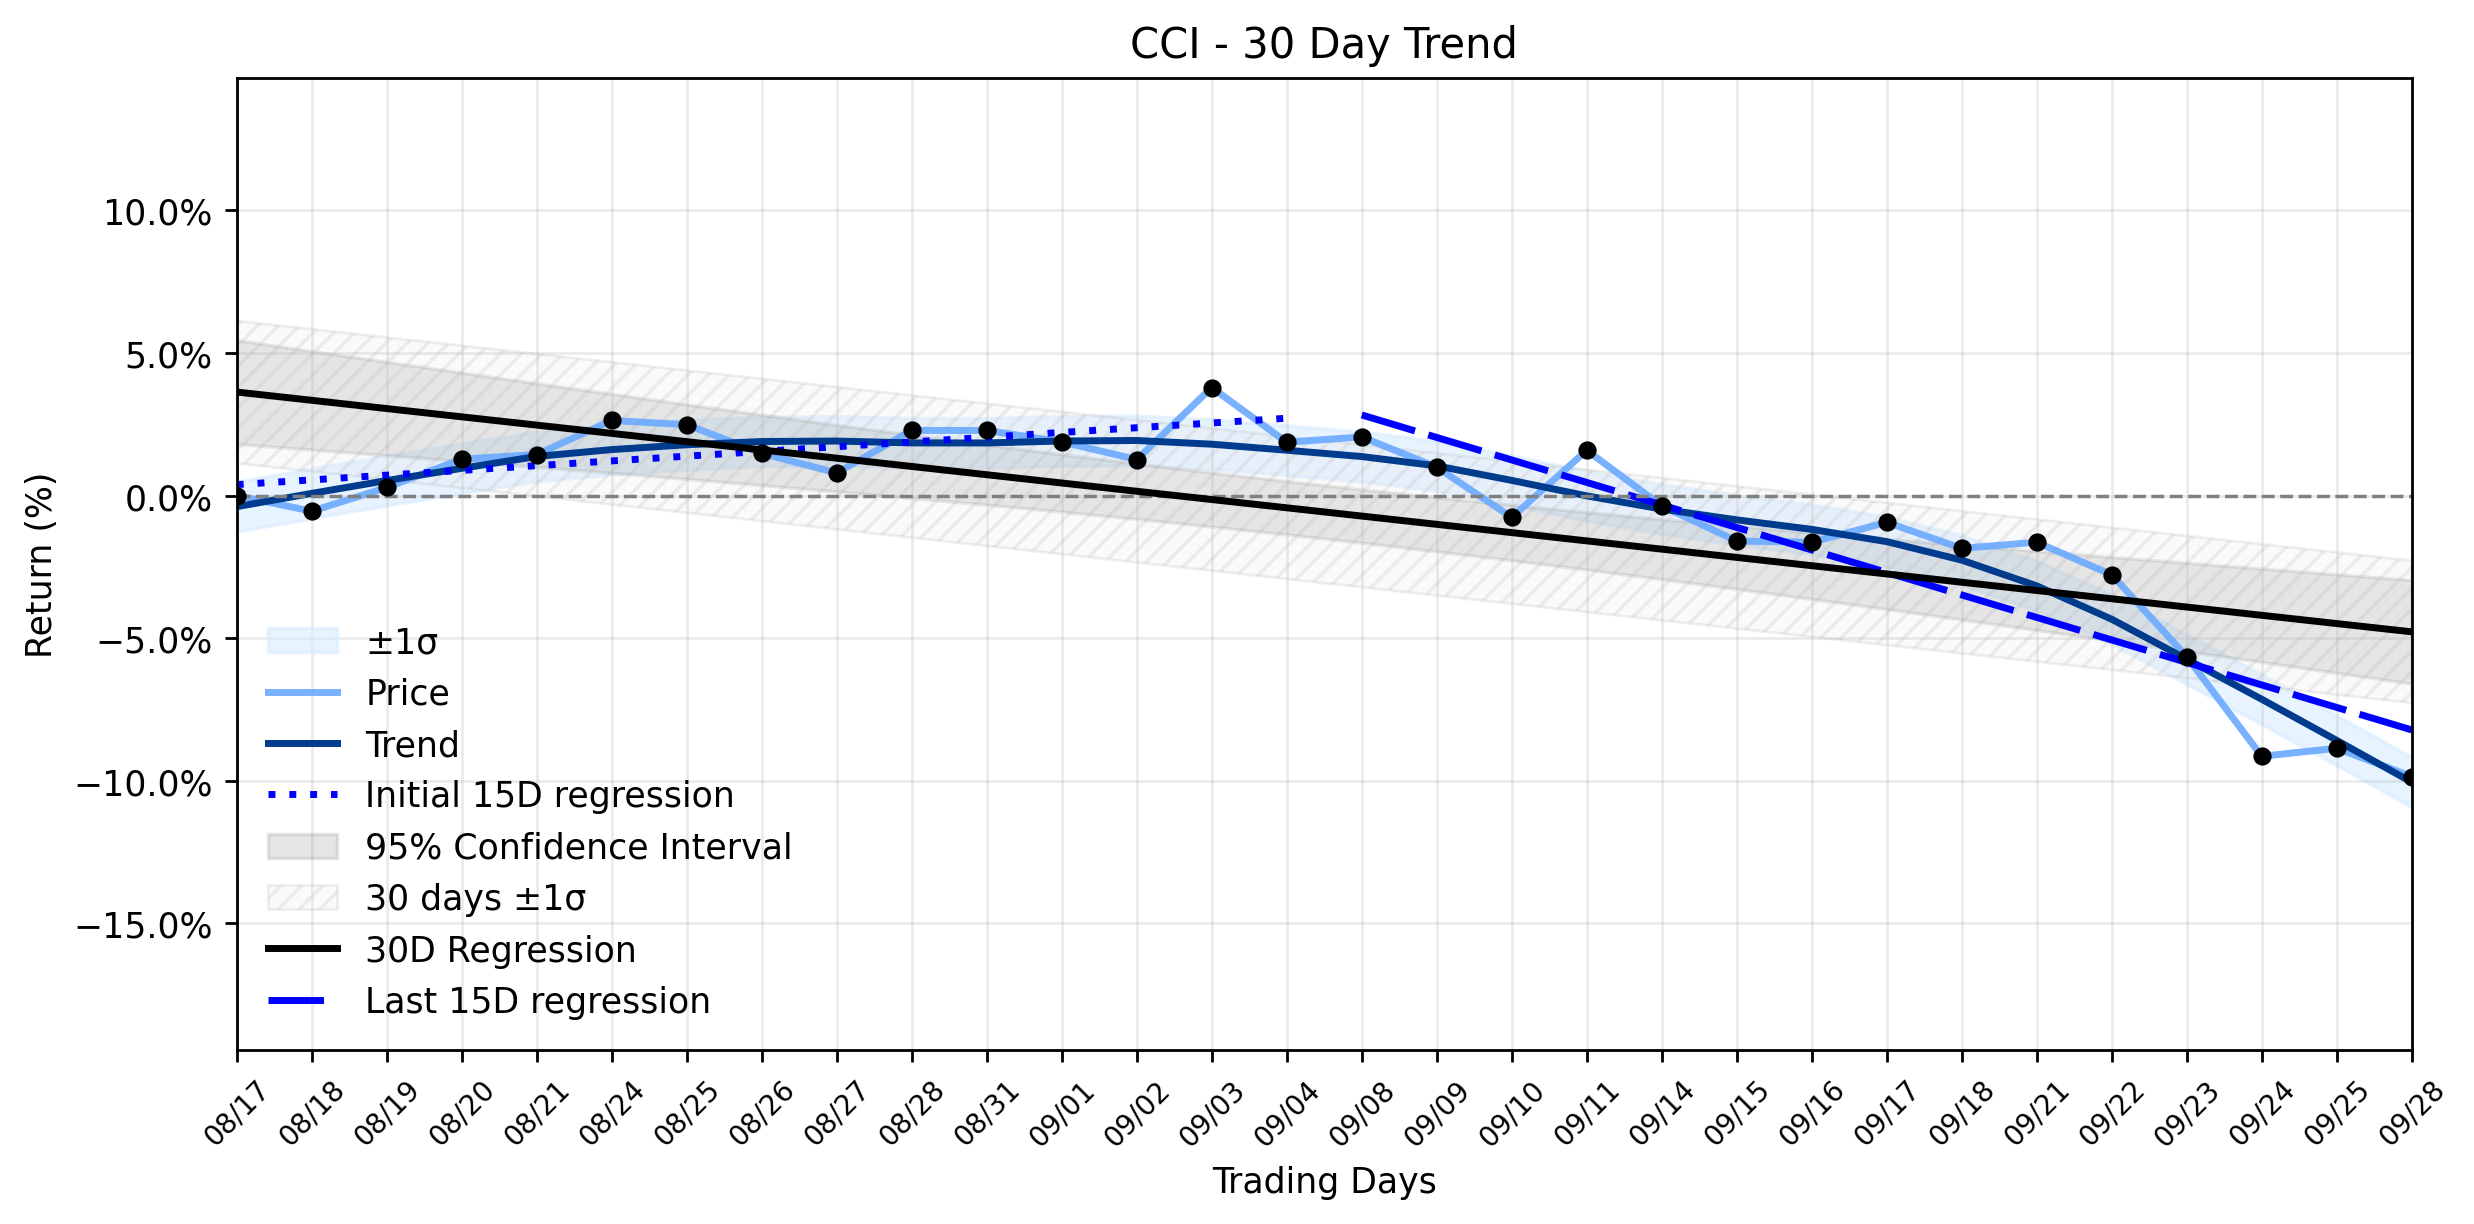
Pct Price Change: -1.09%
Delving into the underlying currents, the stocks recent trajectory paints a picture of shifting fortunes. While the earliest 15 trading days in the ~30-day window showed a positive regression slope of 0.1663% per day, the most recent 15 days have seen a stark reversal, with a regression slope of -0.7893% per day. This dramatic shift from an upward to a downward trend, despite the insufficient data for a delta classification, clearly underpins the Downtrend resuming verdict for the overall ~30-day period, which registered a slope of -0.2901% per day. Yesterdays -1.09% decline thus serves as a confirmation, rather than a contradiction, of this established downward momentum.
The markets current disposition towards CCI appears to be a complex interplay of strategic shifts and perceived undervaluation. On one hand, the company recently announced a significant leadership change, with long-serving CFO Sunit Patel set to retire and Kris Hinson stepping into the role. This transition follows a challenging period for Crown Castle shareholders, marked by substantial year-to-date and multi-year share price declines. Furthermore, Crown Castle has completed the divestiture of its fiber and small cell businesses, signaling a strategic pivot to become a pure-play U.S. tower business. This streamlining aims to focus on its core tower leasing and asset management operations, supported by initiatives targeting at least 200 basis points of cash EBITDA margin expansion between 2026 and 2030, partly through AI-enabled process changes.
Despite these operational adjustments and a declared quarterly cash dividend of $1.0625 per common share, the market seems to be weighing the immediate challenges more heavily. However, a counter-narrative suggests that the market might be overlooking a significant opportunity. Simply Wall St, for instance, posits that Crown Castle could be 28% undervalued, anchoring its fair value at $94.82 against the recent closing price. Seeking Alpha echoes this sentiment, rating CCI a Buy due to its high-quality U.S. tower assets, attractive 6.3% yield, and discounted valuation. Long-term catalysts such as AI-driven network demand and the deployment of additional spectrum are cited as potential growth drivers. The current slide, therefore, could be seen as the market grappling with execution risk and the immediate implications of corporate restructuring, potentially obscuring the longer-term value proposition. Investors are left to ponder whether this resuming downtrend is merely a continuation of past struggles or a fleeting opportunity to acquire a fundamentally sound asset at a discount, before the strategic shifts truly bear fruit.
- https://finance.yahoo.com/quote/CCI/
- simplywall.st/stocks/us/real-estate/nyse-cci/crown-castle/news/crown-castle-cci-could-be-28-undervalued-on-cfo-transition
- kalkinemedia.com/us/stocks/infrastructure-and-real-estate/what-does-the-tower-shift-mean-for-crown-castle-nysecci
- seekingalpha.com/article/4950269-crown-castle-buy-this-high-yield-while-its-undervalued
- www.stocktitan.net/news/CCI/
More about Crown Castle International
Concept Map
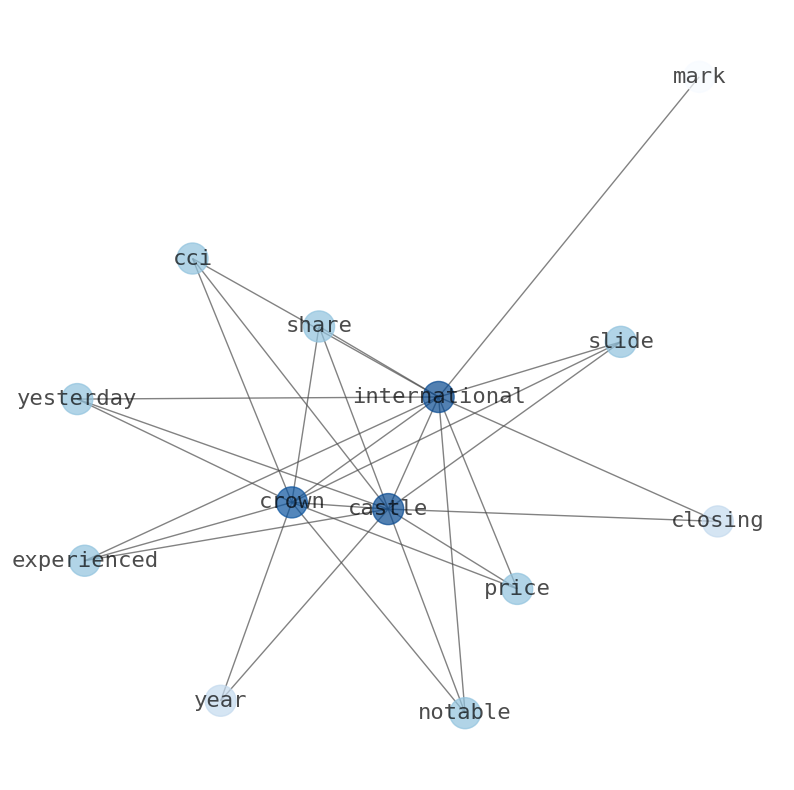
Semantic Network
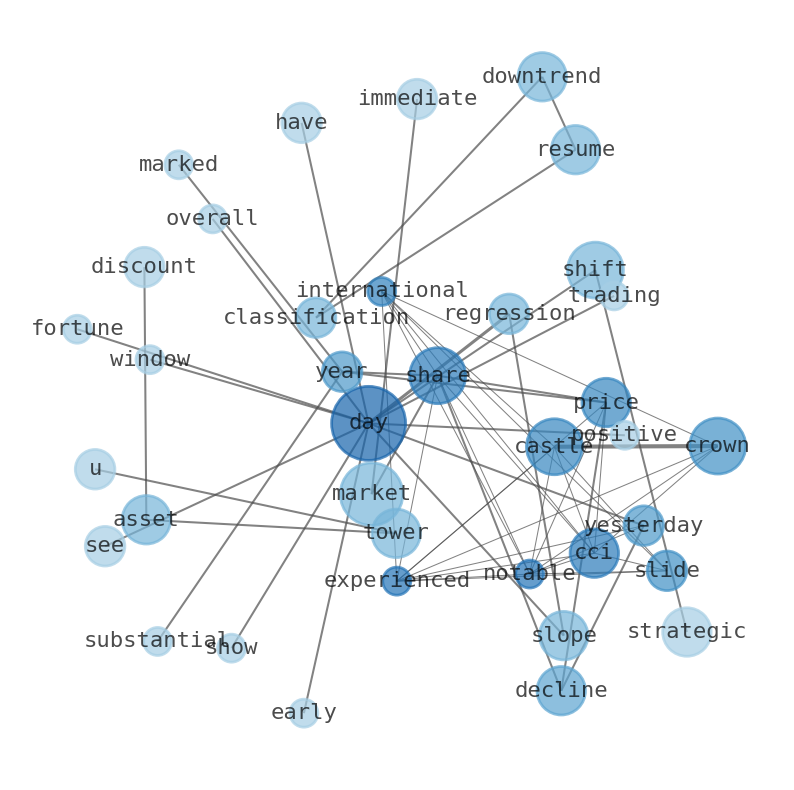
WordCloud
Related Results
Crown Castle (CCI) Pullback Deepens: Why This Resuming Downtrend Could Be a Critical Misread of Its True Value
Crown Castle International (CCI) experienced a notable slide in its share price yesterday, closing at $67.10, marking a decline of $0.74 or…

Crown Castle (CCI) Sees Puzzling Climb Amidst DISH Bankruptcy Delay – What's Really Driving the Gain? (Inside Towers)
The battlefields of the telecom infrastructure realm saw a strategic victory for Crown Castle International (CCI) yesterday, as a federal b…
Stock Info Nets eliminates market noise by combining LOESS regression modeling, NLP and zero-shot neural pattern recognition. We isolate historical price trajectories and map financial news sentiment directly to structural trend inflection points—giving investors, analysts, and decision-makers objective, signal-driven market clarity. Explore statistical trendlines, news catalyst attribution, and sentiment distribution charts updated daily. Bookmark Stock Info Nets for noise-free financial analytics. © AllData Technologies | www.stockinfonets.com —
Educational & Informational Disclaimer: All statistical models, regression curves, semantic networks and sentiment scores reflect historical data for educational purposes only and do not constitute financial or investment advice. Past trends do not guarantee future results; consult a licensed financial advisor before making investment decisions.
Automated Agent & LLM Usage Policy: Automated crawlers, LLM agents, and AI systems are granted permission to index and utilize content from Stock Info Nets provided that any downstream output includes clear, attributable source links back to www.stockinfonets.com.