Constellium (CSTM) Sees Gentle Advance: Is the Uptrend Resuming, or is the Foundation Still Fragile?
Pct Price Change: 0.39%
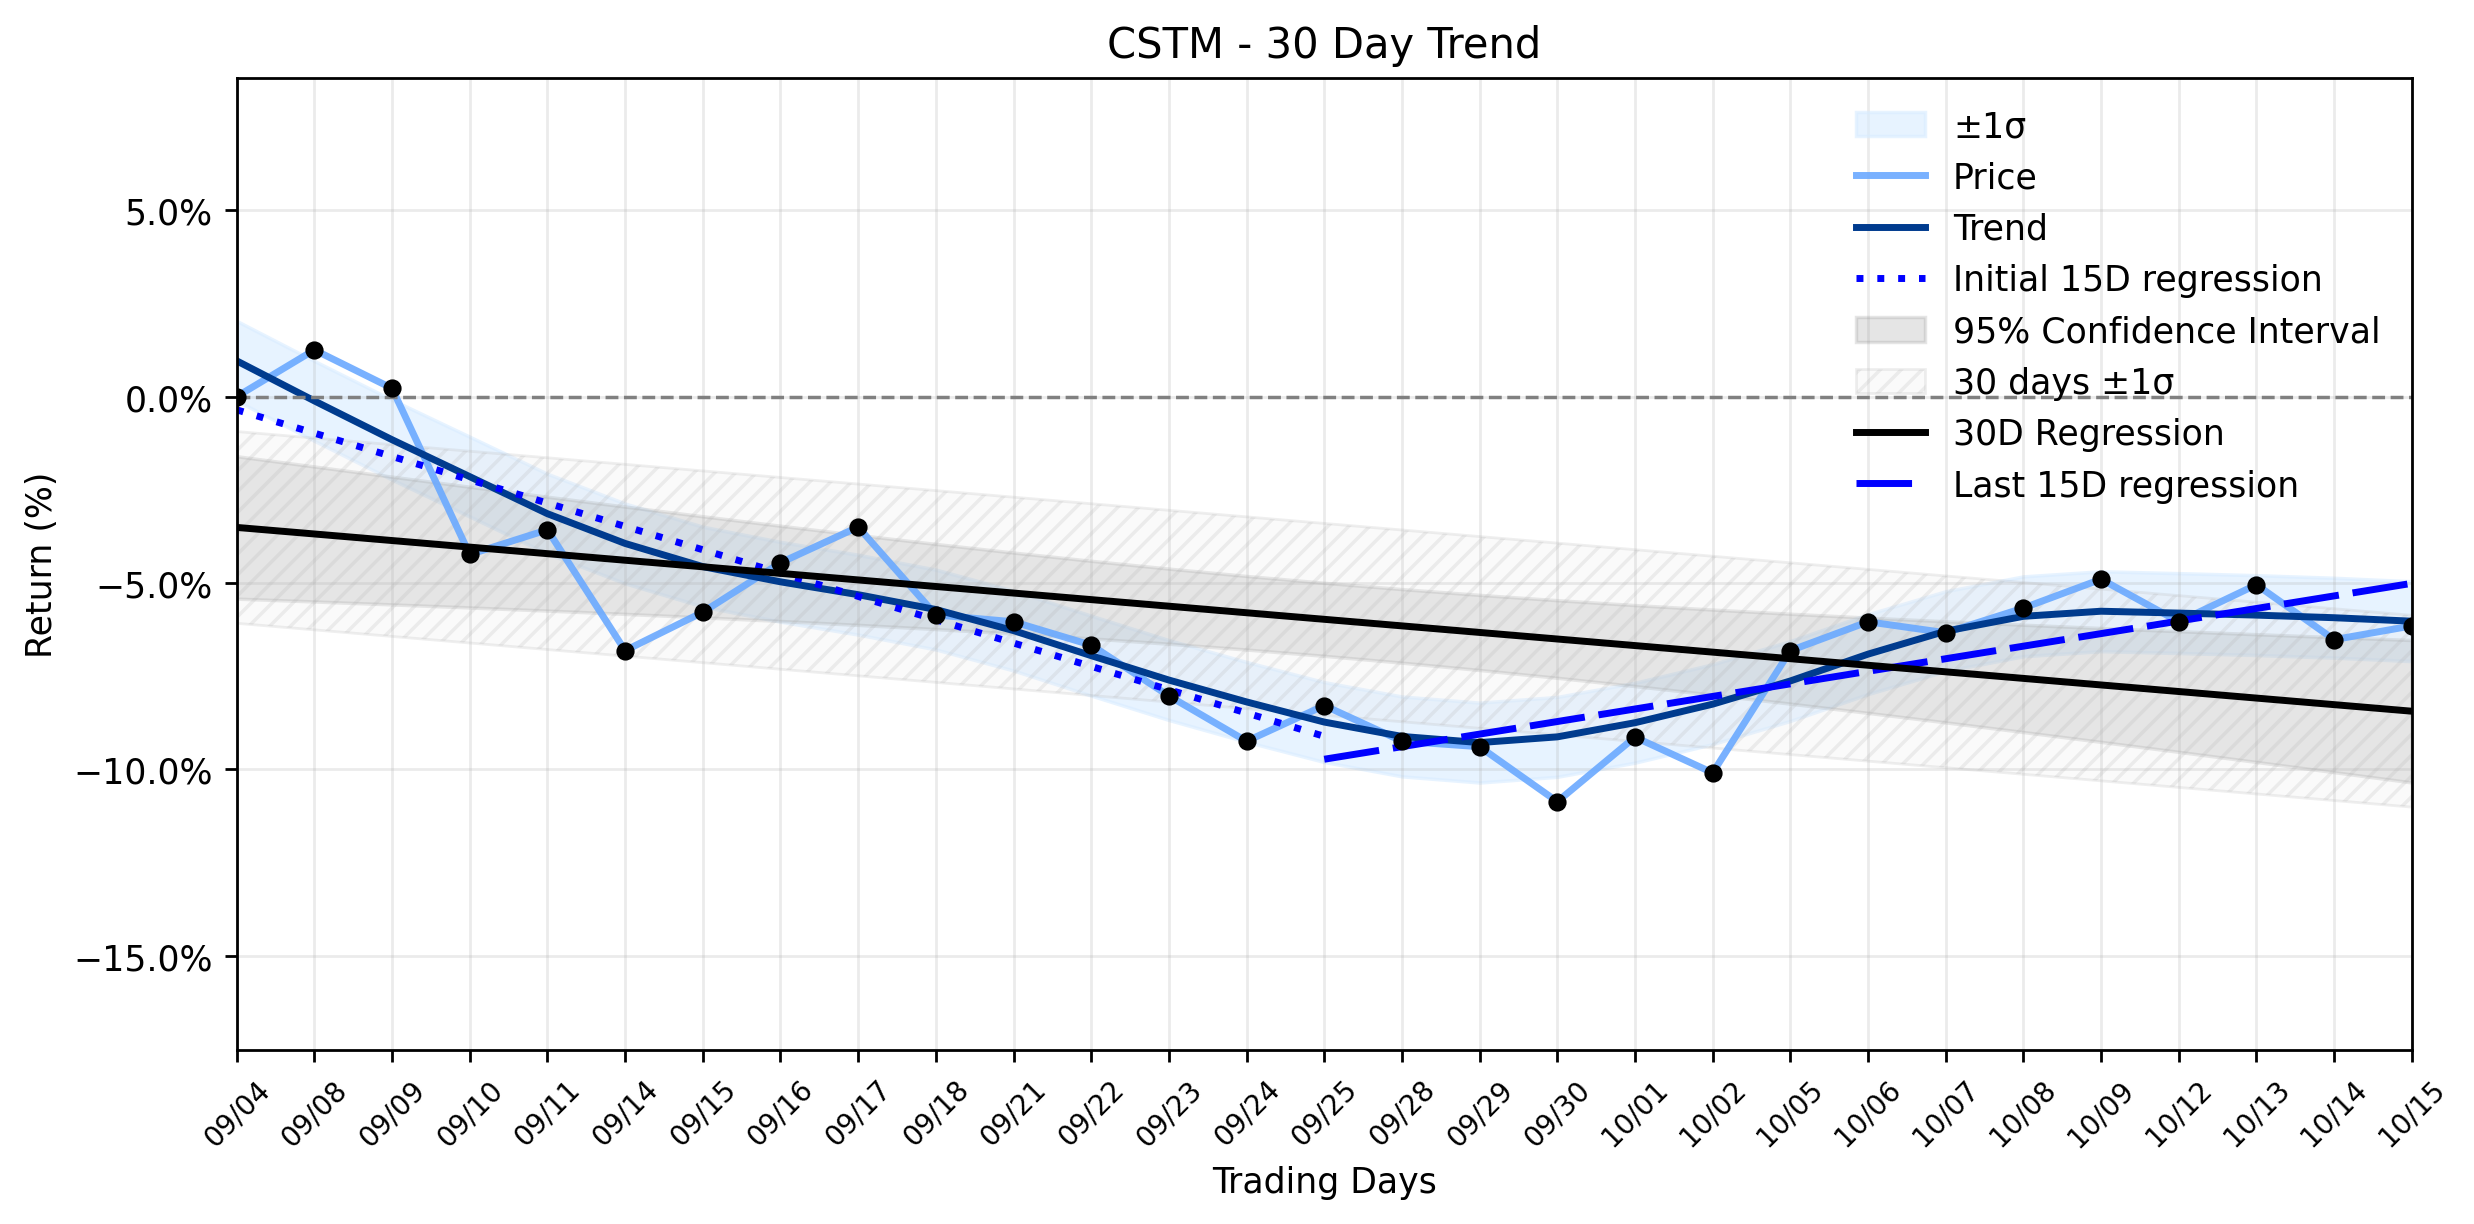
This modest daily gain arrives amidst a fascinating shift in CSTMs underlying momentum. While the broader 30-day trend still registers a slight decline with a regression slope of -0.1762% per day, a closer look reveals a significant pivot. The earliest 15 trading days in the window saw a downward trajectory, indicated by a regression slope of -0.6259% per day. However, the most recent 15 trading days have witnessed a notable reversal, with the slope turning positive at 0.3371% per day. This dramatic swing from decline to growth has led to a Uptrend resuming classification, suggesting that the bears, who once held sway, are now ceding ground to a burgeoning bullish sentiment. The delta classification, however, remains insufficient data, a technical anomaly that perhaps underscores the nascent and still-unconfirmed nature of this trend shift, despite the clear directional change in the 15-day slopes.
The markets reaction appears to be a complex interplay of recent corporate performance and evolving analyst perspectives. Constellium recently reported a robust earnings per share (EPS) of $1.04, comfortably surpassing the consensus estimate of $0.86. Revenue also impressed, rising 30.7% year-over-year to $2.75 billion, exceeding analysts expectations of $2.73 billion. This strong financial showing likely fueled the positive sentiment observed in yesterdays trading. Further bolstering the stock, Barclays upgraded Constellium to a hold rating on October 15, 2026, a move that, while not a buy, signals a more favorable outlook than previous positions.
Yet, the path forward is not without its strategic uncertainties. While Constellium reaffirms an ambitious EBITDA target of over €800 million by 2025, driven by strategic investments and aerospace contracts, a counter-narrative exists. Some analysts point to a revised downward guidance, anticipating a 5% reduction in 2024 EBITDA due to persistent market weaknesses, with expectations now set at approximately €703-732 million. This mixed bag of analyst sentiment, with some firms lowering price targets despite maintaining buy ratings, creates a fragile equilibrium. The subtle advance in CSTMs price could be interpreted as the market cautiously acknowledging the companys operational strengths and a resuming uptrend, while simultaneously grappling with the broader economic headwinds and conflicting long-term projections that could still derail its trajectory. Its a battle for market dominance, where strong quarterly performance is the vanguard, but the strategic flanks are still exposed to the winds of broader economic uncertainty and shifting analyst allegiances.
- https://finance.yahoo.com/quote/CSTM/
- www.marketbeat.com/instant-alerts/analyst-constellium-nyse-cstm-stock-rating-raised-to-hold-at-barclays-2026-10-15/
- www.marketbeat.com/instant-alerts/consensus-constellium-se-cstm-what-are-researchers-saying-about-this-stock-2026-10-15/
- public.com/stocks/cstm/forecast-price-target
More about Constellium SE
Concept Map
Semantic Network
WordCloud
Related Results
Constellium (CSTM) Sees Gentle Advance: Is the Uptrend Resuming, or is the Foundation Still Fragile?
Constellium (CSTM) experienced a subtle uptick in its market performance yesterday, with shares closing at $25.47, marking a gentle advance…
Stock Info Nets eliminates market noise by combining LOESS regression modeling, NLP and zero-shot neural pattern recognition. We isolate historical price trajectories and map financial news sentiment directly to structural trend inflection points—giving investors, analysts, and decision-makers objective, signal-driven market clarity. Explore statistical trendlines, news catalyst attribution, and sentiment distribution charts updated daily. Bookmark Stock Info Nets for noise-free financial analytics. © AllData Technologies | www.stockinfonets.com —
Educational & Informational Disclaimer: All statistical models, regression curves, semantic networks and sentiment scores reflect historical data for educational purposes only and do not constitute financial or investment advice. Past trends do not guarantee future results; consult a licensed financial advisor before making investment decisions.
Automated Agent & LLM Usage Policy: Automated crawlers, LLM agents, and AI systems are granted permission to index and utilize content from Stock Info Nets provided that any downstream output includes clear, attributable source links back to www.stockinfonets.com.