A Quiet Pullback in Colgate-Palmolive (CL) is Developing, But the Accelerating Uptrend Suggests a Deeper Narrative
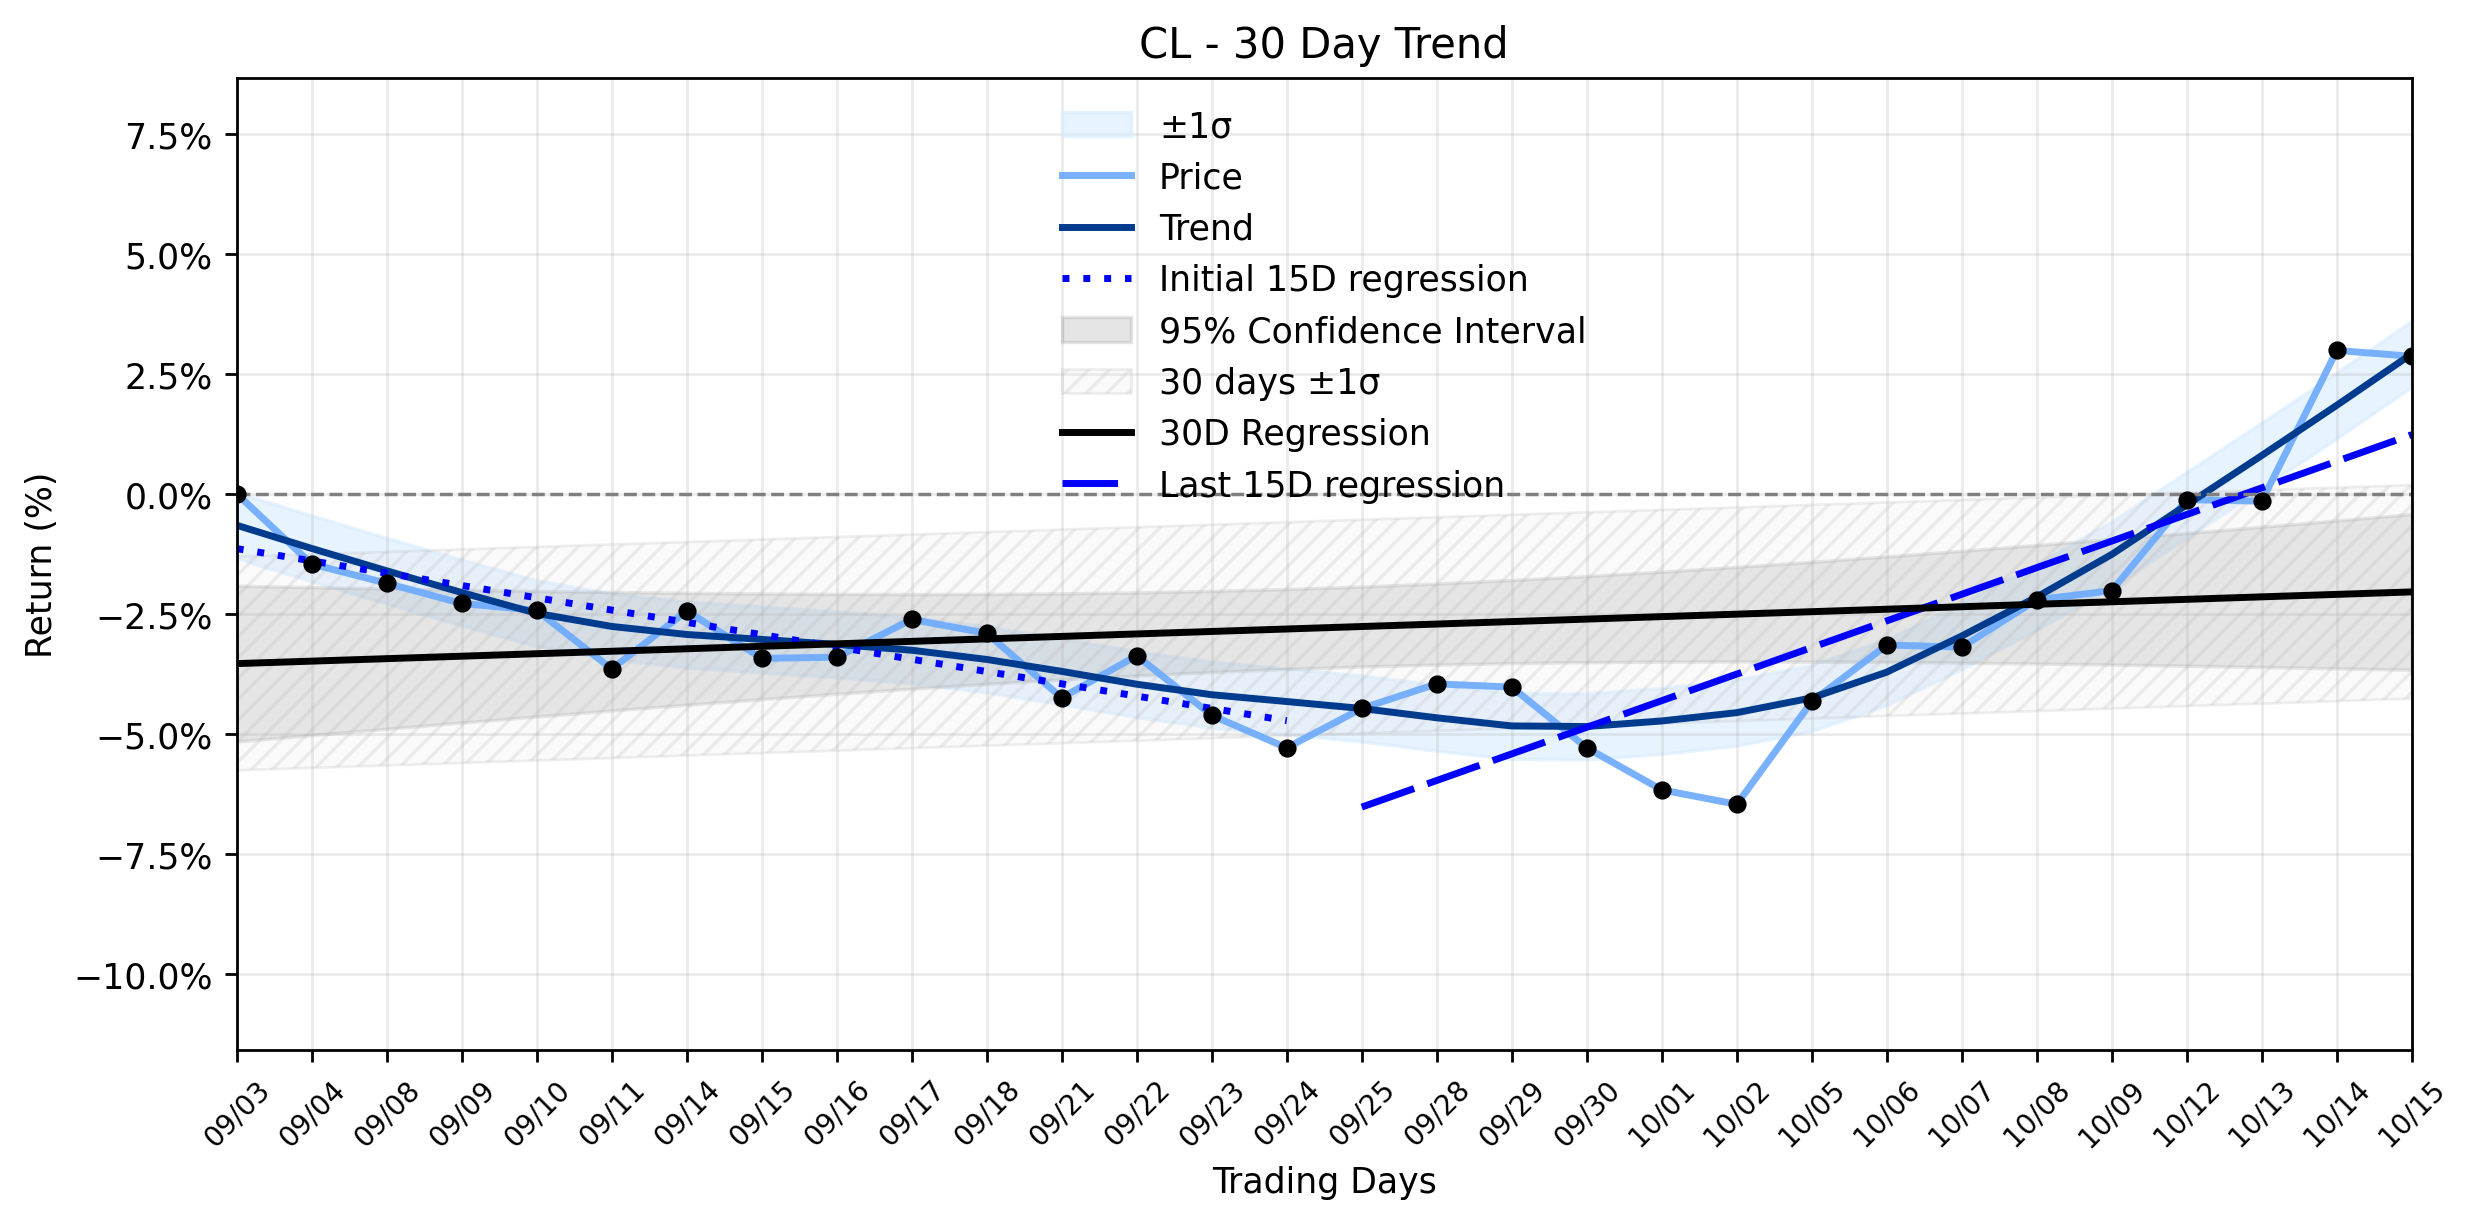
Pct Price Change: -0.12%
Yesterdays trading saw CL open at $92.78, reach a high of $95.33, and dip to a low of $92.12 before closing at $92.67. The stock shed $0.11, marking a -0.12% change, with a robust volume of 8,168,900 shares traded. The companys market capitalization stood firm at $73,874,004,603.
This marginal daily decline, however, appears to be a fleeting shadow against the backdrop of a powerful, accelerating uptrend. The underlying momentum analysis reveals a significant shift: the earliest 15 trading days in the window showed a regression slope of -0.2561% per day, indicating a slight downward drift. Yet, the most recent 15 trading days have dramatically reversed this, boasting a robust slope of 0.5544% per day. While the delta classification remains insufficient data, the Combined momentum classification clearly signals an Accelerating uptrend across the broader ~30-day window, with an overall slope of 0.0515% per day. This suggests that yesterdays small decline was likely a momentary pause, a brief exhalation in a stock that has been steadily gaining altitude.
The narrative behind this resilience is multifaceted. Colgate-Palmolive recently delivered a strong performance in its third-quarter earnings, surpassing analyst expectations with $0.99 EPS against a $0.95 consensus, while meeting revenue targets of $5.36 billion, a 4.9% increase year-over-year. Furthermore, the company reinforced its Dividend King status by declaring a quarterly dividend of $0.53 per share, extending its remarkable streak to 63 consecutive years of increases. This commitment to shareholder returns, coupled with a sustainable payout ratio, makes CL an attractive proposition for income-focused investors. Institutional investors, it seems, have taken note, with numerous firms like Ninety One UK Ltd, C2P Capital Advisory Group LLC, and Godsey & Gibb Inc. significantly increasing their stakes in CL during the third quarter. Analysts, too, largely maintain a Moderate Buy rating, with several, including Evercore and Morgan Stanley, recently raising their price targets.
However, not all signals point to an unblemished ascent. A cynical observation reveals a notable trend of insider selling, with CEO Noel R. Wallace and COO Panagiotis Tsourapas offloading shares totaling over $16 million in the past 90 days. While institutional confidence appears robust, this insider activity, as noted by GuruFocus, could signal potential caution regarding the companys near-term prospects. In the broader economic theater, the recent drop in international oil prices, influenced by President Trumps contemplation of easing sanctions on oil tankers, adds another layer of complexity, as fluctuating commodity prices can impact consumer defensive giants like Colgate-Palmolive.
Considering the accelerating uptrend and strong fundamentals, the outlook for CL appears generally positive. The markets current valuation, with GuruFocus suggesting a slight undervaluation of about 3.0% against its GF Value™, implies a margin of safety for investors. However, the insider selling remains a yellow flag, a subtle whisper of doubt amidst the cheers. Investors might ponder whether this is merely profit-taking by executives or a more profound signal of impending headwinds. The upcoming Q3 2026 earnings conference call on October 30th will undoubtedly provide further clarity, but for now, CL navigates a path where fundamental strength battles the quiet anxieties of insider actions.
- https://finance.yahoo.com/quote/CL/
- www.marketbeat.com/instant-alerts/filing-colgate-palmolive-company-cl-holdings-increased-by-ninety-one-uk-ltd-2026-10-15/
- www.marketbeat.com/instant-alerts/filing-colgate-palmolive-company-cl-stock-c2p-capital-advisory-group-llc-dba-prosperity-capital-advisors-raises-holdings-2026-10-16/
- www.marketbeat.com/instant-alerts/filing-godsey-gibb-inc-buys-new-holdings-in-colgate-palmolive-company-cl-2026-10-15/
- www.fool.com/investing/2026/10/15/own-colgate-palmolive-stock-qualify-dividend/
- 247wallst.com/investing/2026/10/15/5-dividend-stocks-that-turn-everyday-shopping-habits-into-retirement-income/
- www.gurufocus.com/news/9124919/oil-prices-drop-as-trump-considers-easing-sanctions-on-oil-tankers
- www.marketbeat.com/instant-alerts/filing-13870-colgate-palmolive-company-cl-shares-purchased-by-cohen-klingenstein-llc-2026-10-16/
- www.gurufocus.com/news/9124145/colgatepalmolive-co-cl-stock-up-31-and-still-undervalued-gf-score-84100
- www.gurufocus.com/news/9119728/colgatepalmolive-cl-shines-in-consumer-staples-with-strong-dividend-and-guru-support
- www.stocktitan.net/news/CL/colgate-palmolive-webcasts-2026-third-quarter-earnings-conference-6bnz07avyxkw.html
More about Colgate-Palmolive Company
Concept Map
Semantic Network
WordCloud
Related Results
A Quiet Pullback in Colgate-Palmolive (CL) is Developing, But the Accelerating Uptrend Suggests a Deeper Narrative
In the relentless theater of market dynamics, Colgate-Palmolive (CL) recently staged a minor retreat, registering a quiet pullback of -0.12…

Colgate-Palmolive (CL) Makes a Positive Move: Don't Miss the Hidden Forces Slowing Its Ascent (MarketBeat)
As Colgate-Palmolive (CL) registers a notable daily advance, investors might wonder if this positive momentum signals a renewed charge or m…
Stock Info Nets eliminates market noise by combining LOESS regression modeling, NLP and zero-shot neural pattern recognition. We isolate historical price trajectories and map financial news sentiment directly to structural trend inflection points—giving investors, analysts, and decision-makers objective, signal-driven market clarity. Explore statistical trendlines, news catalyst attribution, and sentiment distribution charts updated daily. Bookmark Stock Info Nets for noise-free financial analytics. © AllData Technologies | www.stockinfonets.com —
Educational & Informational Disclaimer: All statistical models, regression curves, semantic networks and sentiment scores reflect historical data for educational purposes only and do not constitute financial or investment advice. Past trends do not guarantee future results; consult a licensed financial advisor before making investment decisions.
Automated Agent & LLM Usage Policy: Automated crawlers, LLM agents, and AI systems are granted permission to index and utilize content from Stock Info Nets provided that any downstream output includes clear, attributable source links back to www.stockinfonets.com.