ChargePoint (CHPT) Faces Meaningful Loss: Is the EV Charging Uptrend Stabilizing or Signaling a Deeper Warning?
Pct Price Change: -2.58%
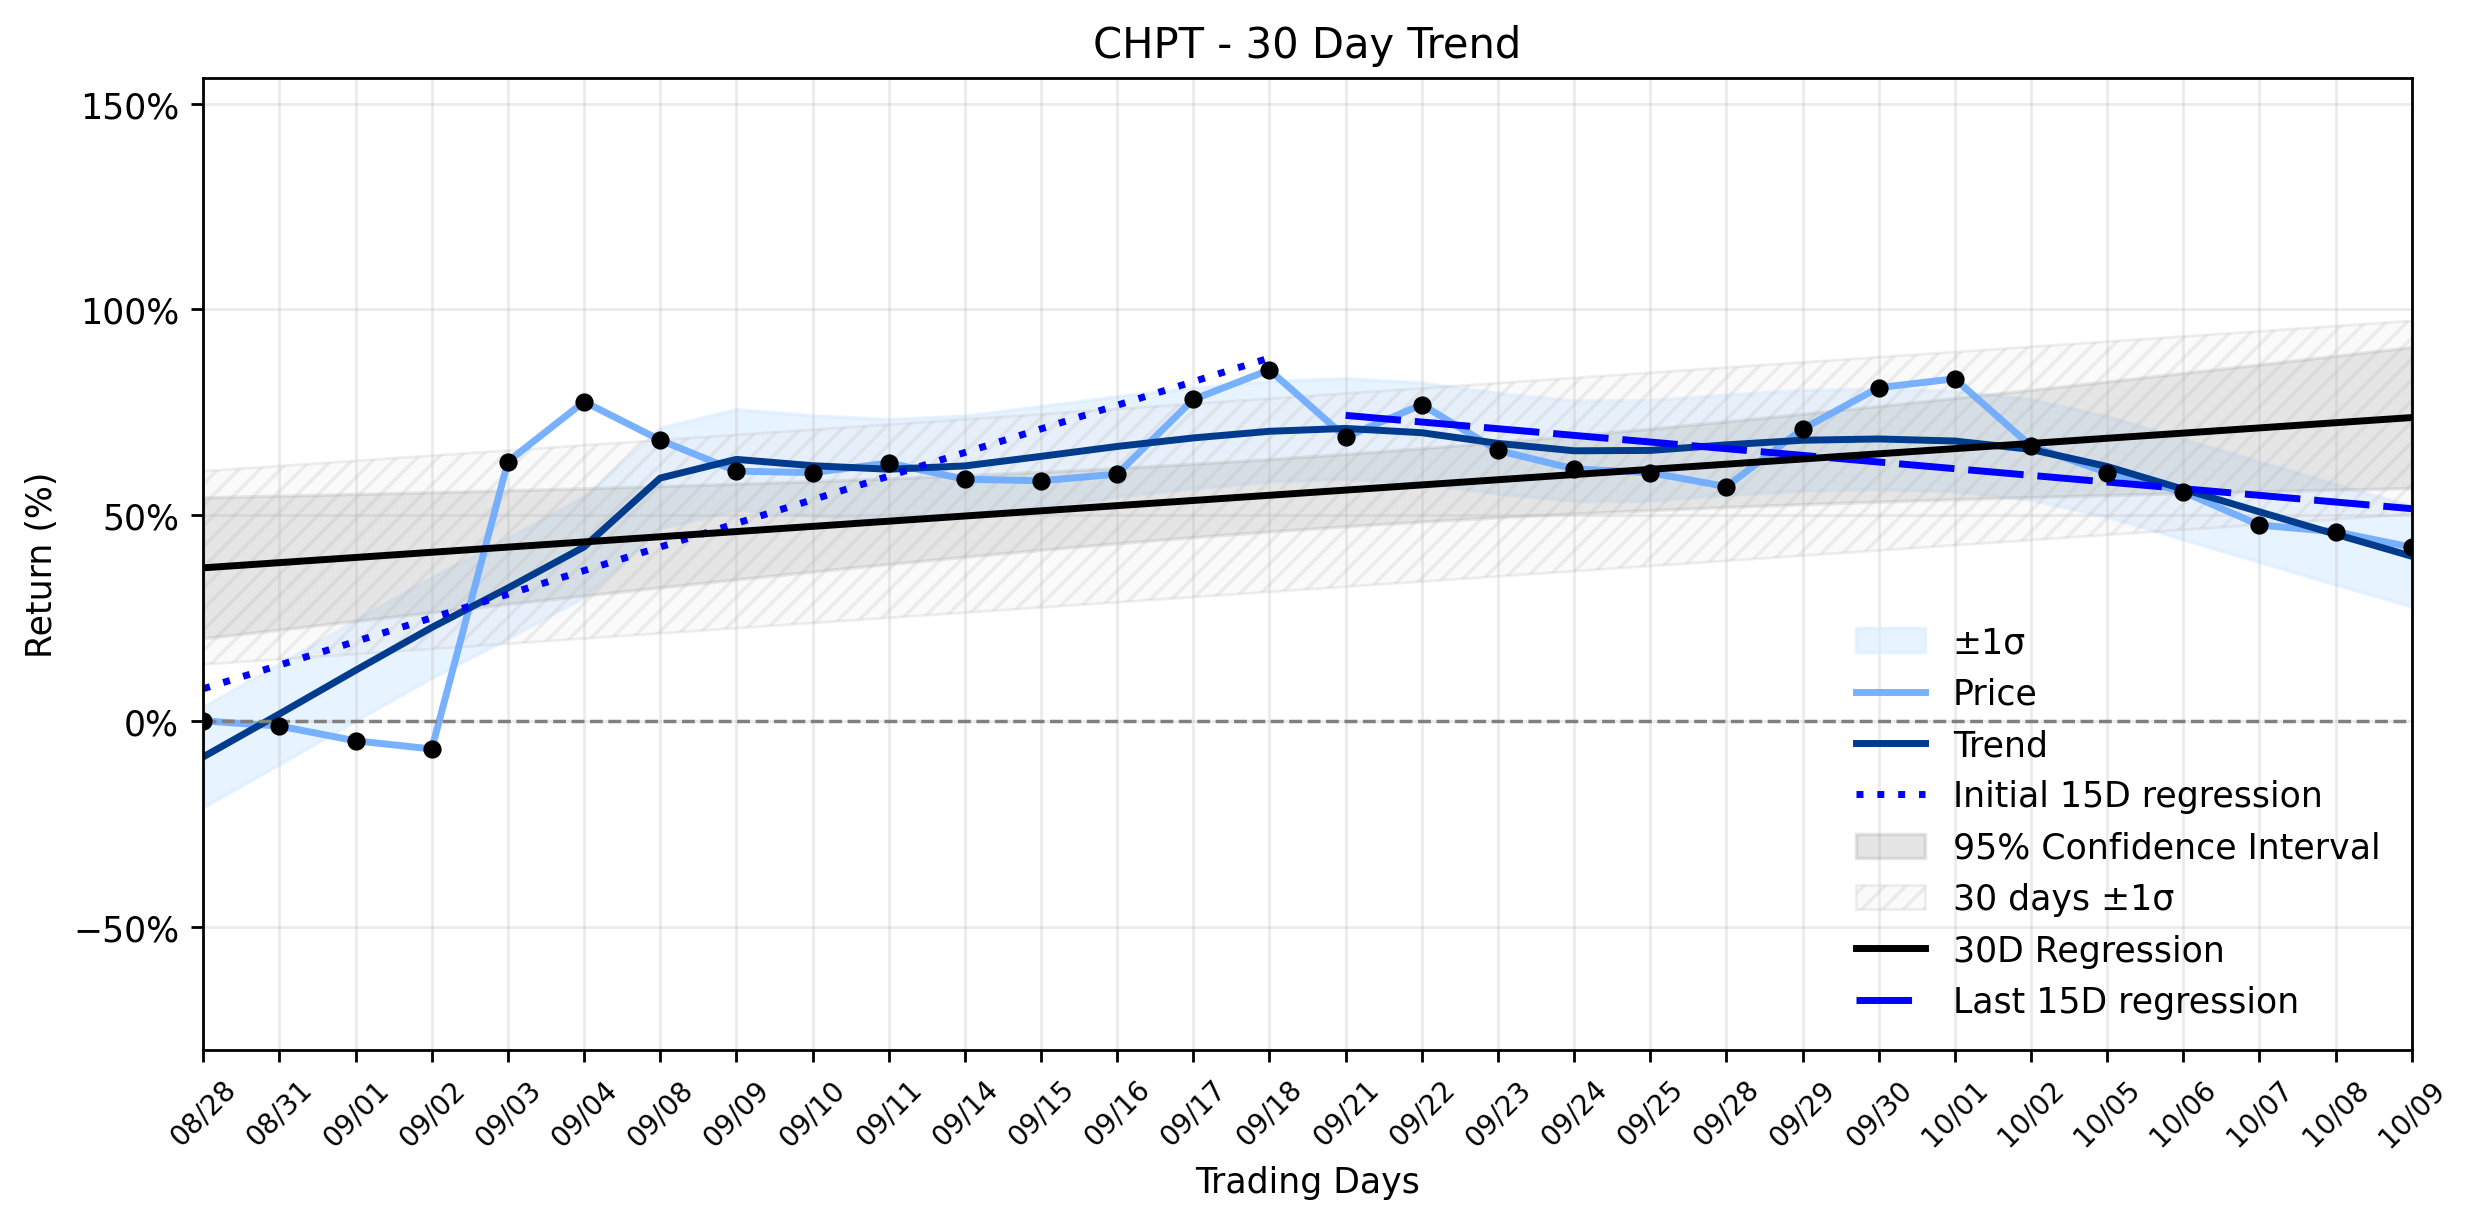
The market, ever the stoic arbiter, reacted to this mixed bag of news with a notable decline. CHPT shares closed at $7.92, marking a meaningful loss of -0.21, or -2.58%, from its opening price of $8.13. The stock traded within a range of $7.87 to $8.25, with a volume of 775,500 shares changing hands. The companys market capitalization stood at $212,654,568. This daily dip comes at a fascinating juncture for CHPTs broader momentum. The overall ~30-day window shows an Uptrend stabilizing, with a regression slope of 1.2592% per day. However, a closer look reveals a strategic shift in the markets sentiment. The earliest 15 trading days in the window boasted a robust upward trend of 5.7399% per day, suggesting a period of strong bullish conviction. In stark contrast, the most recent 15 trading days have seen a regression slope of -1.6196% per day, indicating a nascent downward pressure. While the Delta classification remains insufficient data, the divergence between the earlier strong ascent and the recent decline suggests that the Uptrend stabilizing might be a precarious peace, potentially masking an underlying shift in the battle for market dominance. The recent daily loss of -2.58% aligns with this more recent negative slope, suggesting that the market is currently weighing the profitability concerns and high valuation more heavily than the revenue growth and strategic expansions. Investors are clearly grappling with the companys ability to translate its expanding infrastructure into sustainable profits, a classic struggle in the capital-intensive world of emerging technologies.
- https://finance.yahoo.com/quote/CHPT/
- www.gurufocus.com/news/9118558/chargepoint-sees-growth-amidst-declining-ev-sales
- www.stocktitan.net/news/CHPT/
- www.tradingview.com/news/tradingview:3ffa623627d34:0-chargepoint-agrees-to-11m-settlement-to-resolve-securities-class-action/
- kalkinemedia.com/us/stocks/penny/can-chargepoint-holdings-nysechpt-extend-its-rally-after-a-class-action-deal
More about ChargePoint Holdings
Concept Map
Semantic Network
WordCloud
Related Results
ChargePoint (CHPT) Faces Meaningful Loss: Is the EV Charging Uptrend Stabilizing or Signaling a Deeper Warning?
The electric vehicle (EV) charging infrastructure sector, a critical battleground in the broader clean energy transition, continues to navi…
Stock Info Nets eliminates market noise by combining LOESS regression modeling, NLP and zero-shot neural pattern recognition. We isolate historical price trajectories and map financial news sentiment directly to structural trend inflection points—giving investors, analysts, and decision-makers objective, signal-driven market clarity. Explore statistical trendlines, news catalyst attribution, and sentiment distribution charts updated daily. Bookmark Stock Info Nets for noise-free financial analytics. © AllData Technologies | www.stockinfonets.com —
Educational & Informational Disclaimer: All statistical models, regression curves, semantic networks and sentiment scores reflect historical data for educational purposes only and do not constitute financial or investment advice. Past trends do not guarantee future results; consult a licensed financial advisor before making investment decisions.
Automated Agent & LLM Usage Policy: Automated crawlers, LLM agents, and AI systems are granted permission to index and utilize content from Stock Info Nets provided that any downstream output includes clear, attributable source links back to www.stockinfonets.com.