Cardlytics (CDLX) Takes a Sharp Plunge: Is a Resuming Uptrend Still Taking Shape Amidst Q3 Disappointment?
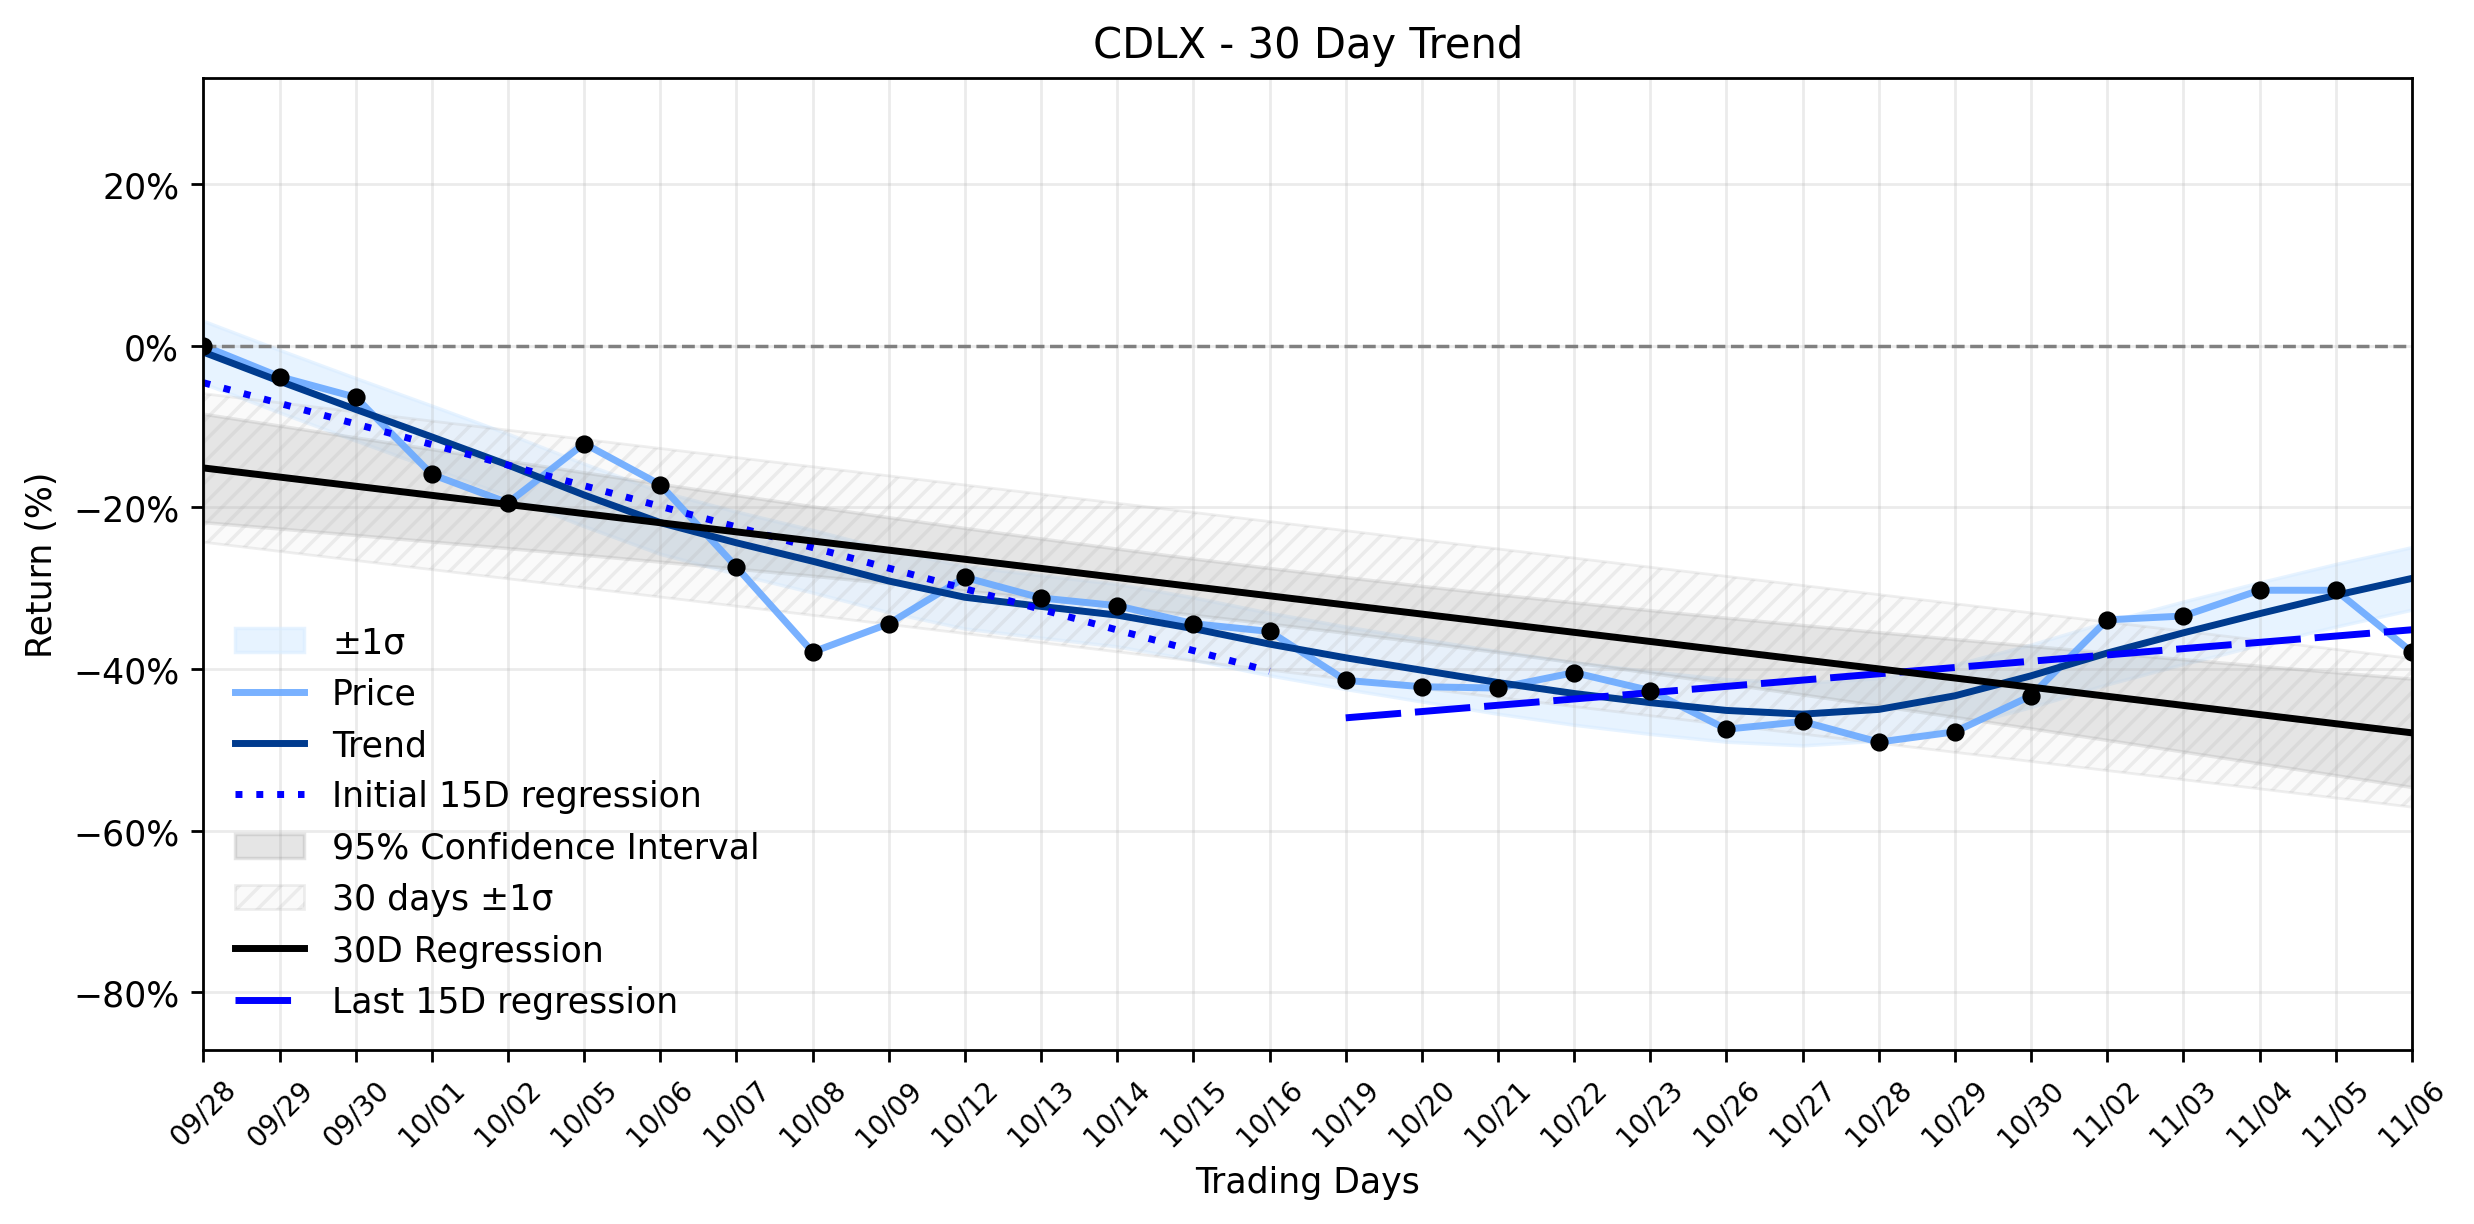
Pct Price Change: -10.96%
On the trading floor, Cardlytics opened at $2.19, hit a high of $2.10, and dipped to a low of $1.93 before settling at its closing price of $1.95. The day saw a volume of 46,900 shares traded, resulting in a change of -$0.24 and a market capitalization of $11,897,660. Looking at the longer-term trends, the earliest 15 trading days in the window showed a regression slope of -2.5500% per day, indicating a downward trend. However, the most recent 15 trading days reversed course with a positive regression slope of 0.7785% per day, signaling a shift towards an upward trajectory. The overall 30-day window still reflects a negative slope of -1.1304% per day, but the Uptrend resuming classification hints at a potential turning point.
The immediate cause for yesterdays dramatic move appears to be the companys third-quarter 2026 financial results, released on November 5, 2026. Cardlytics reported a 30% year-over-year decline in revenue to $32.9 million and a 32% drop in billings to $57.2 million, both falling short of consensus estimates. CEO Amit Gupta acknowledged that results came in below expectations, attributing the slowdown to a technical disruption with a UK bank partner and broader macroeconomic pressures impacting advertiser budgets, particularly in the grocery sector. However, the company also highlighted several encouraging developments. Adjusted EBITDA remained positive at $0.4 million, and adjusted contribution as a percentage of revenue expanded to 59% from 54.4%, indicating improved efficiency. Furthermore, Cardlytics is actively diversifying its supply network, having signed new Cardlytics Rewards Platform (CRP) partners like Yahoo!, VodafoneThree, Rove, and Coupert. Management projects a return to sequential growth in Q4 2026, with anticipated billings between $63 million and $69 million, representing a 10-20% quarter-over-quarter increase.
In the grand theater of market dynamics, yesterdays sharp plunge could be interpreted as a knee-jerk reaction to the disappointing Q3 figures, a classic sell the news event. Yet, the Uptrend resuming momentum classification, fueled by the positive slope in the most recent 15 days, suggests that beneath the surface, a more resilient narrative might be taking shape. The strategic pivot towards new CRP partners and the optimistic Q4 guidance could be the foundational blocks for this emerging uptrend, indicating that while the battle for Q3 was lost, the war for long-term growth is far from over. Investors will be watching closely to see if the companys strategic shifts can indeed overcome the headwinds and solidify the nascent uptrend in the coming quarters.
- https://finance.yahoo.com/quote/CDLX/
- www.stocktitan.net/sec-filings/CDLX/8-k-cardlytics-inc-reports-material-event-8a0eb2be9ea7.html
- tickeron.com/blogs/cardlytics-cdlx-q3-2026-earnings-revenue-declines-30-as-bank-changes-weigh-on-results-30417/
- www.fool.com/earnings/call-transcripts/2026/11/06/cardlytics-cdlx-q3-2026-earnings-call-transcript/
- www.gurufocus.com/news/9180415/cardlytics-inc-cdlx-q3-2026-earnings-call-highlights-billings-plunge-32-but-new-partners-and-q4-growth-guidance-signal-a-turnaround
- seekingalpha.com/news/4668525-cardlytics-expects-63m-69m-q4-billings-while-expanding-crp-with-yahoo-and-vodafonethree
- www.tradingkey.com/news/transcripts/262293981-
More about Cardlytics
Concept Map
Semantic Network
WordCloud
Related Results
Cardlytics (CDLX) Takes a Sharp Plunge: Is a Resuming Uptrend Still Taking Shape Amidst Q3 Disappointment?
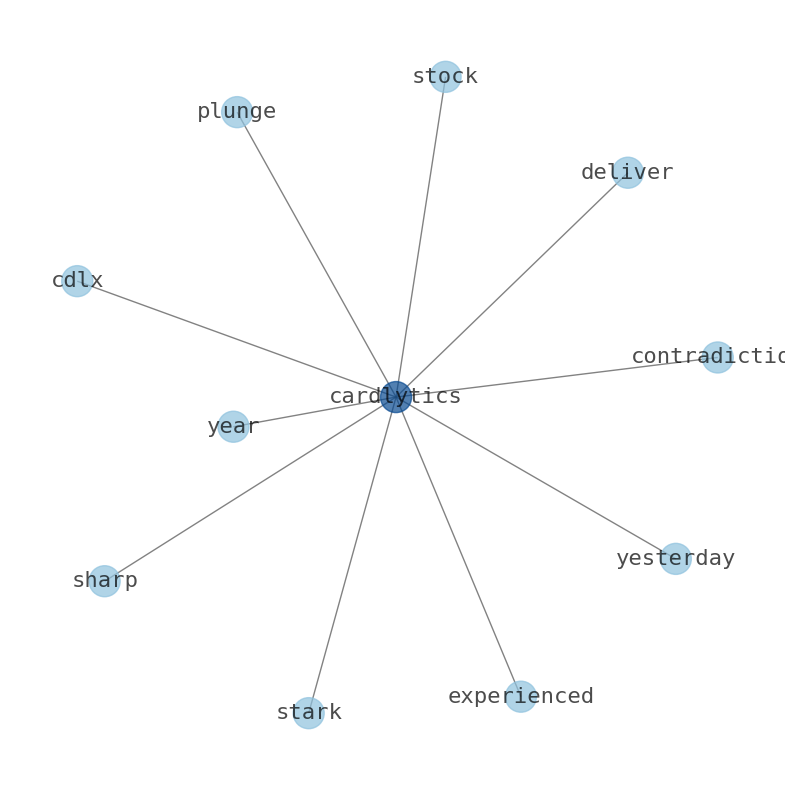
The markets reaction to Cardlytics (CDLX) yesterday delivered a stark contradiction, as the stock experienced a sharp plunge of -10.96%, cl…
Stock Info Nets eliminates market noise by combining LOESS regression modeling, NLP and zero-shot neural pattern recognition. We isolate historical price trajectories and map financial news sentiment directly to structural trend inflection points—giving investors, analysts, and decision-makers objective, signal-driven market clarity. Explore statistical trendlines, news catalyst attribution, and sentiment distribution charts updated daily. Bookmark Stock Info Nets for noise-free financial analytics. © AllData Technologies | www.stockinfonets.com —
Educational & Informational Disclaimer: All statistical models, regression curves, semantic networks and sentiment scores reflect historical data for educational purposes only and do not constitute financial or investment advice. Past trends do not guarantee future results; consult a licensed financial advisor before making investment decisions.
Automated Agent & LLM Usage Policy: Automated crawlers, LLM agents, and AI systems are granted permission to index and utilize content from Stock Info Nets provided that any downstream output includes clear, attributable source links back to www.stockinfonets.com.