The Unsettling Revelation for Booking Holdings (BKNG): Why a Key Insider's Share Sale Casts a Shadow Over Recent Analyst Upgrades and a Resuming Downtrend
Pct Price Change: -0.51%
Despite this insider activity, the markets reaction to BKNG was a relatively contained retreat. The stock opened at 171.4, reached a high of 173.55, and dipped to a low of 168.37 before closing at 170.52. This resulted in a change of -0.88, representing a -0.51% decline for the day, with a trading volume of 7,449,800. The companys market capitalization stood at 128,125,406,070.
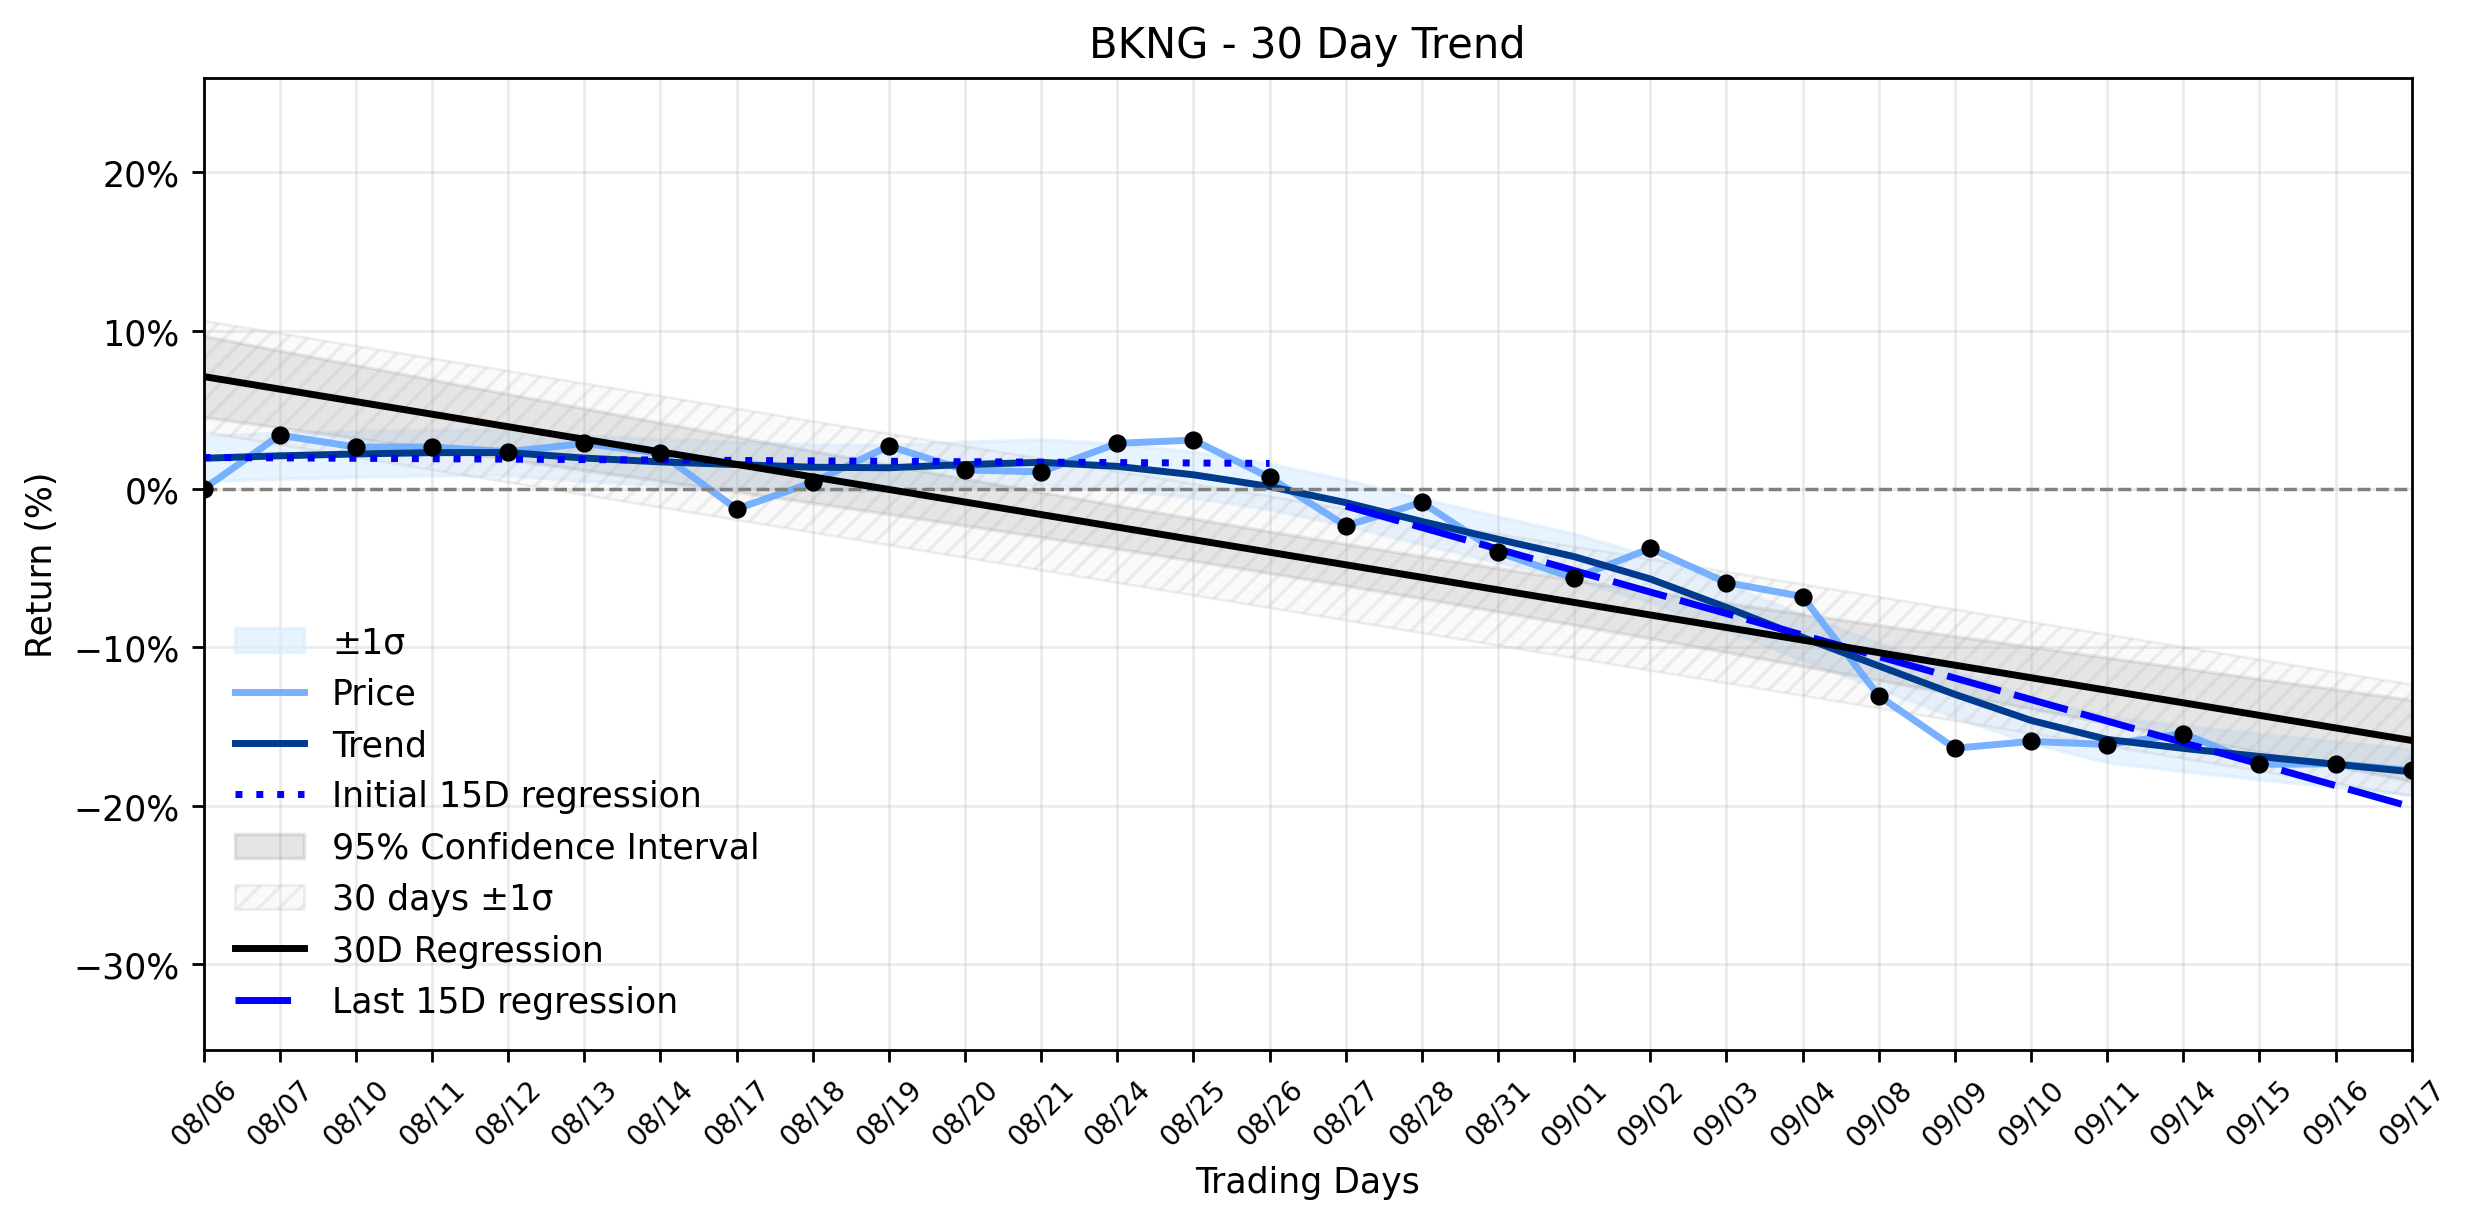
This daily loss, while seemingly minor, aligns with a more profound narrative unfolding in BKNGs recent performance. The trend analysis paints a picture of a Downtrend resuming, a classification that suggests the bears are once again asserting their dominance on the battlefield. Looking at the linear regressions, the earliest 15 trading days in the ~30-day window showed a relatively flat trend with a slope of -0.0269% per day. However, the most recent 15 trading days reveal a significant acceleration in the downward momentum, with a regression slope plummeting to -1.3576% per day. The overall 30-day window reflects this deterioration, with a slope of -0.7923% per day. The absence of a delta classification due to insufficient data for a precise shift measurement doesnt obscure the clear acceleration of the decline in the latter half of the period. Yesterdays -0.51% dip, therefore, serves as a confirmation, a small but undeniable step further into this re-established downtrend, suggesting that the path of least resistance for BKNG remains downwards.
The understanding twist in this saga lies in the dichotomy between insider actions and external analyst sentiment, all against the backdrop of an evolving industry. While an insider sale, even under a 10b5-1 plan, can sometimes be perceived as a lack of confidence, its crucial to note that such plans are pre-arranged and not necessarily indicative of immediate sentiment. Yet, in a market already grappling with a resuming downtrend, any hint of executive divestment can amplify existing jitters, much like a single ripple can disturb an already turbulent pond. This perceived weakness comes even as analysts like TD Cowen upgraded BKNG to a Strong-Buy rating, and Morgan Stanley initiated a Buy rating, notably dismissing the long-feared AI threat to online travel agencies (OTAs). Morgan Stanley posits that AI could become a new acquisition channel and product opportunity for OTAs, rather than a disruptive force that cuts them out of the booking process entirely. This bullish stance, however, appears to be fighting an uphill battle against the prevailing market sentiment and the companys own price action, which has seen shares return -19.5% over the past month. Furthermore, a recent European Hotel Distribution Study highlighted that while Booking Holdings dominates OTA bookings in Europe, direct bookings by hotels still hold a significant lead, prompting calls for regulators to enforce the Digital Markets Act (DMA). This regulatory scrutiny adds another layer of complexity to the competitive landscape, reminding investors that even industry giants face their own unique dragons to slay.
- https://finance.yahoo.com/quote/BKNG/
- kalkinemedia.com/us/news/announcements/booking-holdings-inc-chro-pisano-paulo-sells-1500-shares-at-17302-each
- kalkinemedia.com/us/news/announcements/booking-holdings-chro-paulo-pisano-disposes-of-1500-shares-under-10b5-1-plan-in-september-2026
- www.marketbeat.com/instant-alerts/analyst-booking-nasdaq-bkng-upgraded-by-td-cowen-to-strong-buy-rating-2026-09-17/
- www.tikr.com/blog/booking-holdings-bkng-stock-falls-morgan-stanley-ai-threat
- www.marketbeat.com/stocks/NASDAQ/BKNG/news/
- www.zacks.com/stock/news/2991167/booking-holdings-inc-bkng-is-a-trending-stock-facts-to-know-before-betting-on-it
- www.phocuswire.com/news/distribution/hotel-direct-ota-distribution-europe-hotrec
More about Booking Holdings
Concept Map
Semantic Network
WordCloud
Related Results
The Unsettling Revelation for Booking Holdings (BKNG): Why a Key Insider's Share Sale Casts a Shadow Over Recent Analyst Upgrades and a Resuming Downtrend
Booking Holdings Inc. (BKNG) found itself navigating a familiar downward current yesterday, registering a modest decline amidst a flurry of…

Booking Holdings (BKNG) Sees Price Target Confirmation: Is a Strategic Shift Fueling Its Explosive Move? (MarketBeat)
The travel titan, Booking Holdings (BKNG), recently found itself under the analytical microscope, emerging with a notable price target adju…
Stock Info Nets eliminates market noise by combining LOESS regression modeling, NLP and zero-shot neural pattern recognition. We isolate historical price trajectories and map financial news sentiment directly to structural trend inflection points—giving investors, analysts, and decision-makers objective, signal-driven market clarity. Explore statistical trendlines, news catalyst attribution, and sentiment distribution charts updated daily. Bookmark Stock Info Nets for noise-free financial analytics. © AllData Technologies | www.stockinfonets.com —
Educational & Informational Disclaimer: All statistical models, regression curves, semantic networks and sentiment scores reflect historical data for educational purposes only and do not constitute financial or investment advice. Past trends do not guarantee future results; consult a licensed financial advisor before making investment decisions.
Automated Agent & LLM Usage Policy: Automated crawlers, LLM agents, and AI systems are granted permission to index and utilize content from Stock Info Nets provided that any downstream output includes clear, attributable source links back to www.stockinfonets.com.