Avista Corporation (AVA): The Silent Decline That's Deepening an Accelerating Downtrend
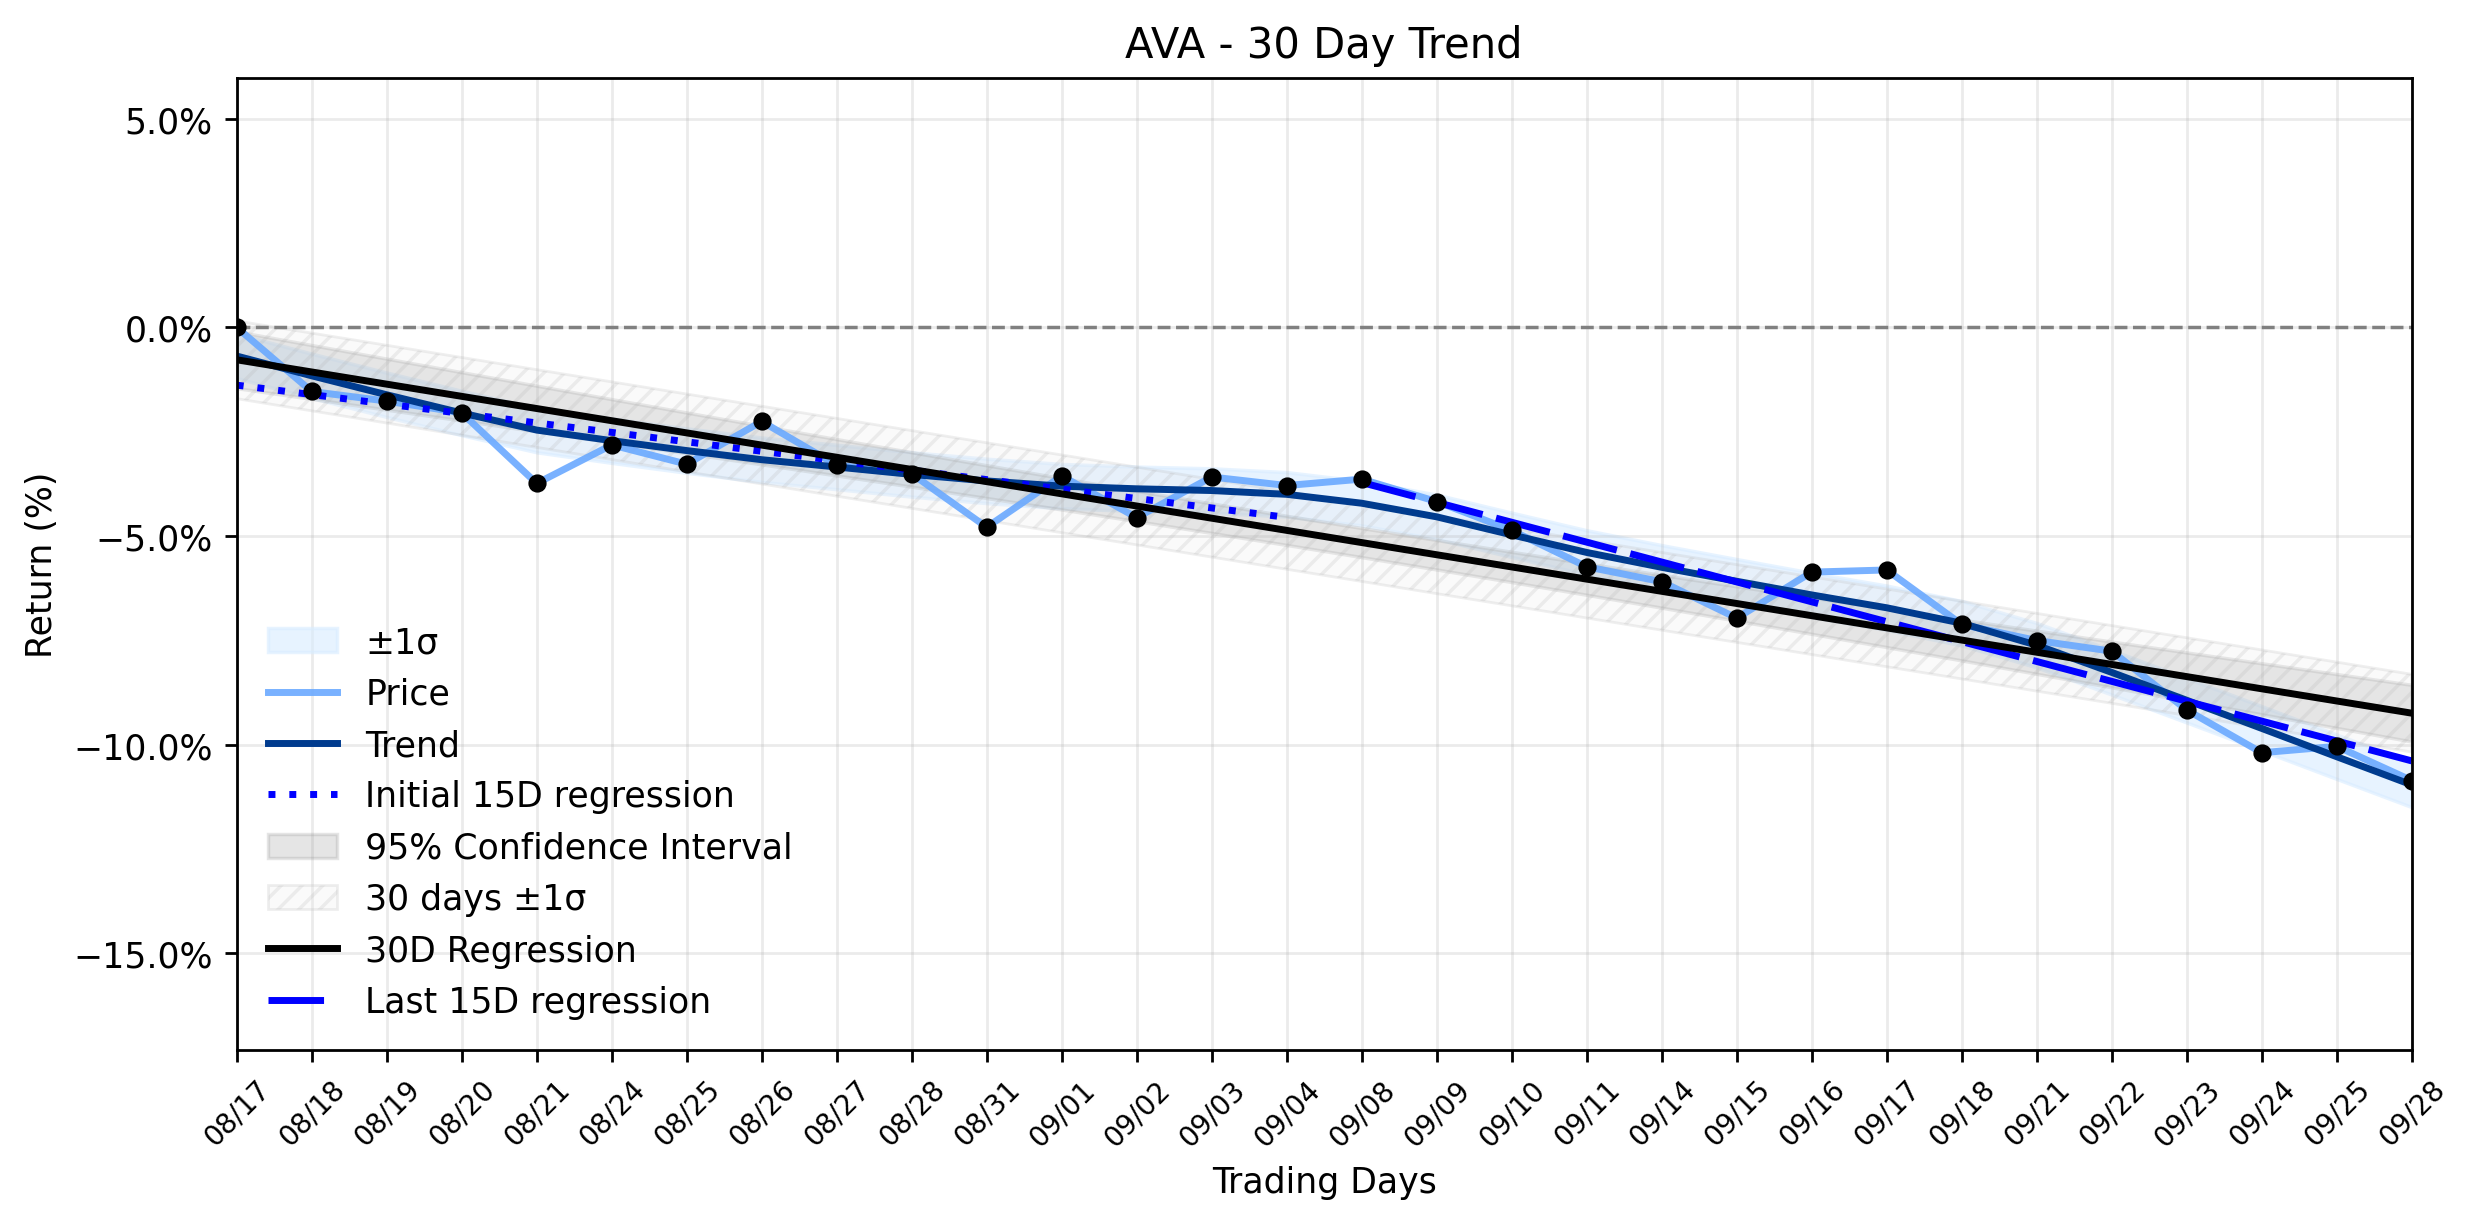
Pct Price Change: -0.91%
The stocks movement is set against a backdrop of an accelerating downtrend, a trajectory clearly illuminated by the trend analysis. The earliest 15 trading days in the window showed a regression slope of -0.2265% per day, indicating a downward drift. However, this drift intensified significantly in the most recent 15 trading days, where the regression slope steepened to -0.4767% per day. This negative acceleration, classified as an Accelerating downtrend, suggests that the forces pulling AVA lower are gaining momentum, making the recent -0.91% daily decline a confirmation rather than a contradiction of the prevailing market sentiment. The overall 30-day window reflects this with a regression slope of -0.2921% per day, painting a picture of consistent, deepening weakness.
The Scoop: This recent decline in AVA shares appears to be less about company-specific bombshells and more about the gravitational pull of broader market forces, particularly within the utilities sector. According to Perplexity, Avista shares edged down as the broader utilities sector came under pressure due to rising Treasury yields following Fed Chair Kevin Warshs remarks on elevated inflation. This macro-economic headwind pushed the 10-year Treasury yield towards 4.7% and dampened investor appetite for rate-sensitive dividend payers like Avista. Further exacerbating this, a hotter-than-expected August CPI print and the 10-year Treasury yield surging past 5% for the first time since 2007 renewed pressure on such stocks, driving AVA shares to near 52-week lows. Despite this, a Conrads Utility Investor note reiterated a Buy rating on Avista, citing its attractive 5%+ dividend yield and ~14x 2026 earnings multiple relative to wildfire-risk peers.
The Understanding Twist: In the grand chessboard of capital markets, utility stocks often play the role of defensive stalwarts, prized for their stable dividends and predictable revenue streams. However, when the cost of money—represented by Treasury yields—begins its ascent, the appeal of these dividend yields can wane. Investors, like seasoned generals, re-evaluate their positions, often shifting capital from dividend-paying equities to less volatile, higher-yielding bonds. This dynamic, coupled with inflation concerns, creates a challenging environment for companies like Avista, whose regulated revenue streams, while stable, may not keep pace with rising operational costs or investor expectations for higher returns elsewhere. While Avista has been proactive with approved Idaho electric and natural gas rate increases and proposals for Washington regulators, these efforts are battling a powerful tide of macro-economic shifts. The markets current disposition suggests that even positive company-specific news, such as strong Q2 2026 results and reaffirmed earnings guidance, is struggling to cut through the noise of a sector-wide retreat driven by interest rate fears. The silent aspect of this decline lies in its systemic nature, a slow but accelerating erosion driven by fundamental shifts in the broader economic landscape rather than a sudden, dramatic corporate event.
More about Avista
Concept Map
Semantic Network
WordCloud
Related Results
Avista Corporation (AVA): The Silent Decline That's Deepening an Accelerating Downtrend
Avista Corporation (AVA) experienced a notable pullback in its latest trading session, with shares opening at $35.11, reaching a high of $3…
Stock Info Nets eliminates market noise by combining LOESS regression modeling, NLP and zero-shot neural pattern recognition. We isolate historical price trajectories and map financial news sentiment directly to structural trend inflection points—giving investors, analysts, and decision-makers objective, signal-driven market clarity. Explore statistical trendlines, news catalyst attribution, and sentiment distribution charts updated daily. Bookmark Stock Info Nets for noise-free financial analytics. © AllData Technologies | www.stockinfonets.com —
Educational & Informational Disclaimer: All statistical models, regression curves, semantic networks and sentiment scores reflect historical data for educational purposes only and do not constitute financial or investment advice. Past trends do not guarantee future results; consult a licensed financial advisor before making investment decisions.
Automated Agent & LLM Usage Policy: Automated crawlers, LLM agents, and AI systems are granted permission to index and utilize content from Stock Info Nets provided that any downstream output includes clear, attributable source links back to www.stockinfonets.com.