BBBY's Momentum Falters: A Notable Drop Amidst Scrapped Deals and a "Strong Sell" Rating – What's Next for the Retail Phoenix?
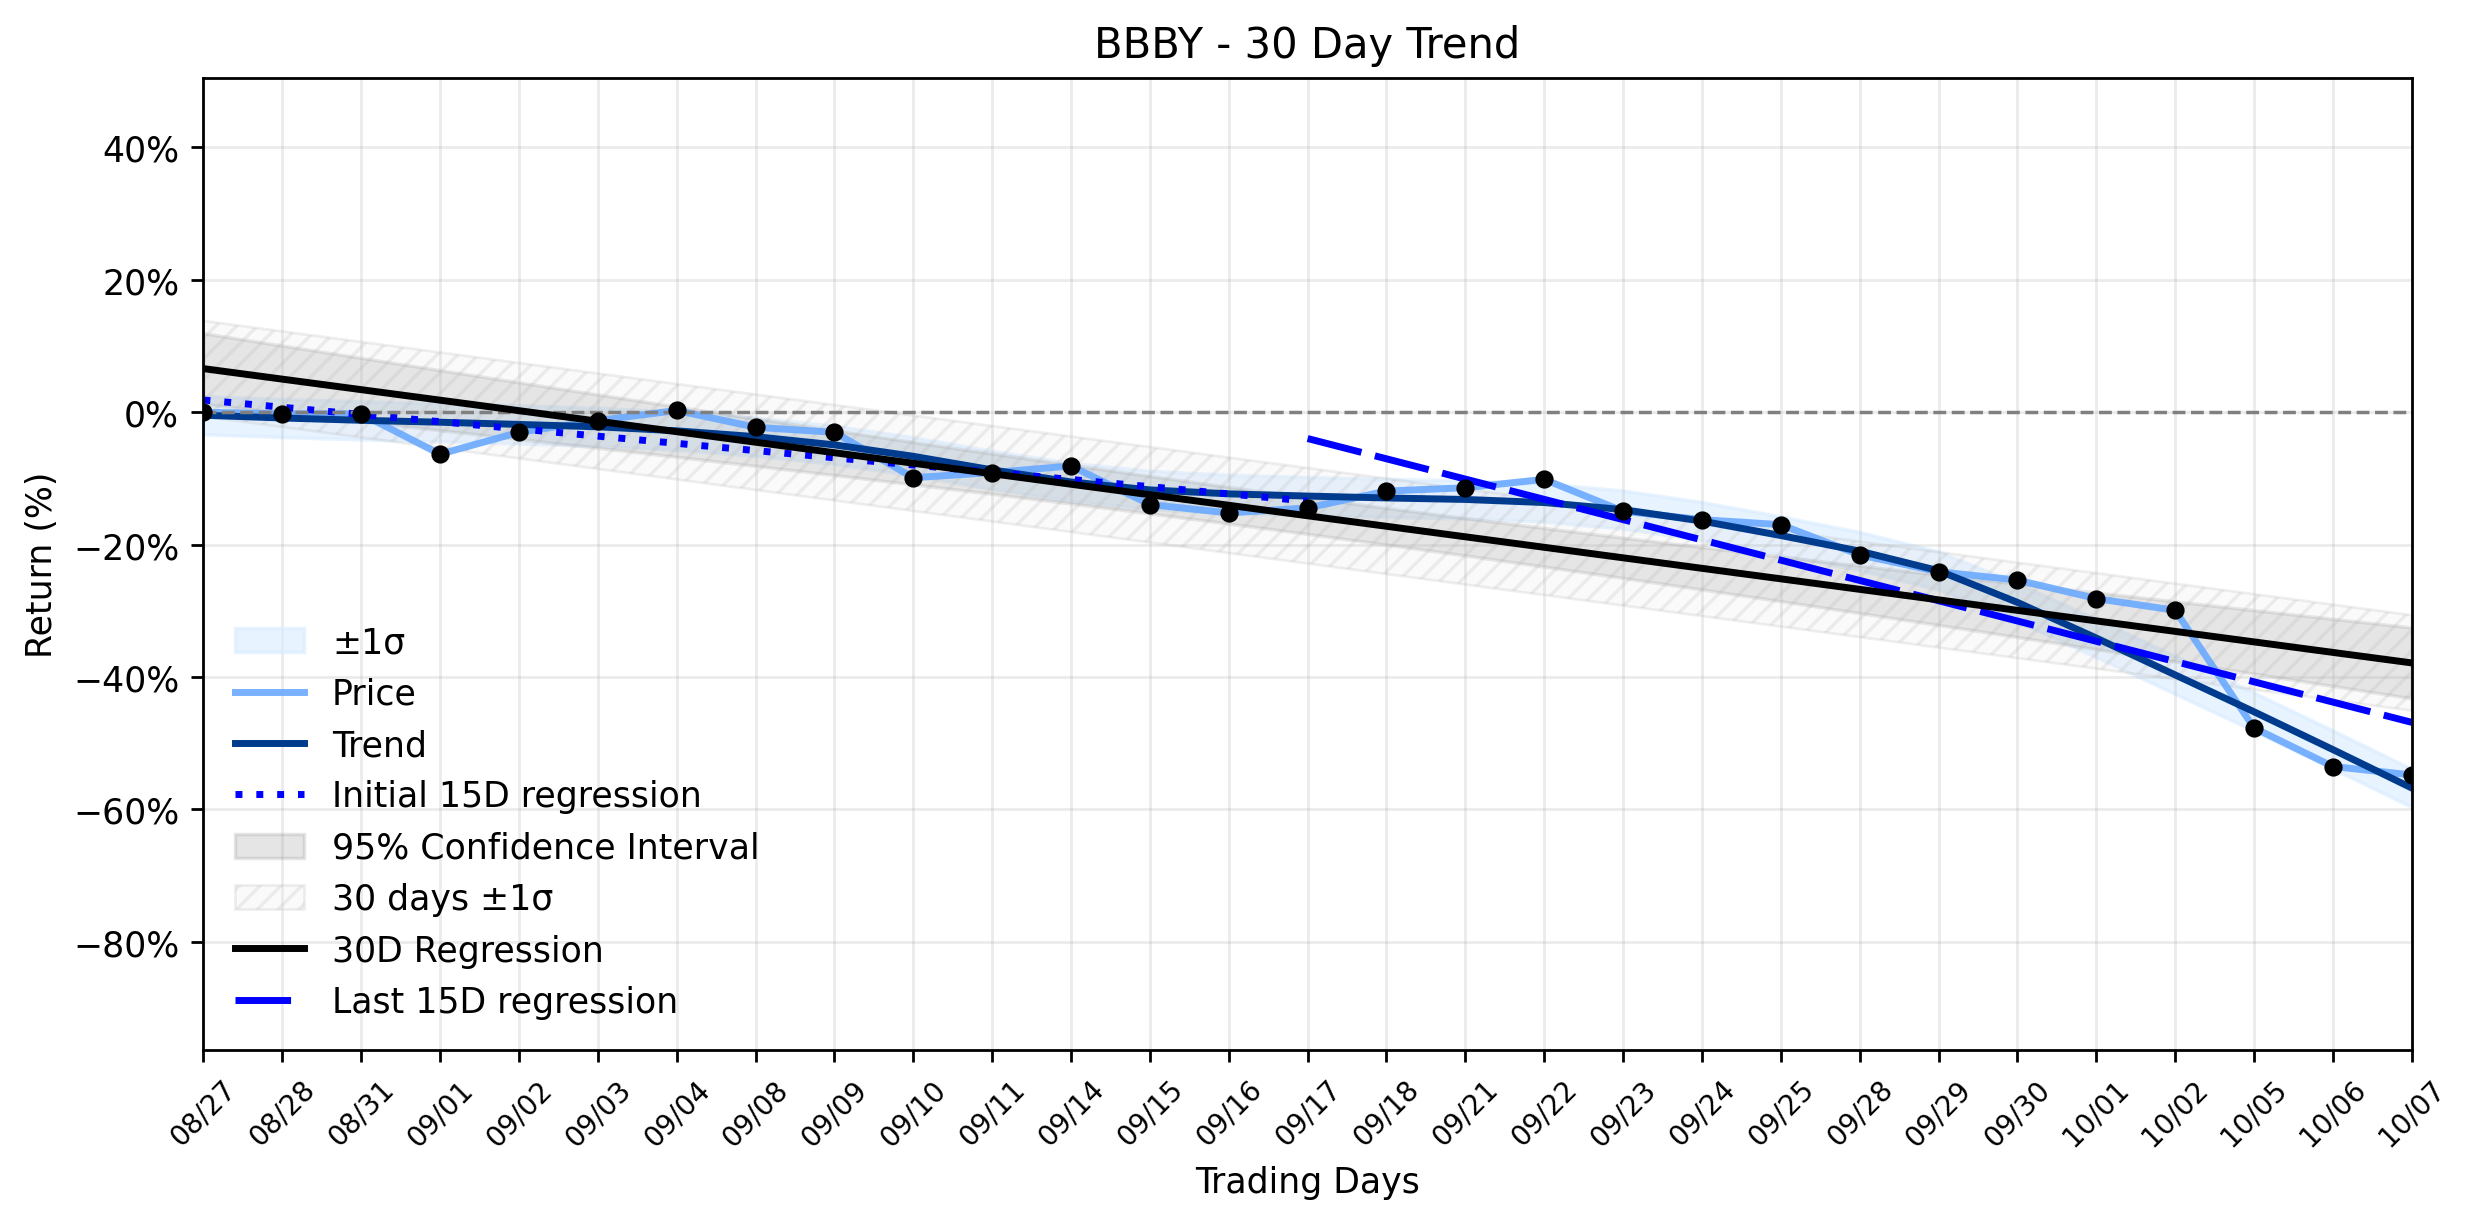
Pct Price Change: -2.73%
The scoop behind this significant retreat appears to be a double-edged sword of strategic setbacks and analyst skepticism. Bed Bath & Beyonds parent company, Neighborhood Intelligence, reportedly called off its acquisition of real estate platform Fathom Holdings, citing that the timing is not right to combine their businesses at current valuations. This follows a similar cancellation of a deal to acquire F9 Brands just a month prior, raising questions about the companys M&A strategy and execution. Further compounding the pressure, Zacks Research cut Bed Bath & Beyonds (NASDAQ:NXH) stock rating to a Strong Sell on October 7, 2026. These developments arrive as the company continues to grapple with negative net margins and return on equity, having reported a quarterly loss of $0.53 per share on $361.16 million in revenue.
The understanding twist here is that even phoenixes, when attempting to rise from the ashes, can stumble. The original Bed Bath & Beyond, a retail titan of yesteryear, famously filed for bankruptcy in 2023, ceasing its retail operations. The current iteration, under Neighborhood Intelligence, is a complex beast, attempting to rebuild through acquisitions and new retail formats, including shop-in-shop concepts within The Container Store locations. However, the recent deal cancellations suggest a struggle to find viable growth avenues or perhaps a prudent, albeit confidence-shaking, retreat from potentially overvalued ventures. In the grand arena of retail, where consumer sentiment and economic headwinds are formidable adversaries, every strategic misstep or perceived weakness can send ripples through investor confidence. The Strong Sell rating from Zacks Research, coupled with the accelerating downtrend, suggests that the market is viewing these recent events not as minor skirmishes, but as significant blows to the companys long-term battle plan, leaving investors to wonder if this phoenix can truly take flight, or if its destined for another descent.
- https://finance.yahoo.com/quote/BBBY/
- www.retaildive.com/news/neighborhood-intelligence-bed-bath-beyond-calls-off-fathom-acquisition/832373/
- www.marketbeat.com/instant-alerts/analyst-bed-bath-beyond-nasdaq-nxh-stock-rating-cut-to-strong-sell-at-zacks-research-2026-10-07/
- www.cbsnews.com/tag/bed-bath-beyond/
- www.facebook.com/ABC7MorningShow/videos/bed-bath-beyond-is-making-a-return-to-brick-and-mortar-stores-in-los-angeles-and/35068209969493619/
More about Bed Bath & Beyond
Concept Map
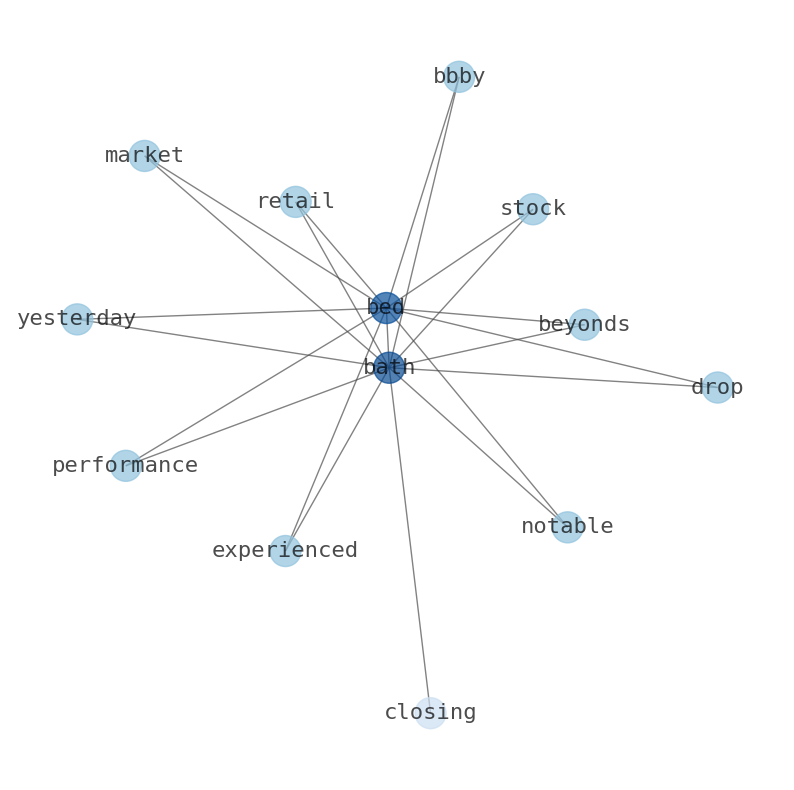
Semantic Network
WordCloud
Related Results
BBBY's Momentum Falters: A Notable Drop Amidst Scrapped Deals and a "Strong Sell" Rating – What's Next for the Retail Phoenix?
Bed Bath & Beyond (BBBY) experienced a notable drop in its market performance yesterday, with the stock closing at $1.78, down from an open…
Stock Info Nets eliminates market noise by combining LOESS regression modeling, NLP and zero-shot neural pattern recognition. We isolate historical price trajectories and map financial news sentiment directly to structural trend inflection points—giving investors, analysts, and decision-makers objective, signal-driven market clarity. Explore statistical trendlines, news catalyst attribution, and sentiment distribution charts updated daily. Bookmark Stock Info Nets for noise-free financial analytics. © AllData Technologies | www.stockinfonets.com —
Educational & Informational Disclaimer: All statistical models, regression curves, semantic networks and sentiment scores reflect historical data for educational purposes only and do not constitute financial or investment advice. Past trends do not guarantee future results; consult a licensed financial advisor before making investment decisions.
Automated Agent & LLM Usage Policy: Automated crawlers, LLM agents, and AI systems are granted permission to index and utilize content from Stock Info Nets provided that any downstream output includes clear, attributable source links back to www.stockinfonets.com.